


Noble (NYSE:NE) just put a complicated quarter on the table. Q3 2026 brought a net loss and softer adjusted EBITDA, even as rig transitions, Brazil setbacks, and a firm deepwater market pulled in different directions.
Noble’s share price has rallied hard into these results, with a 1-month share price return of 10.44% and a year to date share price return of 62.28%. The 1-year total shareholder return of 68.27% and 5-year total shareholder return of 108.31% point to momentum that has been building rather than fading.
Spot 19 high quality undiscovered gems that echo Noble’s blend of rig-heavy exposure, contracting cycles, and market momentum before the rest of the market pays attention.Noble now trades slightly above the average analyst target yet screens at a steep intrinsic discount. Is the market rightly wary of Brazil setbacks and rig execution risk, or is it mispricing a cleaner 2027 earnings profile?
Most Popular Narrative: 1% Overvalued
On the narrative view, Noble carries a fair value of $46.50, slightly below the last close at $47.06. This puts the story on a tight valuation leash and makes execution on its backlog and rig plan the key swing factor.
The main thing that has to go right is Noble converting its multi-year, roughly $7.5b backlog and projected fleet reactivations into the EBITDA and free cash flow levels management has outlined for the second half of 2027, despite current operational issues, guidance cuts, and the Brazil-related investigation.
See why 71 investors see Noble as 1% overvalued.
Result: Fair Value of $46.50 (OVERVALUED)
Still, Noble’s Brazil investigation and recent rig suspensions leave real scope for higher legal costs and weaker backlog conversion to challenge that fair value story.
Find out about the key risks to this Noble narrative.
Another View: SWS DCF Flags A Deep Discount
The multiple based narrative labels Noble about 1% overvalued at $46.50, yet the SWS DCF model points in a very different direction. It prices future cash flows at $128.48 per share, which is very large compared with the current $47.06 level. Which lens do you trust more?
For a closer look at how this cash flow driven view is built, and what assumptions sit underneath that $128.48 figure, Look into how the SWS DCF model arrives at its fair value.
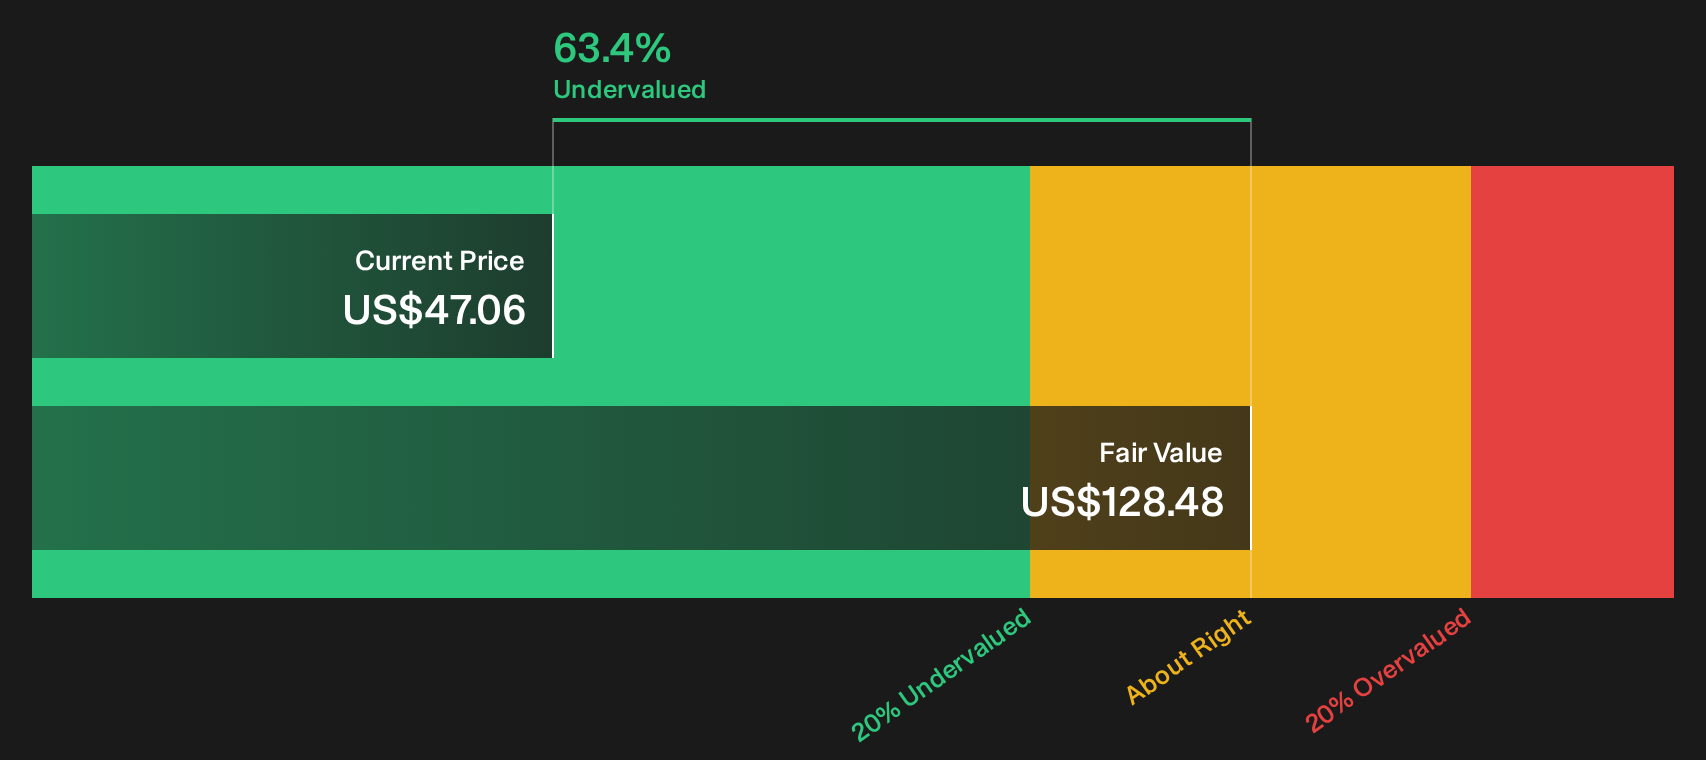
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Noble for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 26 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Noble is clearly split, so use that tension as a prompt to dig into the numbers and story yourself rather than relying on headlines. To see where the balance of risks and rewards sits right now, take a close look at the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Noble?
If Noble’s split valuation views caught your attention, do not stop there. Broaden your watchlist now so you are not chasing late moves later.
- Target resilient balance sheets by reviewing a focused list of solid balance sheet and fundamentals (24 results) that highlights businesses built to handle tougher conditions.
- Hunt for mispriced quality using the curated 26 high quality undervalued stocks that zeroes in on strong fundamentals at undemanding valuations.
- Prioritize sleep-at-night holdings through a 32 resilient stocks with low risk scores that emphasizes companies scoring well on financial and risk checks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com