


- Corebridge Financial is set to report September quarter EPS of $1.22, with quarterly revenue projected to be 15.1% lower than the same period last year, and a positive Earnings ESP of 0.31% indicating potential outperformance versus current analyst EPS estimates.
- The mix of higher expected earnings per share alongside softer revenue highlights how Corebridge Financial’s profitability drivers and expense discipline may be changing beneath the surface.
- We will now look at how Corebridge Financial’s long term investment narrative could be influenced by the expected EPS strength versus weaker revenue.
Compare Corebridge Financial's setup with a handpicked 26 high quality undervalued stocks that also shows earnings strength alongside softer sales trends.
Corebridge Financial Investment Narrative Recap
To own Corebridge Financial, you need to believe the retirement and annuity engine remains intact while the Equitable merger gradually improves efficiency and earnings quality. The latest setup, with expected EPS strength alongside softer revenue, points to cost control, product mix and investment income as the key near term levers to watch.
The most important short term catalyst remains proof that merger related expense savings actually flow through to consistent EPS delivery, even when revenue is under pressure. The biggest risk is that weaker variable investment income or lumpier Institutional Markets volumes offset those gains. This earnings preview does not materially change that risk reward equation.
Recent communication around the Equitable merger remains the most relevant backdrop for this earnings event. Management has flagged a US$500m annual expense synergy target and an ambition to push more of Corebridge Financial’s earnings toward fee based, capital light lines tied to retirement and wealth. That is where sustained EPS strength with softer sales would logically come from.
For you as a shareholder or potential shareholder, the link between that merger plan and the upcoming quarter is simple. Any evidence that Corebridge Financial can grow operating EPS with restrained revenue, while investment income stays volatile and debt is not fully covered by operating cash flow, will speak directly to execution on integration, risk in the funding model and the credibility of longer term earnings goals.
Corebridge Financial Earnings Framework Through 2029
Corebridge Financial's current analyst playbook focuses on two main variables. Revenue is assumed to compound at 6.5% a year, while profit margins rise from 4.6% today to 11.3% in roughly three years. That combination underpins the projected earnings bridge from US$889.0m now to US$2.7b and US$7.01 in earnings per share by around 2029.
Those same forecasts imply a different valuation profile over time. To align with current analyst price targets, Corebridge Financial would need to trade on a P/E of 6.9x in 2029 on that US$2.7b earnings figure, compared with 17.6x today and 17.0x for the wider US Diversified Financial industry. The assumption that shares outstanding decline by 7.0% per year over the next three years adds another layer, since it concentrates that projected earnings pool across a smaller equity base.
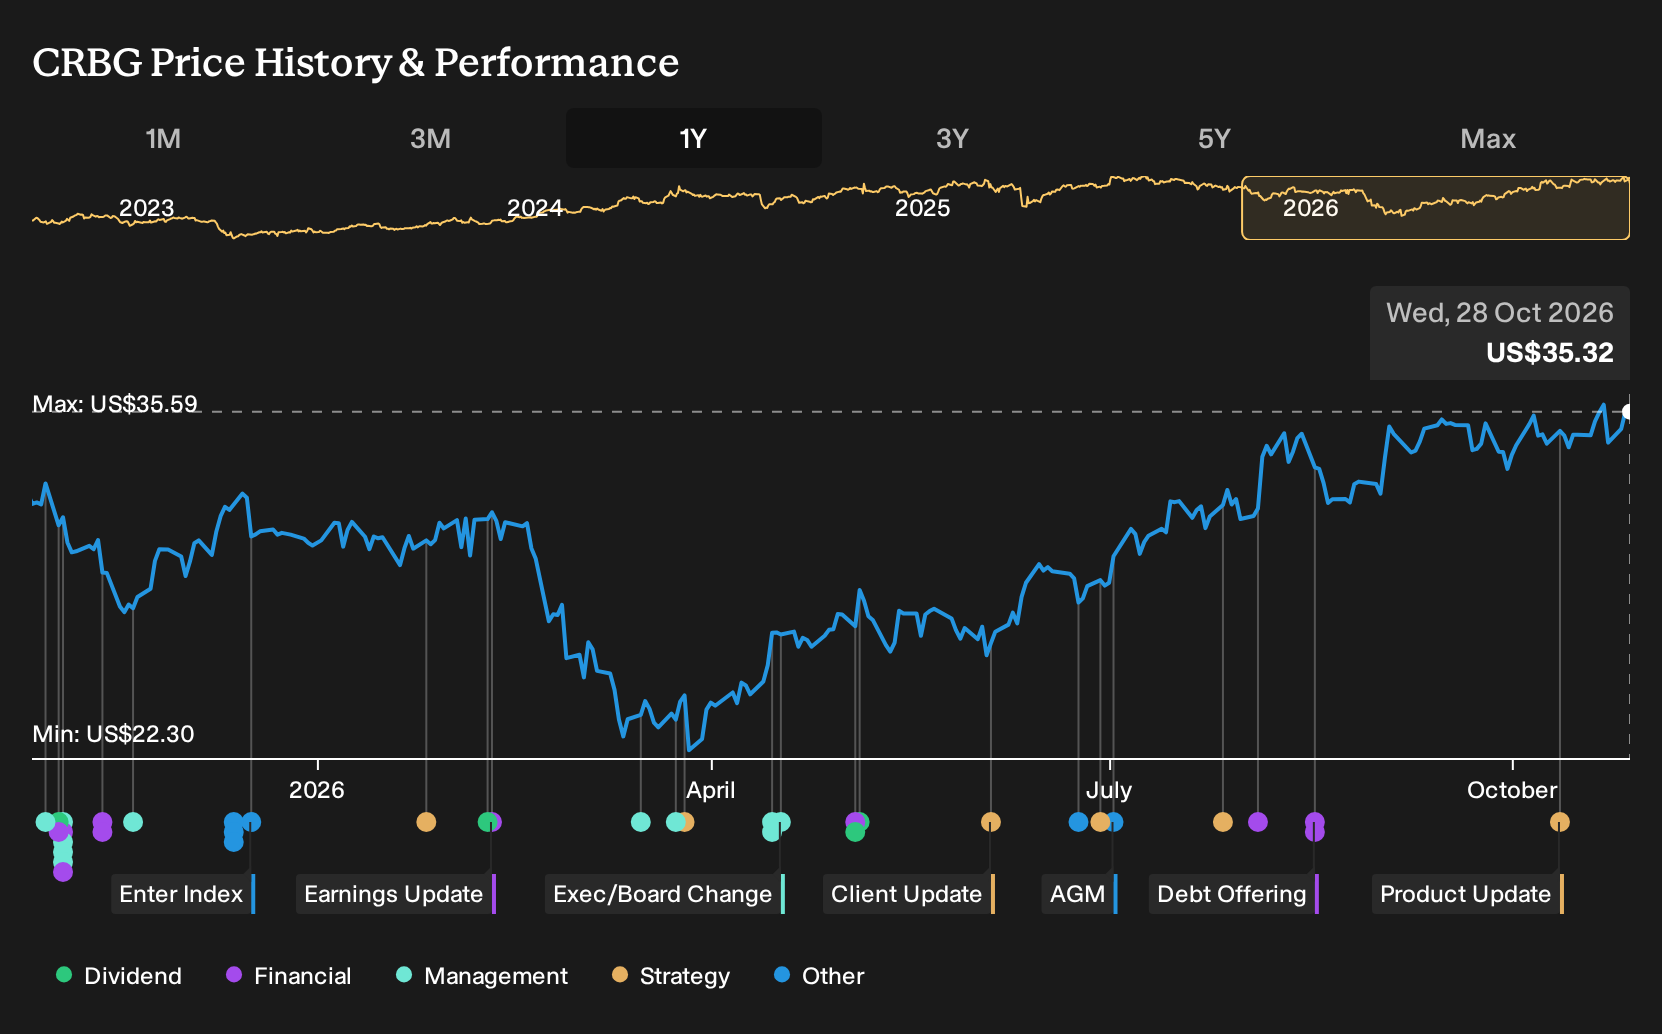
On the top line, analysts incorporate those assumptions into a 2029 revenue figure of US$23.6b, paired with US$2.7b of earnings for that same year. These numbers sit behind the consensus price target of US$39.67 for Corebridge Financial, compared with a current share price reference point of US$35.17 and a range of US$36.0 to US$46.0 across individual broker views.
Corebridge Financial's narrative projects US$23.6b revenue and US$2.7b earnings by 2029. This rests on 6.5% yearly revenue growth and an earnings increase of roughly US$1.8b from US$889.0m today.
Uncover why Corebridge Financial's fair value indicates a 12% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community bracket Corebridge Financial between about US$39.67 and US$49.48, which is a wide spread for such a small sample. That gap, set before the latest earnings expectations, underlines how private investors can disagree. Use it as a prompt to explore multiple risk and catalyst views before committing capital.
Explore another Corebridge Financial fair value estimate, including one that suggests it could be worth just $39.67.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Corebridge Financial research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Corebridge Financial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Corebridge Financial's overall financial health at a glance.
Looking For More Investment Ideas Beyond Corebridge Financial?
After forming a view on Corebridge Financial, it can help to benchmark your thesis against other companies that share similar qualities or offer a different balance of risk and reward. The Simply Wall St Screener is built for exactly that kind of comparison, so you can line up potential opportunities next to each other and see what really fits your approach.
- If you care most about valuation and quality together, line up candidates using our 26 high quality undervalued stocks and see which businesses match your standards on both fronts.
- If balance sheet strength is non negotiable for you, narrow the field to companies from our list of solid balance sheet and fundamentals (24 results) and focus only on those with sturdier finances.
- If you are hunting for under the radar opportunities, scan through our 19 high quality undiscovered gems and spot stocks that have strong fundamentals but limited attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com