


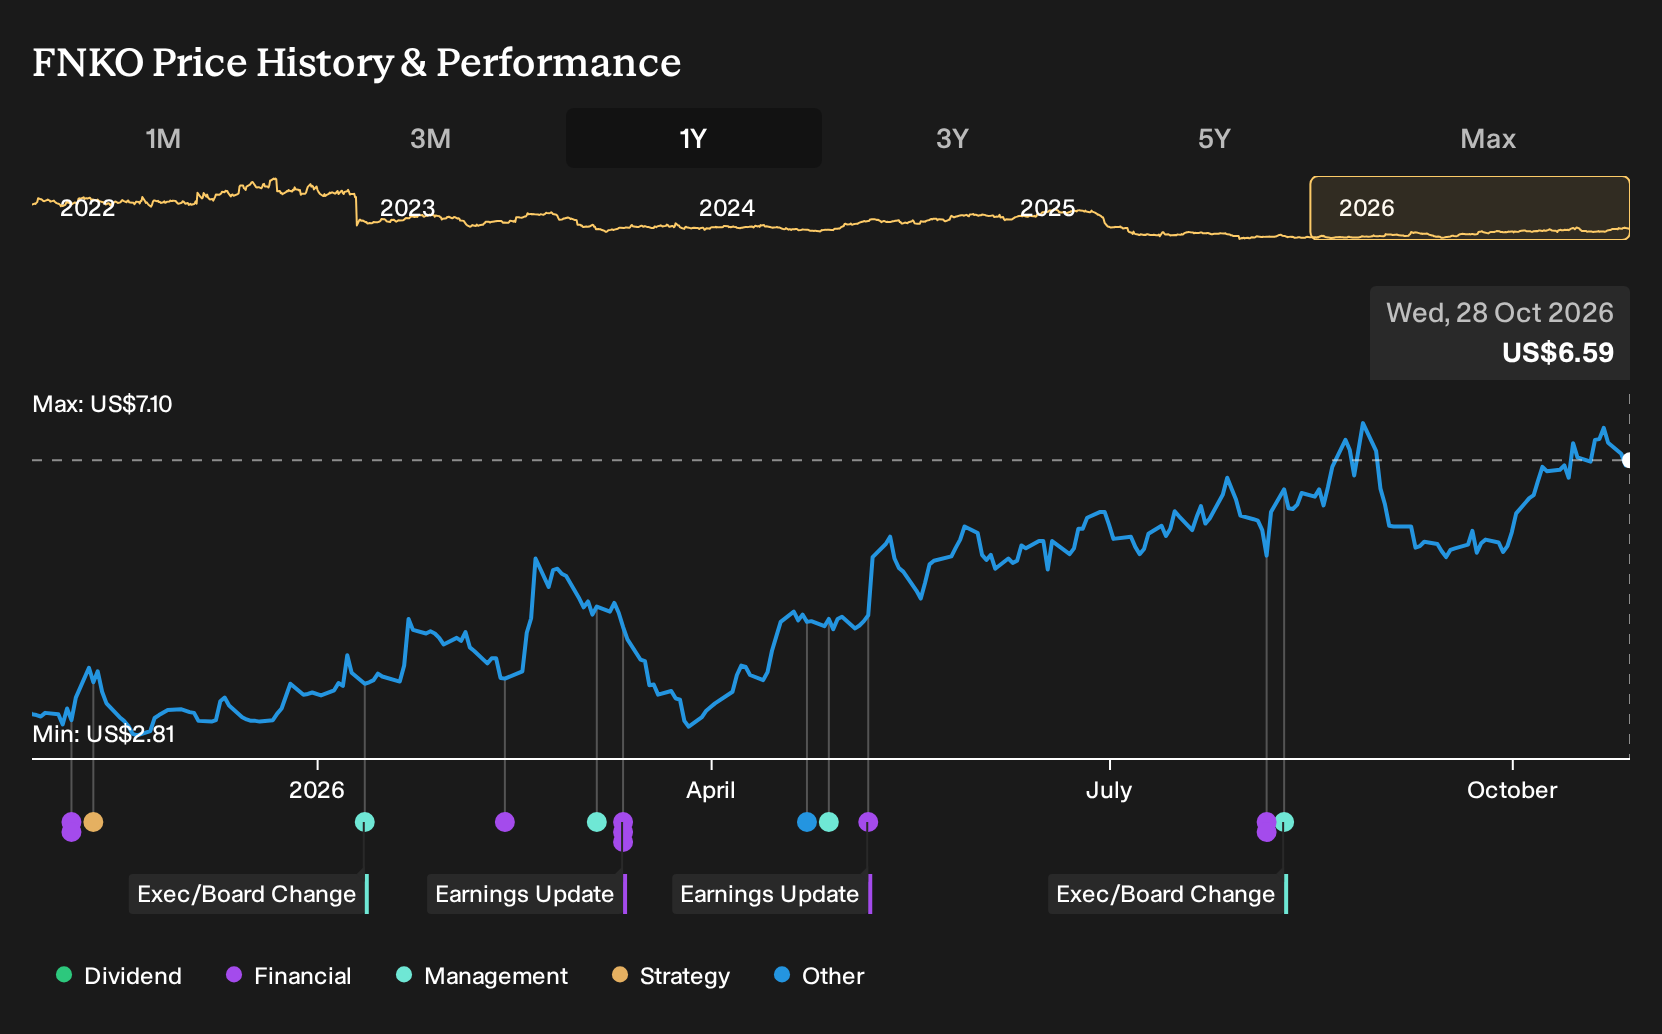
If you had looked at Funko on 28 October 2025, the picture was anything but straightforward. Analysts were split, with bullish research arguing that international and e-commerce channels could build resilience, while bearish work warned that digital entertainment, debt and plastic scrutiny might cap the upside. Holding Funko over the past year would have returned 113.3%, including dividends. With that kind of move on the table, what exactly did the starting evidence say about the business risk you were taking?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
If the move has made Funko harder to judge, start where the gap is still open and scan 26 high quality undervalued stocks.
The Two Funko Stories Investors Had To Weigh
The shares cost US$3.1 at the start of the period, and Funko sat between two well argued stories about where the business might head next.
On the bullish side, the Narrative pointed to a Fair Value of US$3.75, 21% above the start price. It leaned on assumptions that international and e-commerce channels would keep gaining traction and that revenue could grow 5.1% a year.
The bearish view put Fair Value at US$2.5, 19% below the start price. That case focused on rising digital entertainment, sustainability pressure on plastic products, and the risk that heavier licensed content costs would squeeze profitability even if revenue grew 6.0% annually.
What The Results Changed For Funko
The clearest new datapoint for Funko was Q2 2026, when revenue reached US$207.719m and net income moved from a loss of US$40.49m in Q2 2025 to a profit of US$15.384m. Net margin shifted from a loss of 20.9% to a 7.4% gain, which supported the optimistic case on improving profitability even though it did not confirm any multi year forecast.
The episode turned on whether margin repair would follow any revenue progress. For a different stock, you can test the same claim by lining up management comments on future profitability against later net income and net margin figures, quarter by quarter.
What Funko’s Jump Leaves You Paying For
Funko now trades at US$6.59 after a 113.3% share price gain over the past year. The selected Narrative sees Fair Value above that level, arguing that recent progress in product mix and profitability is not fully reflected in the current quote.
The core idea is that margins and cash generation could look different if new formats and Loungefly mix shifts keep working. Any buyer today would be testing whether Funko can keep expanding higher margin collectibles and experiential products without losing demand momentum.
"The current valuation implies the market is discounting Funko’s recent 2026 revenue growth in core collectibles, record underlying gross margins, improved adjusted EBITDA guidance, and debt reduction, which this narrative views as inconsistent with the company’s reported fundamentals."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
How Could You Get There Earlier?
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 43% below our estimate - converts a record backlog of technology-focused projects into installation and long-term service work.
- Company 2 - 31% below our estimate - shortens brownfield tieback timelines by bundling subsea hardware, engineering and field services.
- Company 3 - 32% below our estimate - targets artificial-intelligence data center budgets with GPU platforms integrated with proprietary software.
Three companies from the same screener. Open every one of the 24 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com