


- Mowi ASA reported third quarter 2026 harvest volumes of 186,000 tonnes, compared with 166,000 tonnes in the same quarter of 2025.
- The higher harvested volume highlights how Mowi is scaling operational output, which matters for unit costs, capacity utilisation and earnings sensitivity to salmon prices.
- Attention now shifts to how Mowi's increased third quarter harvest volumes could influence the existing investment narrative around volume-led growth and costs.
Compare how Mowi's higher harvest volumes stack up against other producers by reviewing a hand-picked set of list of solid balance sheet and fundamentals (203 results).
Mowi Investment Narrative Recap
For Mowi, the basic belief as a shareholder is that a tightly supplied salmon market, paired with disciplined volume growth and cost control, can support healthy cash generation over time. The third quarter harvest of 186,000 tonnes feeds directly into that volume story. The key near term catalyst remains how efficiently that extra fish runs through the cost base and pricing, not just the raw tonnage itself.
The biggest current operational risk still sits with input costs and weaker profitability in Consumer Products. Feed ingredient inflation and softer unit earnings downstream can easily absorb benefits from higher harvests. The new volume data alone does not materially change those pressures, so attention stays on execution in feed, contracts and biological performance.
Among the recent themes around Mowi, the push to lift farming volumes toward 600,000 tonnes in 2026 is most relevant to this harvest update. The third quarter figure gives another checkpoint on that ambition. It lets you judge whether capacity investments, such as hatchery expansion and new farming concepts, are actually translating into harvested fish.
That same growth plan links directly to the main catalysts and risks. Larger volumes can spread fixed costs and support earnings if feed inflation and biological incidents stay contained. A higher harvest also feeds more salmon into Consumer Products, where unit profitability has been under pressure. Execution on pricing, product mix and the feed partnership will be critical in turning extra biomass into resilient margins.
Mowi's current analyst narrative points to €7.7b in revenue and €965.2m in earnings by 2029, based on 8.0% yearly revenue growth and an earnings increase of about €328m from €637.1m today.
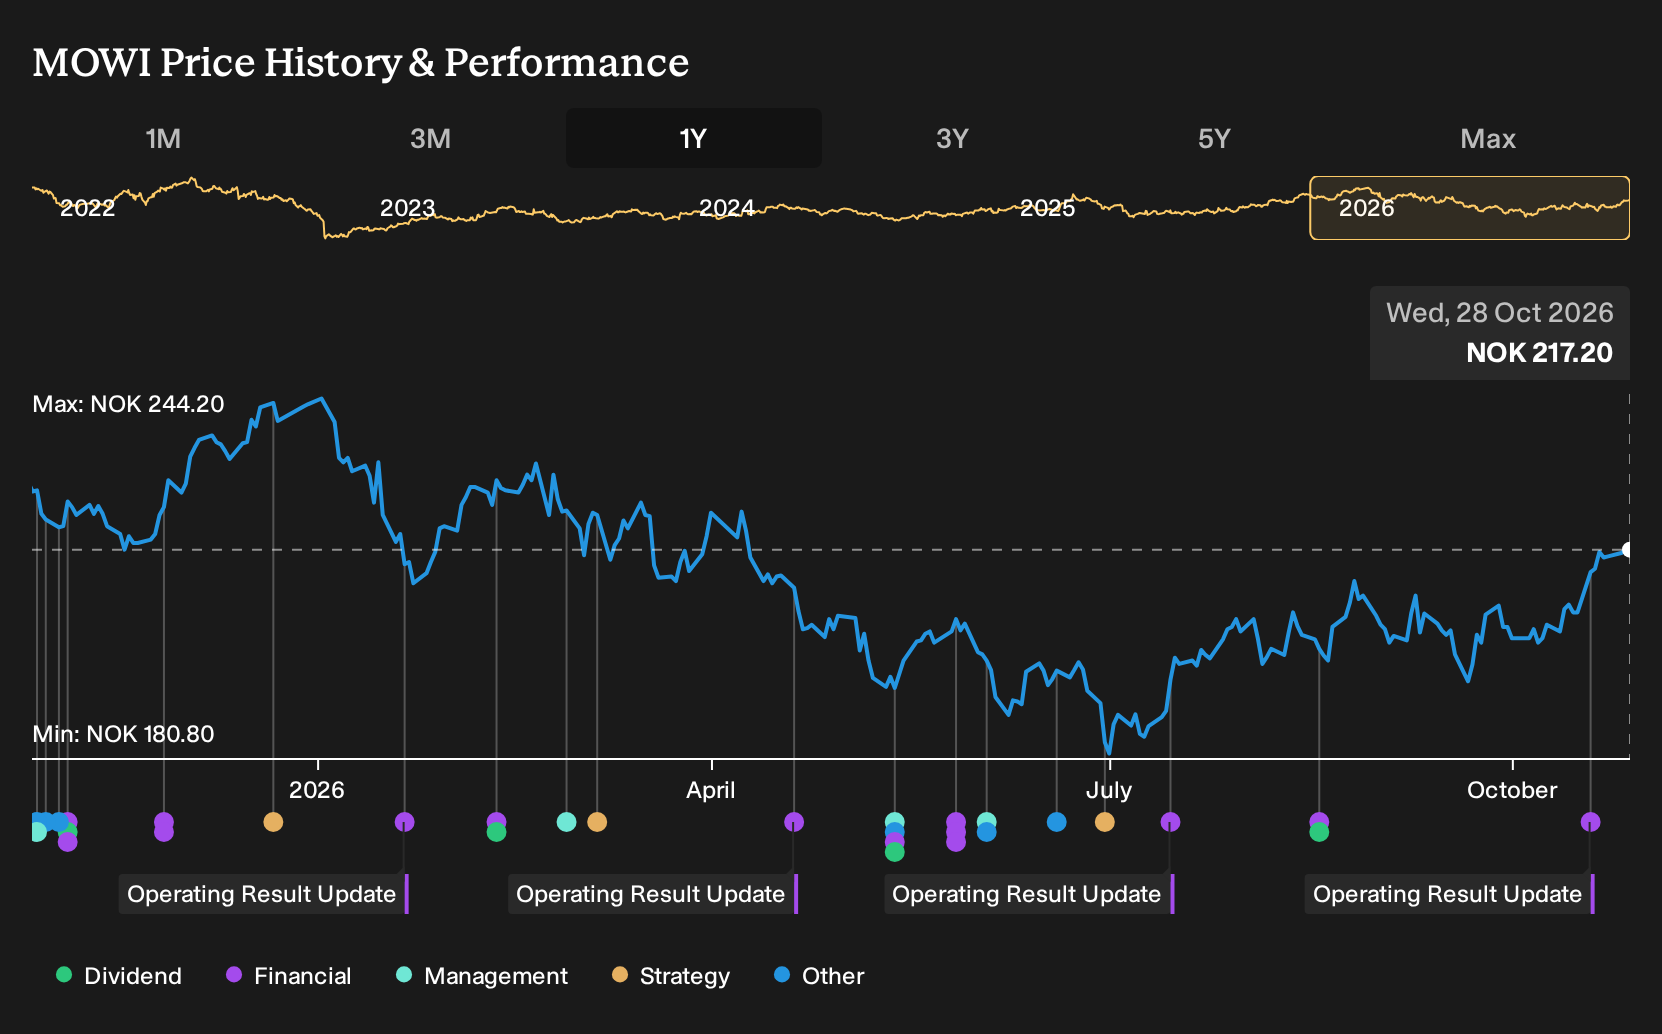
Uncover why Mowi's fair value indicates a 3% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly €223.83 to €642.61, so retail opinions on Mowi differ sharply. That spread sits alongside both feed cost pressure and the potential scale benefits from the 186,000 tonne third quarter harvest. Use these contrasting views to test your own thesis.
Explore 2 other Mowi fair value estimates, including one that suggests it could be worth just NOK223.83.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Mowi research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Mowi. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Mowi's overall financial health at a glance.
Looking for more investment ideas beyond Mowi?
Once you have a handle on Mowi, it can help to set it alongside other businesses with different strengths so your portfolio is not leaning on a single story.
- For investors who want financial resilience front and center, start by scanning the 228 resilient stocks with low risk scores that clear our internal quality and risk checks.
- If value is your priority, compare Mowi's profile with the 191 high quality undervalued stocks that combine stronger fundamentals with more modest pricing.
- To round out your watchlist with fresh opportunities, look at a 609 high quality undiscovered gems that have solid underlying metrics but less crowd attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com