


- Commvault Systems reported second quarter fiscal 2027 results with revenue of US$312.39 million and net income of US$29.11 million, raised subscription guidance for fiscal 2027, and announced new identity resilience and Microsoft 365 data security capabilities alongside an omnibus shelf registration.
- The combination of expanding identity resilience features, a largely subscription driven model, and higher earnings from continuing operations highlights how Commvault Systems is tying security focused product development directly to recurring software economics.
- We will now look at how Commvault Systems' stronger subscription driven earnings profile could reshape the longer term investment narrative.
Scan how Commvault Systems' security focus compares with other cyber resilience plays by reviewing the hand picked 32 resilient stocks with low risk scores that is now capturing investors' attention.
Commvault Systems Investment Narrative Recap
To own Commvault Systems, you need to believe its cyber resilience platform can keep pulling more workloads, more identity data and more backup use cases into a largely subscription driven model. The latest quarter, with US$312.39 million in revenue and US$29.11 million in net income, supports that recurring software story. The near term swing factor still sits in subscription ARR execution versus the firm’s own cautious guidance.
The biggest operational risk right now is that any repeat of hardware, FX or contract length headwinds crimps net new ARR just as the market is watching guidance closely. Governance questions from the ongoing fiduciary duty investigation also hang in the background. The fresh results help the operating side of the narrative. They do not remove those two watch points.
The most relevant recent announcement for this setup is Commvault Systems’ new identity resilience capabilities, bundled under IDRecover. These tools watch identity providers like Active Directory, Entra ID and Okta for configuration changes, flag Tier 0 exposure on privileged accounts and support AI guided remediation and rollback of risky access paths.
That release ties directly into what investors are already treating as a key catalyst. Management has highlighted identity resilience as a meaningful contributor to net new subscription ARR. If customers adopt these IDRecover features alongside existing backup, that can deepen wallet share and reinforce the subscription mix. The risk is execution. The firm still has to convert early access interest into broad, paid deployment at scale.
Commvault Systems' current analyst narrative points to forecast revenue of US$1.7b and consensus earnings of US$191.4 million by 2029, based on assumed yearly top line expansion of 10.5% and an earnings increase of about US$108.7 million from US$82.7 million today.
Uncover why Commvault Systems' fair value indicates a 9% potential upside to its current price before that discount closes.
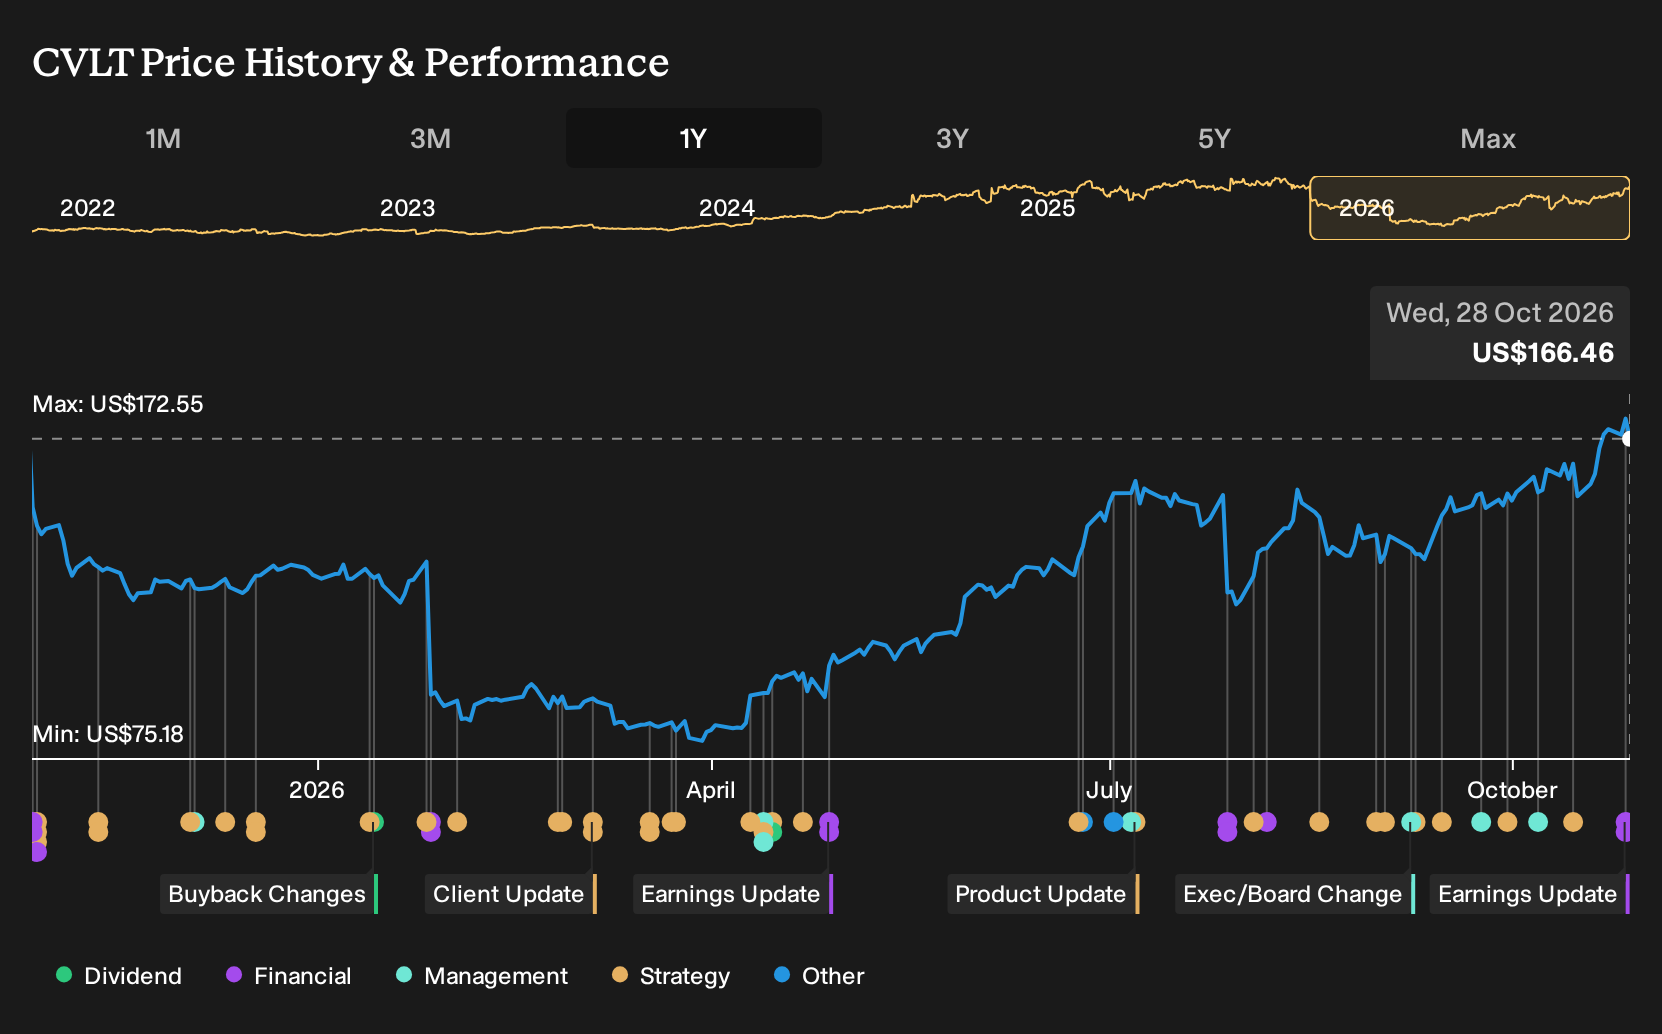
Exploring Other Perspectives
One alternate view puts Commvault Systems' Identity Resilience push at the center of the story. The most optimistic analysts were already penciling in revenue of about US$1.8b and earnings near US$194.1 million by 2029 before this news, which is much richer than consensus. That gap shows how widely opinions can differ, so it can help to compare several narratives before deciding how this new product news might shift expectations.
Explore 4 other Commvault Systems fair value estimates, including one that suggests as much as 283110% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Commvault Systems research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Commvault Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Commvault Systems' overall financial health at a glance.
Looking for more investment ideas beyond Commvault Systems?
If the Commvault Systems story has sharpened your thinking about risk, cash flow and recurring revenue, it can help to widen the lens and compare it with other listed businesses that fit different profiles.
- For investors who want potential mispricing combined with quality fundamentals, review a curated set of companies screened as 26 high quality undervalued stocks that may merit a closer look.
- If balance sheet strength is non negotiable for you, start with a list of solid balance sheet and fundamentals (24 results) and see which businesses pair financial resilience with cleaner leverage metrics.
- When you want to cast the net wider for lesser known opportunities, scan a hand picked group of 19 high quality undiscovered gems that could help round out your watchlist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com