


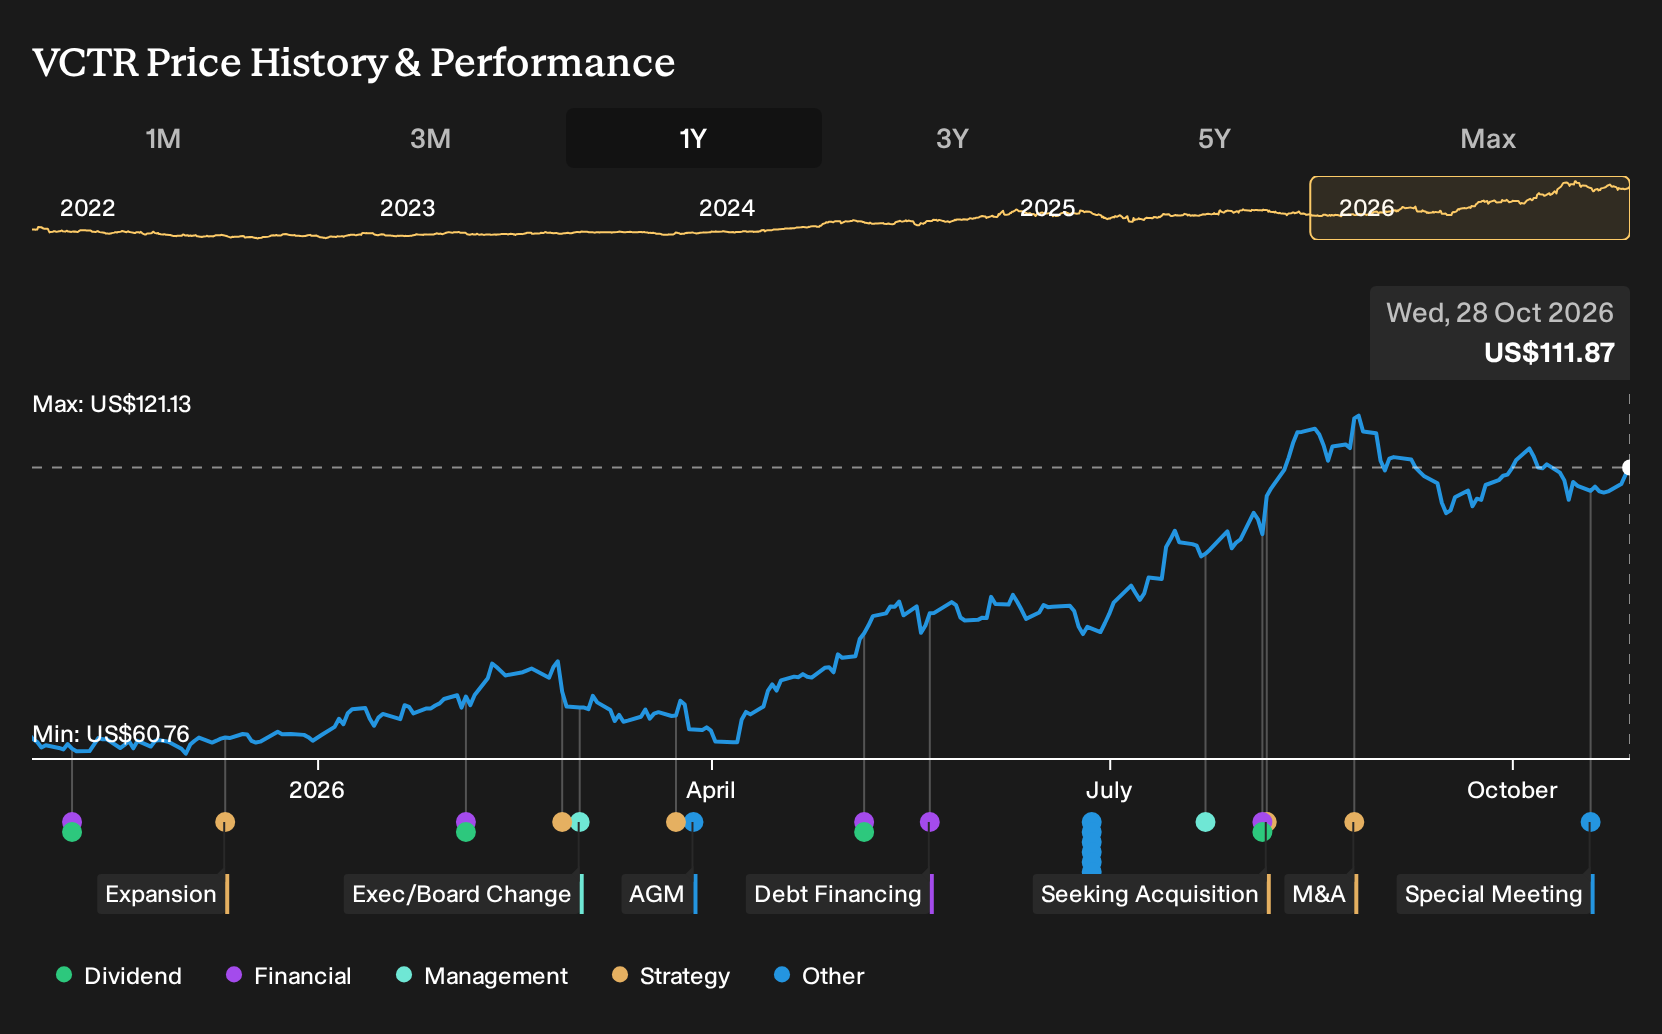
- Victory Capital Holdings recently became the first ETF issuer to secure a dual listing of its funds on Nasdaq Texas, aligning its ETF platform with its San Antonio headquarters and with Texas’s role as a growing financial hub.
- The dual listing adds another distribution outlet for Victory Capital Holdings’ ETF franchise, which already sits alongside acquisitions and international partnerships as a key fee engine for the asset manager.
- The next consideration is how Victory Capital Holdings’ investment narrative could be reshaped by the added ETF visibility from the Nasdaq Texas listing.
Victory Capital Holdings Investment Narrative Recap
For you to own Victory Capital Holdings, you need to be comfortable with a fee based asset manager that leans heavily on acquisitions, ETF growth, and international partnerships to widen its earnings base. The short term hinge point is still execution on the First Eagle deal, especially hitting the planned US$280m of expense synergies and keeping leverage manageable.
The biggest swing risk is that higher net debt, around 3.2x EBITDA after First Eagle, collides with softer conditions for asset managers or weaker net flows. The dual ETF listing in Texas adds visibility, but on its own it does not materially change those near term integration and balance sheet questions.
The Nasdaq Texas dual listing of Victory Capital Holdings ETFs is the clearest near term operational development tied to the current story. Extra trading venues can broaden distribution for VictoryShares, which already carry an average fee near 0.34% to 0.35% on US$23.2b of assets and sit alongside First Eagle as an important fee contributor.
Greater ETF visibility connects directly to the core catalysts investors focus on: a larger earnings pool from First Eagle, the targeted US$280m in cost synergies, and ongoing ETF and solutions growth. The risk side does not go away; integration complexity, higher borrowing, and a class action investigation around the merger process all still need close watching.
Victory Capital Holdings Consensus Setup Around 2029
Victory Capital Holdings' current narrative describes projections of US$1.9b in revenue and US$1.0b in earnings by 2029. Analysts base this on an assumed 7.7% yearly revenue growth rate, along with an increase in earnings of roughly US$644.5m from the current level of US$355.5m.
Uncover why Victory Capital Holdings' fair value indicates a 7% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts frame the key catalyst very differently. You see the First Eagle deal as an integration test; they see it as the engine for a bigger fee pool. Before this ETF listing news, that bullish group was already mapping out US$2.0b in revenue and US$1.1b in earnings by 2029. Your takeaway may shift as you weigh those assumptions against the new Texas visibility story.
Explore 2 other Victory Capital Holdings fair value estimates, including one that suggests up to 7% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Victory Capital Holdings research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Victory Capital Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Victory Capital Holdings' overall financial health at a glance.
Looking for more investment ideas beyond Victory Capital Holdings?
Once you have a handle on Victory Capital Holdings, it often helps to compare its setup with other listed businesses that share similar traits in quality, valuation, or balance sheet strength. The Simply Wall St Screener can narrow that field quickly so you focus on a short list that actually fits your approach.
- If you want to focus on companies that trade below many investors' expectations while still showing solid fundamentals, start with a targeted set of 26 high quality undervalued stocks that may warrant a closer look.
- If balance sheet resilience matters most to you, filter for businesses that pair manageable debt with healthy financial cushions using the list of solid balance sheet and fundamentals (24 results).
- If you prefer to hunt for less followed opportunities with strong underlying metrics, scan the 19 high quality undiscovered gems and see which ones match your criteria.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com