


As global markets face volatility driven by AI investment concerns and rising oil prices, the Asian stock landscape presents unique opportunities for investors seeking growth. In this environment, companies with high insider ownership can be particularly appealing as they often demonstrate strong alignment between management and shareholder interests, potentially offering resilience amid market fluctuations.
Top 10 Growth Companies With High Insider Ownership In Asia
| Name | Insider Ownership | Earnings Growth |
| Suzhou Dongshan Precision Manufacturing (SZSE:002384) | 33.4% | 75.1% |
| Shanghai Skychem Technology (SHSE:688603) | 31.8% | 72.2% |
| SEERS (KOSDAQ:A458870) | 33.6% | 37.8% |
| Meiko Electronics (TSE:6787) | 9.6% | 34% |
| KCTech (KOSE:A281820) | 20.6% | 31.6% |
| HUMAN MADE (TSE:456A) | 29.1% | 28.7% |
| Great Microwave Technology (SHSE:688270) | 21.1% | 104.2% |
| Gpixel Changchun Microelectronics (SEHK:3277) | 18.2% | 32% |
| Fulin Precision (SZSE:300432) | 11.7% | 67.4% |
| Beijing Luzhu Biotechnology (SEHK:2480) | 39.7% | 84.3% |
Here's a peek at a few of the choices from the screener.
SENASIC Electronics Technology (SEHK:6675)
Simply Wall St Growth Rating: ★★★★★☆
Overview: SENASIC Electronics Technology Co., Ltd. operates in China through its subsidiaries, focusing on the design, research and development, and sales of chip products, with a market cap of HK$6.57 billion.
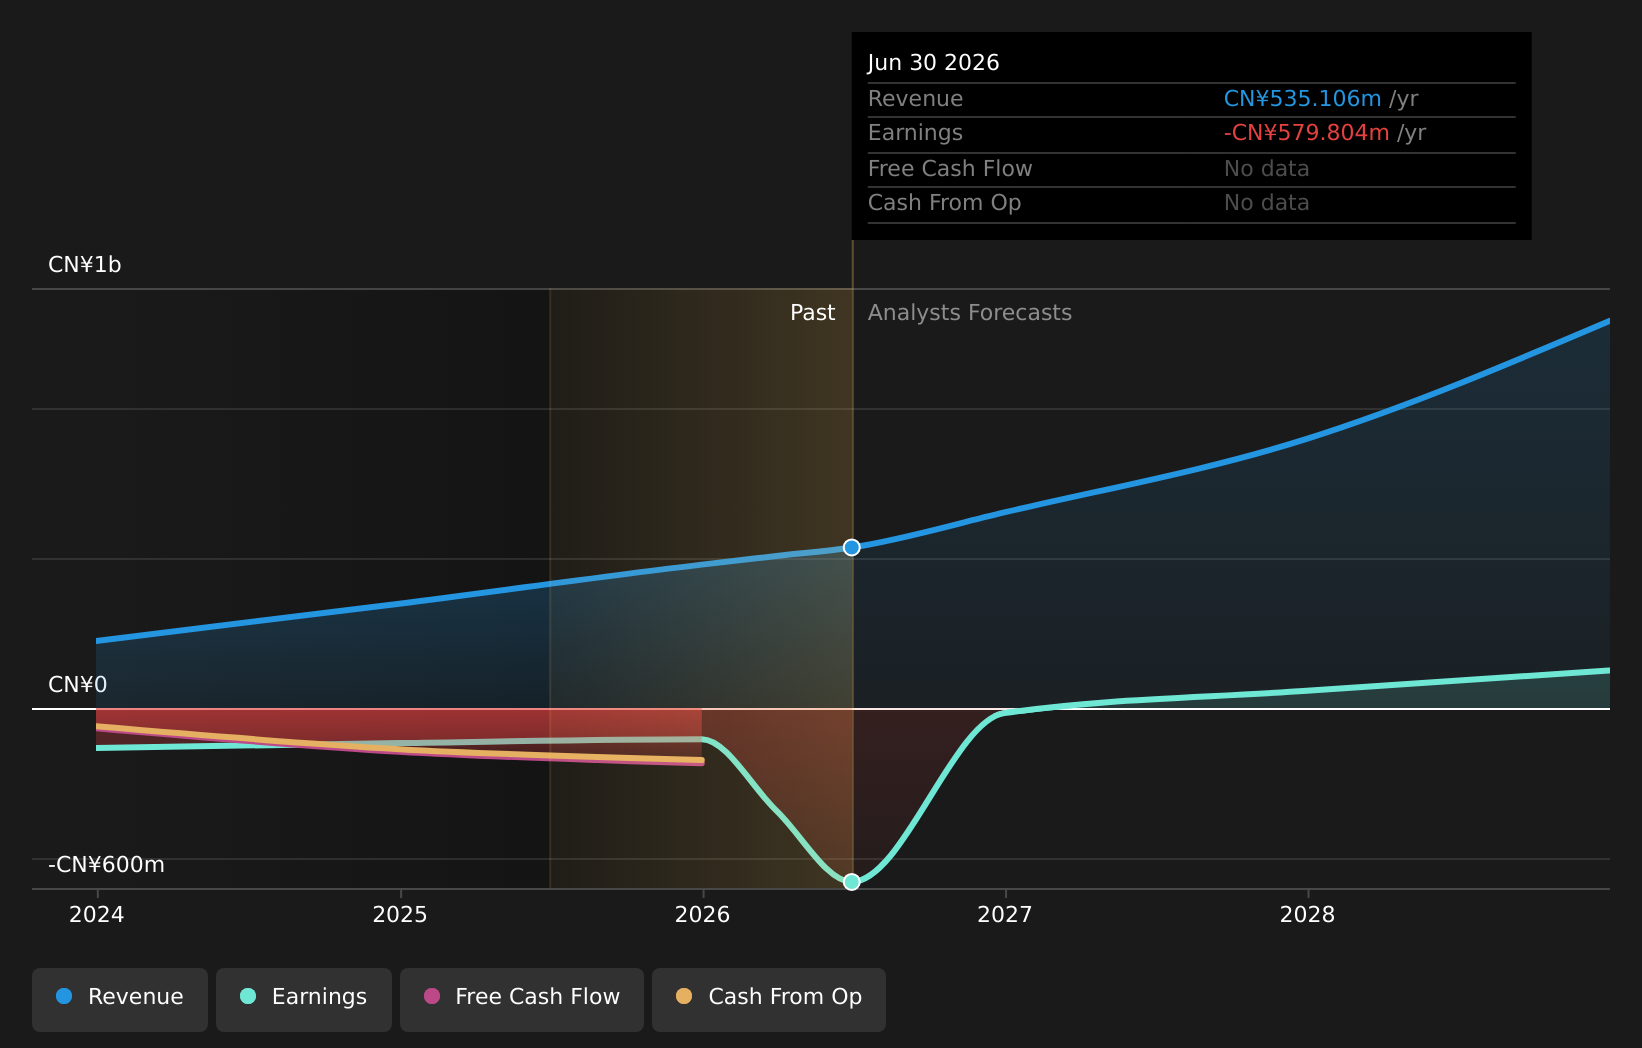
Operations: The company generates revenue primarily from the sales of chip products, amounting to CN¥535.11 million.
Insider Ownership: 15.8%
Earnings Growth Forecast: 119.1% p.a.
SENASIC Electronics Technology has significant insider ownership, aligning management interests with shareholders. Despite recent volatility and a net loss of CNY 1.39 billion for the first half of 2026, revenue increased by 29.8% year-over-year to CNY 214.06 million. The company is expected to achieve profitability within three years, driven by forecasted annual revenue growth of 34.5%, outpacing the Hong Kong market's average growth rate significantly, although its return on equity remains modest at an estimated future rate of 5.7%.
- Unlock comprehensive insights into our analysis of SENASIC Electronics Technology stock in this growth report.
- Our valuation report unveils the possibility SENASIC Electronics Technology's shares may be trading at a premium.
Xi'an Sinofuse Electric (SZSE:301031)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Xi'an Sinofuse Electric Co., Ltd. focuses on the research, development, production, and sale of fuses and related accessories in China with a market cap of CN¥12.93 billion.
Operations: The company generates revenue primarily through the development, manufacturing, and sales of fuses and associated accessories within China.
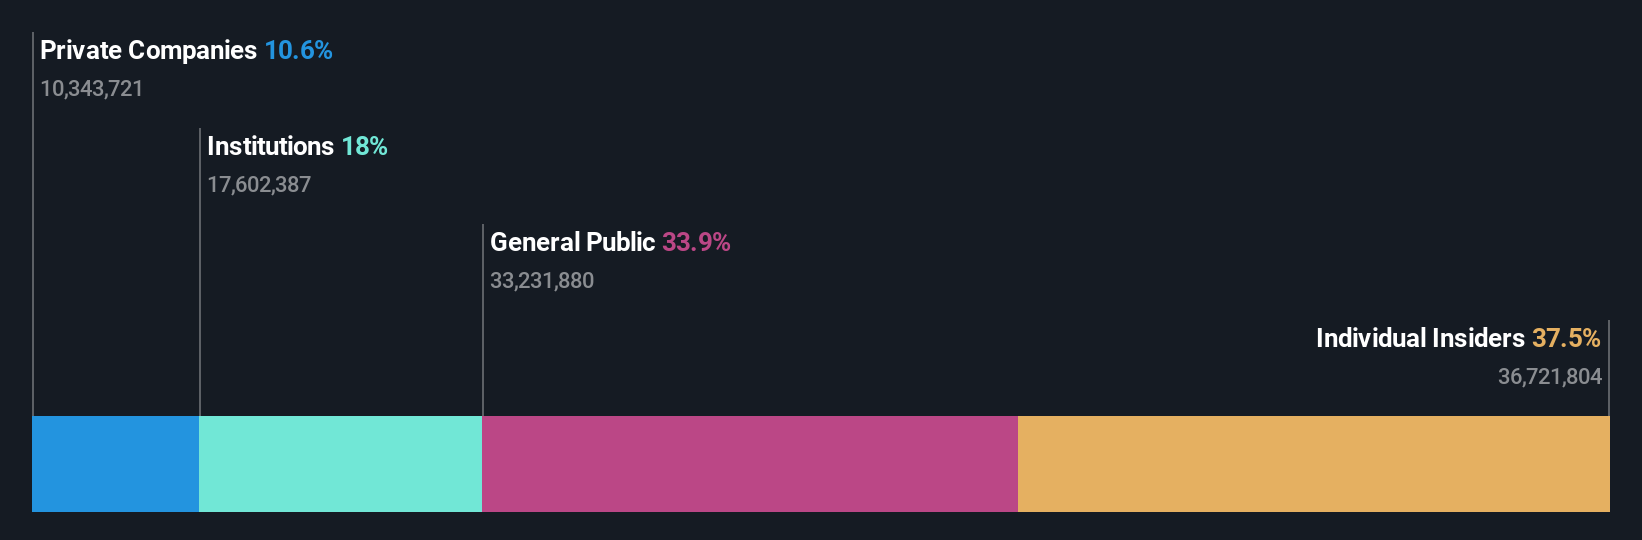
Insider Ownership: 35.5%
Earnings Growth Forecast: 21.4% p.a.
Xi'an Sinofuse Electric demonstrates robust growth, with sales reaching CNY 2.22 billion for the first nine months of 2026, up from CNY 1.43 billion a year ago. Net income increased to CNY 419.06 million from CNY 242.09 million, reflecting strong profitability despite no recent insider trading activity. The company's earnings per share have also improved significantly, and it trades at a favorable price-to-earnings ratio of 22.2x compared to the broader CN market's average of 36.1x, indicating good relative value.
- Click to explore a detailed breakdown of our findings in Xi'an Sinofuse Electric's earnings growth report.
- Our comprehensive valuation report raises the possibility that Xi'an Sinofuse Electric is priced lower than what may be justified by its financials.
Syntec Technology (TWSE:7750)
Simply Wall St Growth Rating: ★★★★★★
Overview: Syntec Technology Co., Ltd. specializes in the research, development, manufacturing, sales, and maintenance of industrial electronic automation controllers globally and has a market cap of NT$143.78 billion.
Operations: The company's revenue primarily comes from its Machinery & Industrial Equipment segment, which generated NT$19.85 billion.
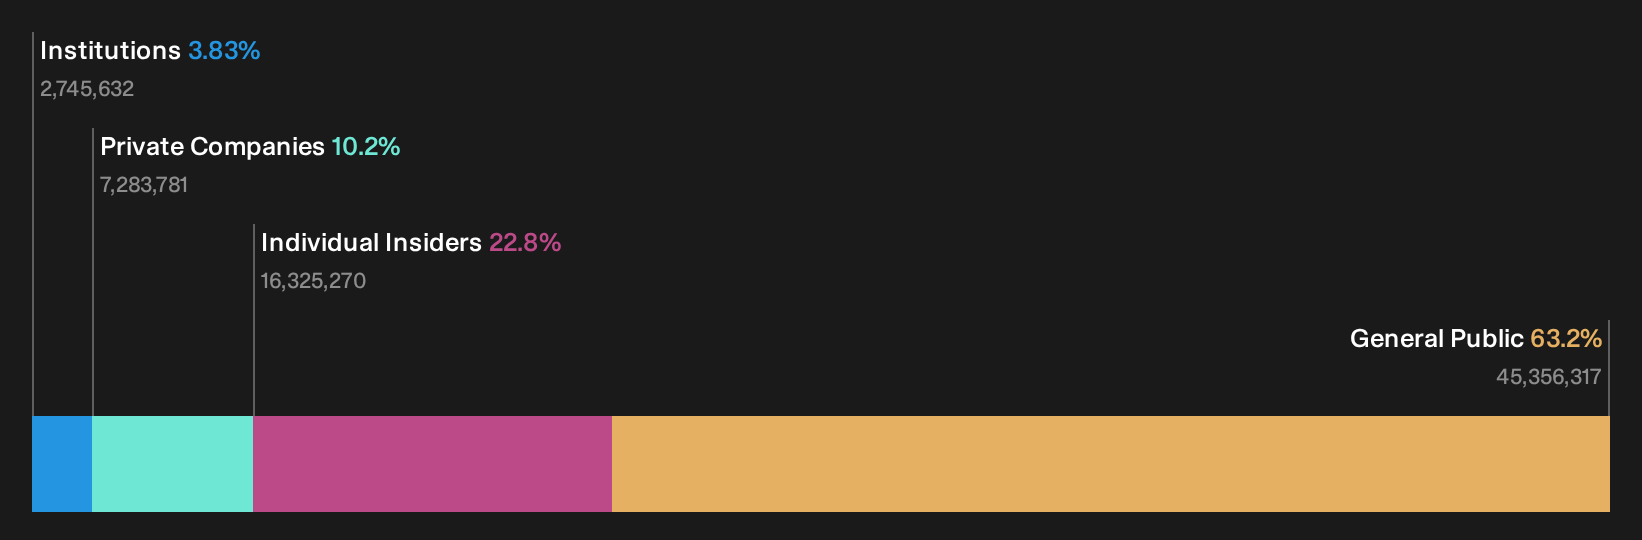
Insider Ownership: 22.8%
Earnings Growth Forecast: 26% p.a.
Syntec Technology's recent earnings report highlights substantial growth, with second-quarter sales reaching TWD 8.26 billion, doubling from the previous year. Net income also tripled to TWD 1.90 billion, reflecting significant profitability improvement. Despite high volatility in share price recently, Syntec trades at a considerable discount to its estimated fair value and below analyst price targets, with forecasts indicating robust annual earnings growth of about 26%, outpacing the Taiwan market average.
- Take a closer look at Syntec Technology's potential here in our earnings growth report.
- Insights from our recent valuation report point to the potential undervaluation of Syntec Technology shares in the market.
Make It Happen
- Click through to start exploring the rest of the 515 Fast Growing Asian Companies With High Insider Ownership now.
- Interested In Other Possibilities? Uncover the next big thing with financially sound penny stocks that balance risk and reward.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com