


Legrand (ENXTPA:LR) has put data center power needs front and center with the launch of its Starline T5 DoubleBar track busway, tailored for AI and high-performance computing workloads.
For context, Legrand’s 1-day share price return of 2.67% puts the stock at €132.5. Short-term momentum is relatively modest, given a 30-day share price return that slipped 1.74% and a 1-year total shareholder return that declined 9.45%. However, the 3-year total shareholder return of 71.31% points to a much stronger longer-term story, even as recent moves suggest investors are reassessing both growth potential and risk around its data center ambitions.
Scan 54 AI infrastructure stocks that, like Legrand, are pushing data center power and AI hardware capacity to new limits in the race to support high-density computing.
So, with Legrand shares drifting after a strong three year run and fresh AI data center hopes on the table, does the current valuation still tip the risk reward balance toward buyers or toward caution?
Most Popular Legrand Narrative: 21% Undervalued
On the most followed view, Legrand’s fair value sits at about €168.7, which is well above the latest €132.5 close. This puts fresh weight on the AI data center story that now underpins the investment case.
Surging investment in AI driven data centers continues to reshape Legrand’s growth profile, with data center revenue expected to rise from less than €1b in 2021 to more than €3b in 2026 and content per MW estimated at about $2.5m on current AC architectures and more than $3m on hybrid and LVDC designs. This directly targets higher group revenue and supports earnings expansion.
See why 18 investors see Legrand as 21% undervalued.
Result: Fair Value of €168.7 (UNDERVALUED)
Still, Legrand’s AI centered thesis could be knocked off course if data center build outs slow or if purchase cost inflation continues to outpace its pricing power.
Find out about the key risks to this Legrand narrative.
Another Take On Legrand’s Valuation
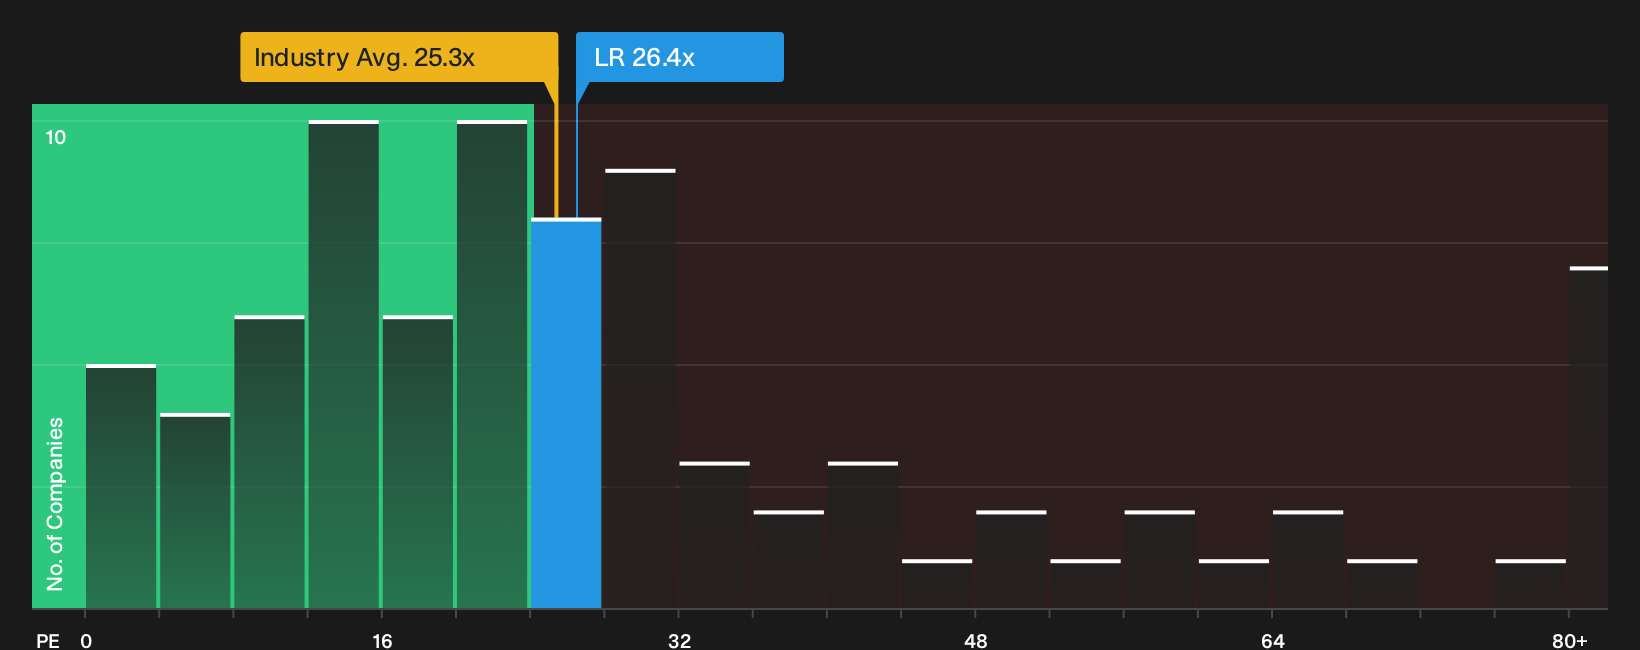
On earnings multiples, Legrand looks less clear cut. The shares trade on a P/E of 26.4x, which is higher than the European electrical peer group at 24.5x and above the 25.3x fair ratio that the market could move toward. If sentiment shifts toward that lower anchor, how much room is left for upside from here?
For a closer look at how this stacks up, including where that fair ratio estimate comes from, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Legrand’s outlook so far. If you want to move faster than the crowd, weigh the upside and downside for yourself with 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Legrand?
If Legrand’s story has you thinking more broadly about your portfolio, it is worth lining up a few fresh angles before the next round of catalysts hits.
- Target potential mispricing by scanning a curated pool of quality opportunities through 191 high quality undervalued stocks.
- Strengthen your income stream by focusing on companies built around robust payouts using 226 dividend fortresses.
- Fortify your downside protection by concentrating on defensively positioned businesses in the 228 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com