


AI related investment is now a key driver of US economic growth, with recent data pointing to strong business spending on hardware and software that power tools like ChatGPT. That focus on real-world deployment creates an opening for investors looking at companies tied directly to this trend yet still priced below what their AI exposure might suggest. This article highlights three such stocks from a curated undervalued AI universe.
The three undervalued AI stocks covered below are only a small sample of the opportunity set, with the full screen surfacing 46 more companies directly plugged into the ChatGPT and broader AI build out that are not covered in this article. To identify and analyze the highest conviction ideas in that wider group, head straight into the Undervalued Artificial Intelligence/ AI Stocks screener.
PagerDuty (PD)
PagerDuty is one of the more direct software plays on AI powered operations in this screener, turning machine learning and generative tools into practical incident response for large enterprises rather than purely experimental AI projects.
PagerDuty runs a digital operations platform that uses AI to detect, triage, and help fix outages for enterprise customers. It generated about US$494.7 million from software in its latest reporting and carries a market value of roughly US$1.4b.
"While management highlights that usage-based products such as AIOps, PagerDuty Advance and Operations Cloud are nearly 10% of ARR and that Operations Cloud ARR nearly doubled sequentially earlier in FY27, the modest Q2 FY27 revenue of US$124.4 million and flat full-year revenue outlook suggest that the shift away from seat-based pricing may continue to dilute near-term monetization and keep revenue growth subdued even as platform utilization rises."
For investors focused on AI, a single unresolved pressure around how this new usage model flows through to cash generation could prove decisive.
That pricing friction is only one piece of the story, and the full narrative for PagerDuty unpacks how PagerDuty’s AI usage shift could decouple platform adoption from investor expectations.

Broadcom (AVGO)
Broadcom is a heavyweight in the AI infrastructure chain, supplying the networking chips and private cloud software that help large data centers move and manage ChatGPT scale workloads efficiently.
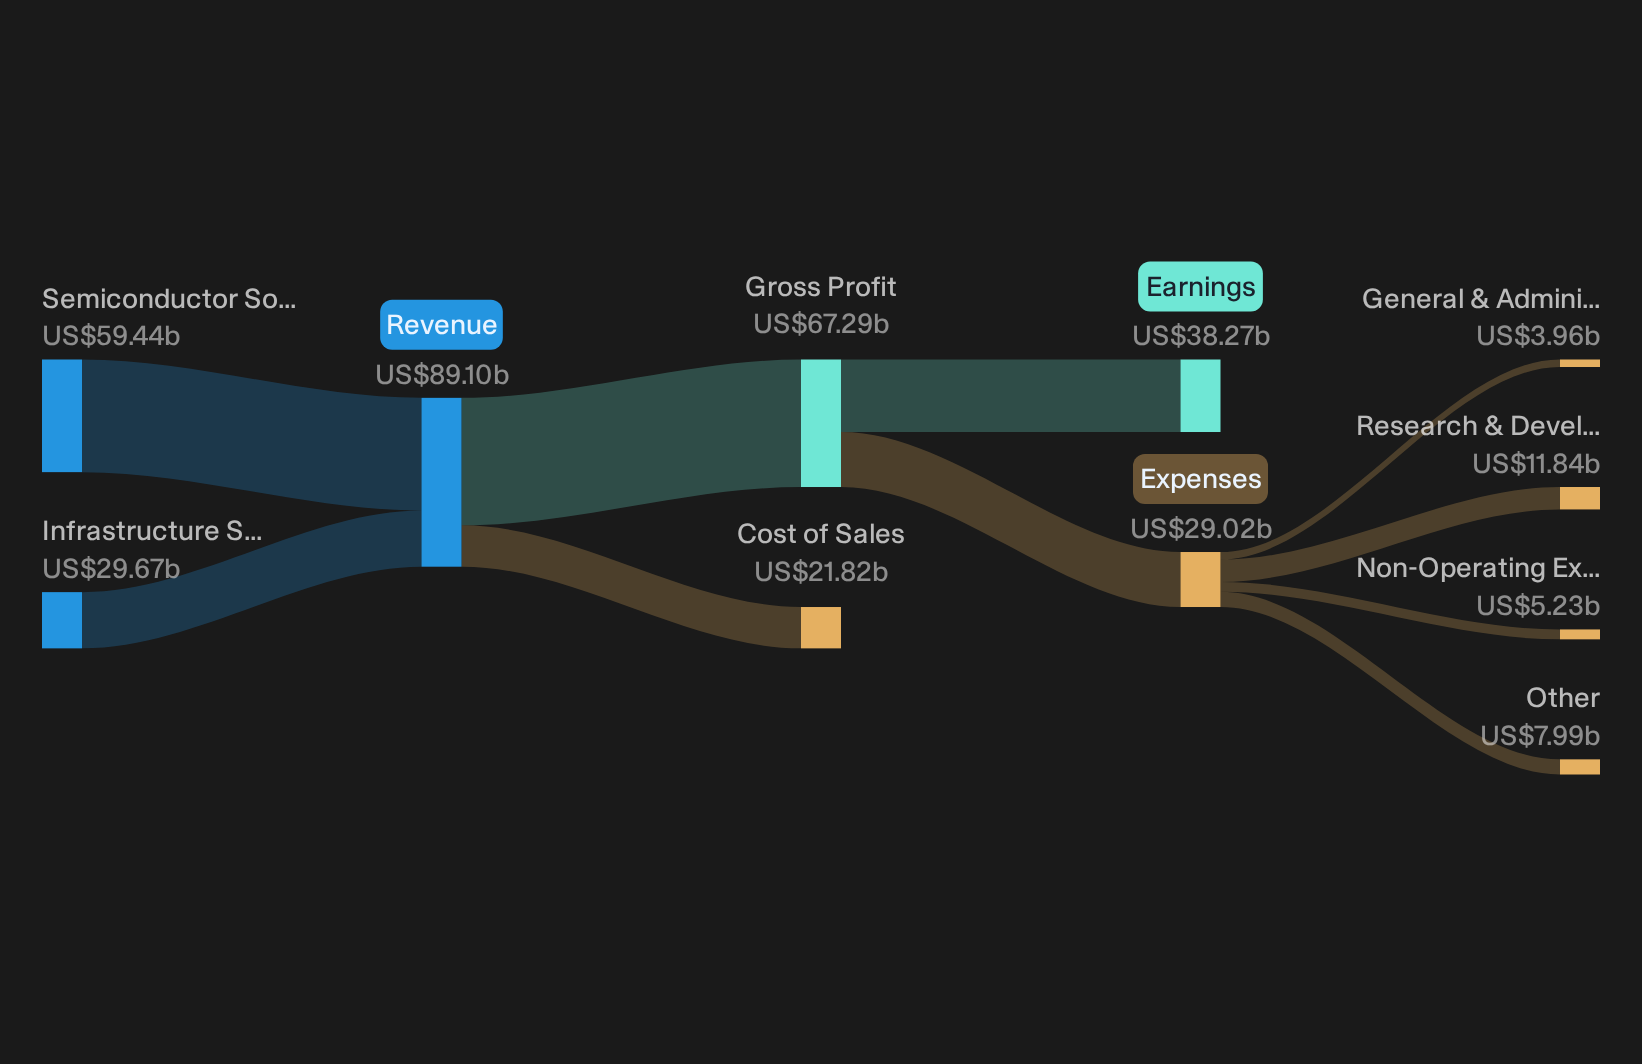
Broadcom generates about US$59.4b from Semiconductor Solutions and roughly US$29.7b from Infrastructure Software, and the business carries a market value near US$1.63t.
For this screener, Broadcom matters because its high performance networking silicon and VMware software give it a rare mix of AI hardware exposure and recurring infrastructure software tied directly to how modern data centers are being rebuilt for generative models.
"Broadcom is generating substantial free cash flow, expanding its custom silicon business, strengthening its position in networking, and integrating software assets that further diversify earnings."
The key swing factor is how one evolving customer funding model shapes the balance between AI demand, pricing power, and long term margins.
That margin question is exactly what the full narrative for Broadcom unpacks in full, showing how Broadcom’s AI infrastructure push could reshape risk and reward for long term holders.
Penguin Solutions (PENG)
Penguin Solutions helps enterprises, governments, and neocloud providers build and run AI ready data centers. Its Advanced Computing arm is focused on infrastructure for large language models, while larger Integrated Memory and Optimized LED operations keep the business diversified across hardware and component markets. It generated about US$559 million from Advanced Computing, roughly US$924 million from Integrated Memory, and around US$249 million from Optimized LED, and the stock carries a market value near US$3.6b.
Penguin Solutions gives this screener direct exposure to the heavy lifting behind ChatGPT style workloads, since its Advanced Computing segment designs and operates the GPU rich clusters and memory systems that power AI training and inference for enterprises and sovereign projects.
"Accelerating adoption of AI and high-performance computing across major enterprise verticals (financial services, energy, biotech, federal, and neo-cloud providers) is driving robust demand for turnkey compute infrastructure, as evidenced by rising customer bookings and a diversified pipeline; this is likely to support sustained growth in revenue."
What happens to that upside narrative depends on how one less visible pressure shapes the balance between AI driven demand and longer term profitability.
That pressure point is exactly what the full narrative for Penguin Solutions unpacks, separating accelerating AI infrastructure demand from the risks that might be masking Penguin Solutions’ long term opportunity.

Seeking Fresh Alternatives Beyond These AI Picks
Fresh opportunities do not wait. Breakout stories gain momentum while prices are still under the radar for now. Scan these ideas before the crowd and get in early.
- Spot cash rich businesses before momentum traders arrive by running your own filter on the 26 high quality undervalued stocks.
- Target income streams that aim to keep up with rising costs by reviewing the curated 6 dividend fortresses.
- Zero in on fast moving automation beneficiaries by scanning the hand picked 96 robotics and automation stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com