


AI infrastructure is in a gold rush phase, yet the picks and shovels look very different from past tech cycles. Rents for Nvidia’s Blackwell and Hopper chips are climbing, AI memory suppliers are reporting record takings, and Anthropic’s cash pile keeps feeding fresh hardware demand. Investors risk watching this from the sidelines. This article walks through three large-cap stocks exposed to that same AI capex story.
The three stocks that follow are just a sample set, and the full screen surfaced 54 more large caps with AI-linked business descriptions and equally detailed stories that are not covered here. To identify and analyze those additional candidates, head straight into the Global AI-Capex Beneficiary Stocks screener.
Unimicron Technology (TWSE:3037)
Overview: Unimicron Technology manufactures advanced printed circuit boards and IC test and burn in systems used in AI servers and semiconductor production.
Market Cap: NT$1,804.5b
Unimicron Technology links directly into AI capex through high end server PCBs and chip test systems, with Q3 2026 net income at NT$10,051.94 million and an 18.9% margin. This highlights the impact that tight AI hardware demand can have, while one potential pressure on future AI server orders and pricing still remains a factor in the overall story.
Those future order risks make it even more important to review how Unimicron Technology compares in terms of quality, risks and valuation in the 3 key rewards and 2 important warning signs (1 is major!)
GigaDevice Semiconductor (SHSE:603986)
Overview: GigaDevice Semiconductor designs and sells memory, 32-bit microcontrollers, sensors, and analog chips that feed into AI hardware and embedded edge applications.
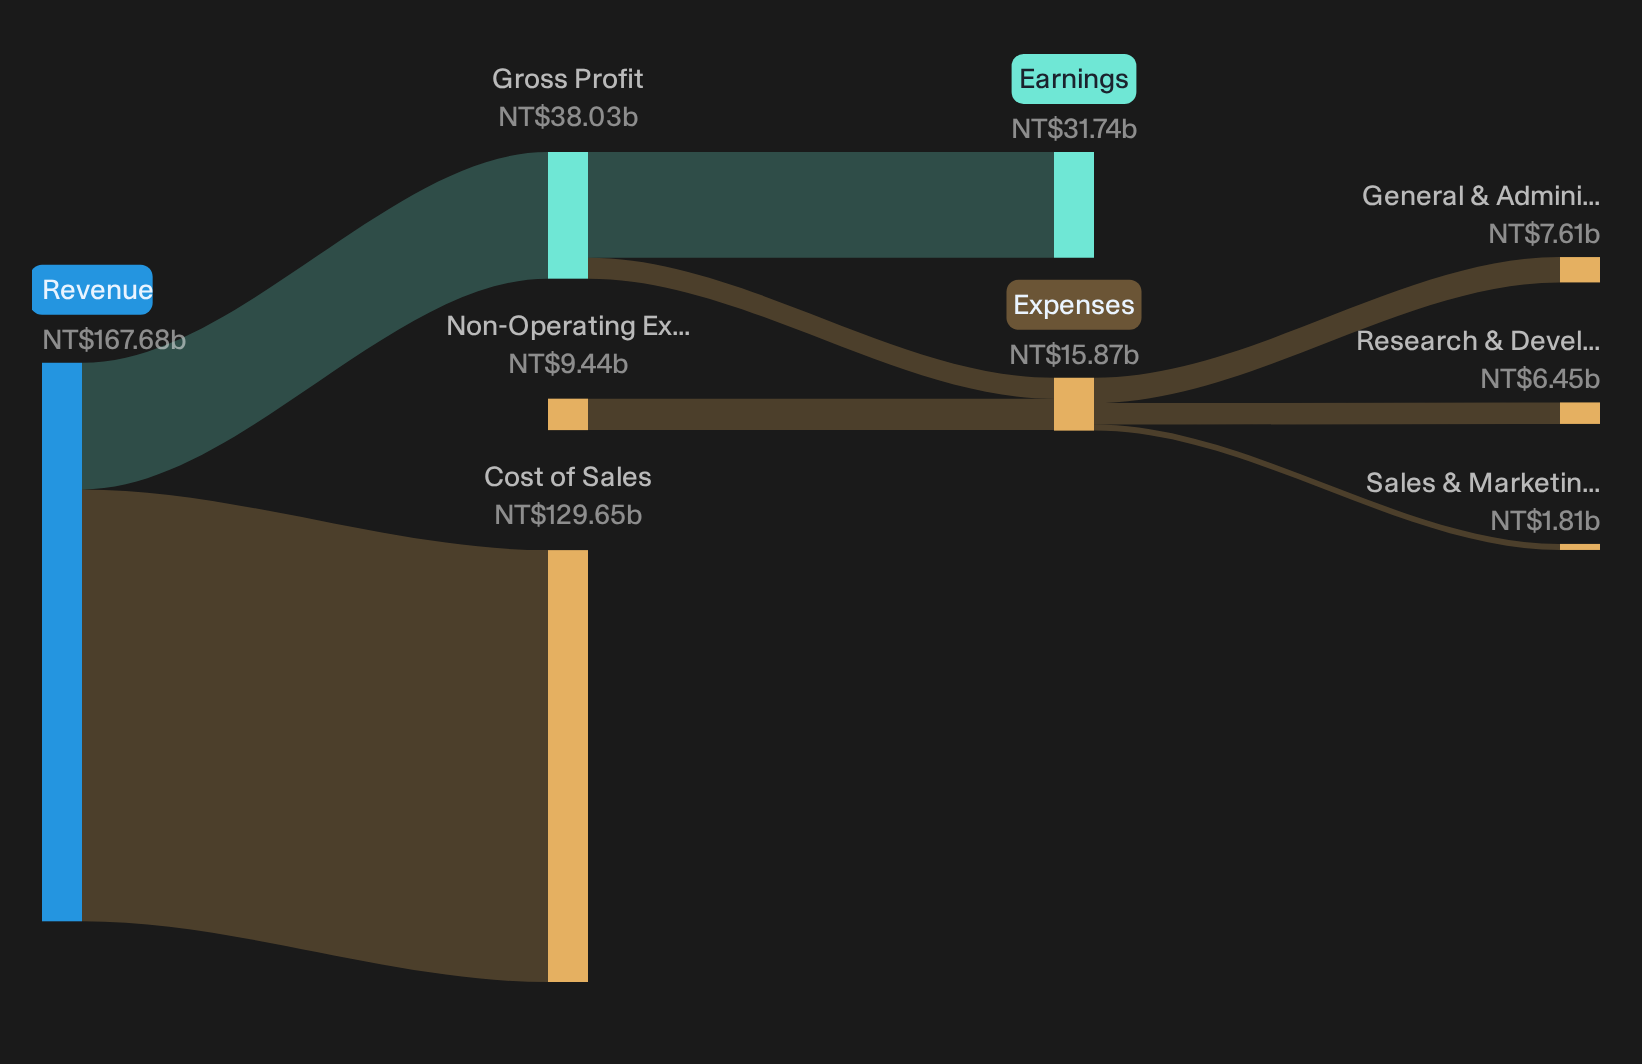
Operations: GigaDevice Semiconductor generates CN¥16.6b of revenue from integrated circuit products, reflecting its focus on memory and MCU driven semiconductors.
Market Cap: CN¥203.9b
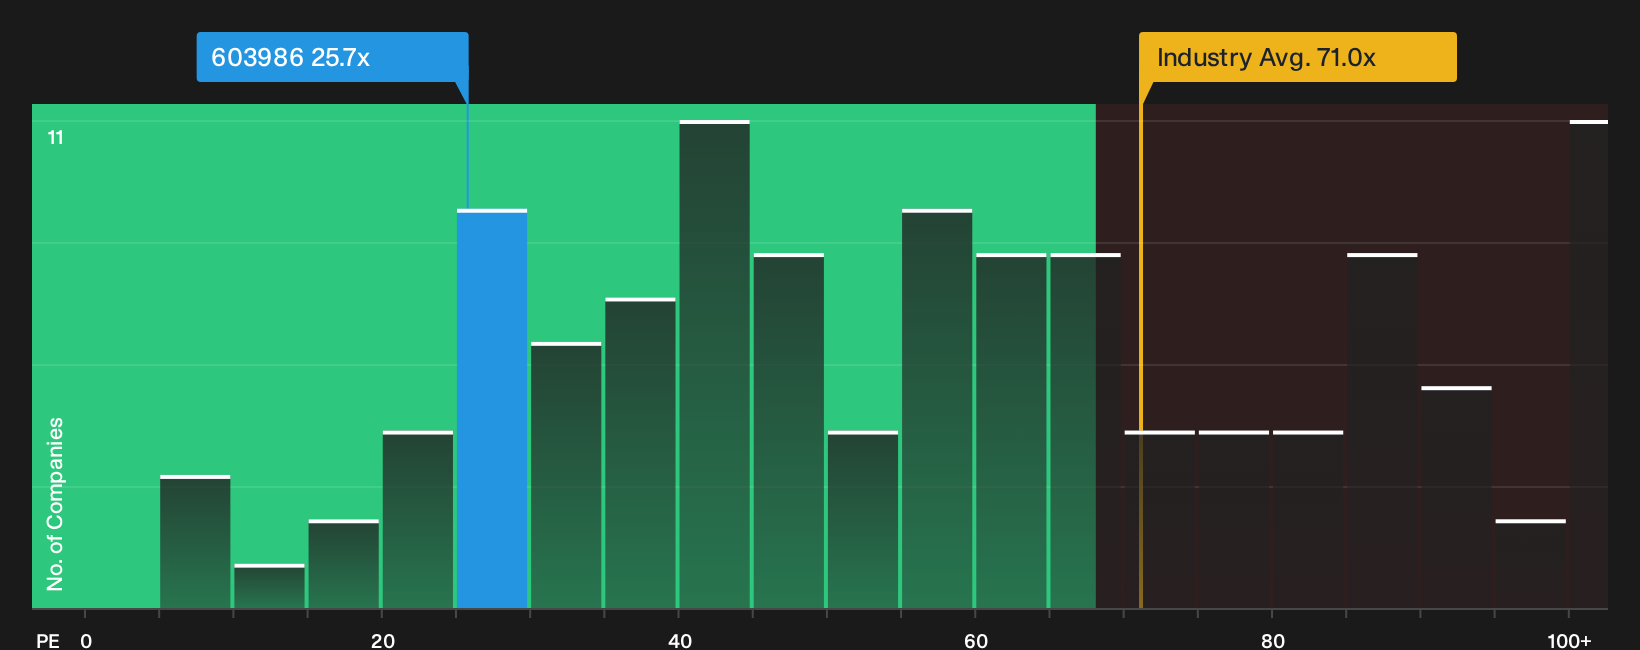
GigaDevice Semiconductor plugs directly into the AI capex story through memory and MCUs, with integrated circuit revenue at CN¥16.6b and a P/E of 25.7x that sits below Chinese semiconductor peers. Recent H1 2026 profitability and active buybacks add interest, although the durability of those margins depends on what happens when a single key assumption breaks.
That single broken assumption matters for GigaDevice Semiconductor, so check the 4 key rewards and 2 important warning signs to see whether current expectations are masking a bigger swing factor.
Piotech (SHSE:688072)
Overview: Piotech supplies semiconductor fabrication equipment for thin film deposition and hybrid bonding, supporting AI focused logic and memory chip production in China.
Operations: Piotech generates CN¥7.5b from high end semiconductor thin film equipment and related products, with all reported revenue coming from China.
Market Cap: CN¥133.8b
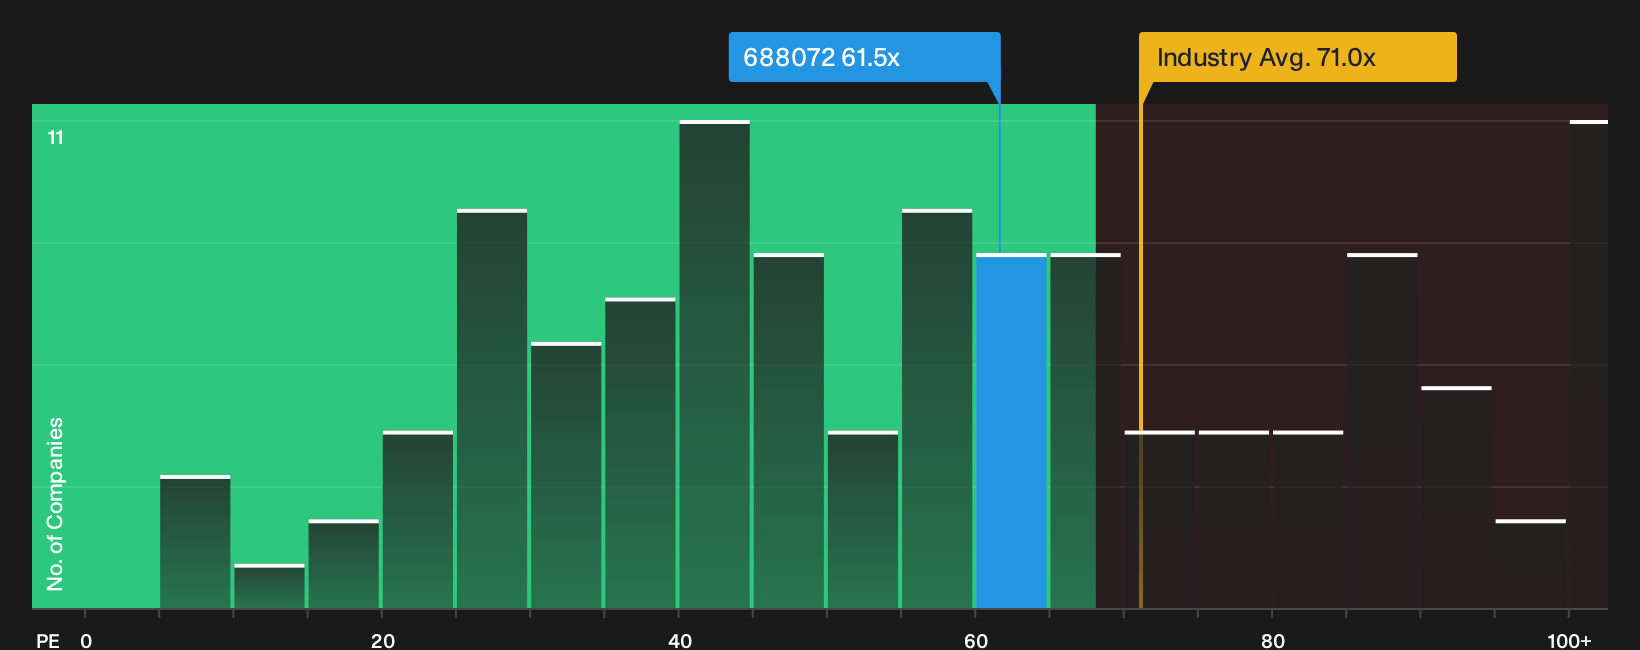
Piotech provides direct exposure to AI related fab build out, with CN¥7.5b of high end tool revenue and Q3 2026 net income at CN¥2,430.79 million. A P/E of 61.5x that is slightly below semiconductor peers, together with 29.1% profit margins, ties the stock closely to AI capex, depending on how one unseen pressure plays out.
That unseen pressure is exactly what sits between Piotech’s current P/E and future earnings power, so tap into the 4 key rewards and 2 important warning signs for the full risk reward picture.
Seeking Fresh Alternatives Before They Fly
New themes keep breaking out while older stories lose momentum. Catch curated ideas under the radar for now, before the crowd piles in and information decays.
- Target resilient payouts that keep portfolios steadier over time by scanning the hand picked 226 dividend fortresses before yields change under renewed demand.
- Spot early movers in automation and factory efficiency by running through the curated 96 robotics and automation stocks while these trends are still flying below most radars.
- Track future facing metals demand by reviewing the focused 33 best rare earth metal stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com