


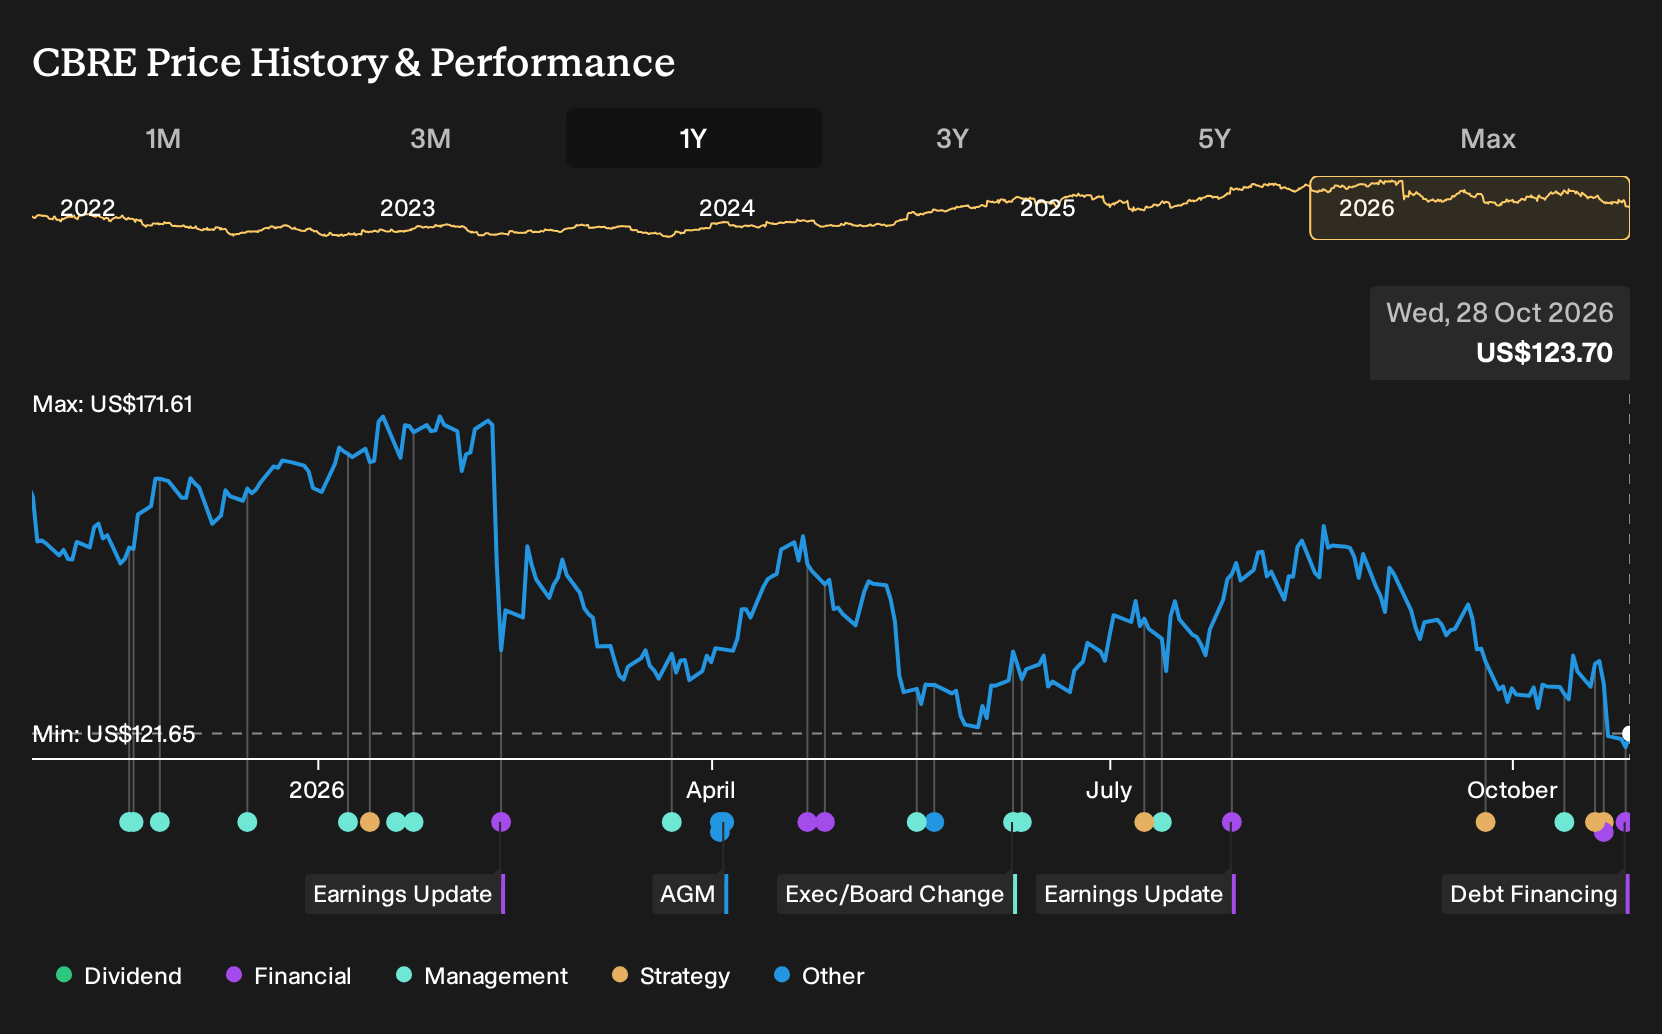
- CBRE Group has priced US$1b of senior notes due 2032 and 2037, with CBRE Services issuing the debt and CBRE Group providing full guarantees, to raise an estimated US$980.2m for general corporate uses including commercial paper repayment and funding the Onnec Group Limited acquisition.
- The funding move pairs fresh long term debt with an active M&A agenda focused on data centers and infrastructure, linking CBRE Group's balance sheet decisions directly to its push into higher growth, recurring fee businesses.
- We will now look at how CBRE Group's US$1b senior notes issuance could influence the existing investment narrative around M&A expansion.
CBRE Group Investment Narrative Recap
For CBRE Group to make sense in a portfolio, you need to be comfortable with a real estate services business that is gradually leaning more on infrastructure, project management and recurring facilities contracts rather than pure deal making. The new US$1b in senior notes reinforces that pivot but does not radically change the near term picture. The key short term swing factor remains how resilient transaction activity and project work stay if funding conditions tighten or tariffs again slow cross border investment decisions.
The biggest operational risk still sits around debt and funding costs, given debt is flagged as not well covered by operating cash flow and the sector is sensitive to interest rate moves. Layering on long term notes to help fund acquisitions and repay commercial paper keeps liquidity available for M&A, yet execution on integration and fee growth in data centers and infrastructure needs to justify the extra balance sheet commitments.
The most relevant update alongside the bond deal is the third quarter 2026 earnings print. CBRE Group reported quarterly sales of US$11,517m with net income of US$443m and basic EPS from continuing operations of US$1.53. For the first nine months of 2026, sales were US$33,270m and net income reached US$965m, with basic EPS of US$3.31. Those figures give you a live read on the earnings base that will now sit behind the new debt.
That profit profile matters for how you judge the catalyst from CBRE Group’s infrastructure and data center expansion. Management has highlighted a growing infrastructure services platform and a shift toward more recurring facilities, property and investment management fees, while advisory activity has seen improving leasing and sales volumes. The bond issuance and the Onnec Group Limited deal plug directly into that pattern, so the real test is whether future quarters keep translating M&A and project pipelines into fee revenue that comfortably services the higher fixed obligations.
CBRE Group Analyst Assumptions and Valuation Bridge
Analysts sketch a fairly specific path for CBRE Group. The consensus view points to revenue growing by 11.0% each year over the next three years, with profit margins rising from 3.0% today to 4.8% by 2029. On that timetable, earnings are projected to move from US$1.3b currently to US$2.8b in 2029, which is an increase of about US$1.5b. That same set of forecasts also anchors a revenue target of US$59.8b and requires the stock to trade on a P/E of 21.5x those 2029 earnings, compared with a multiple of 30.0x today and 14.2x for the broader US real estate peer group.
CBRE Group's narrative projects US$59.8b revenue and US$2.8b earnings by 2029. This assumes 11.0% yearly revenue growth and an earnings increase of about US$1.5b from US$1.3b today.
Those numbers feed directly into the current analyst price targets. The consensus target sits at US$176.67 per share, framed by a bullish end at US$200.00 and a cautious view at US$144.00, against a spot price of US$134.65. For that range to make sense, the market would need to accept that the forecast US$59.8b in 2029 revenue and US$2.8b of earnings can be achieved with a lower P/E multiple than today but still at a premium to many industry peers. That is a useful reference point rather than a conclusion, giving you a starting set of assumptions to stress test against your own view of CBRE Group's execution in infrastructure, data centers and broader real estate services.
Uncover why CBRE Group's fair value indicates a 43% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
You can also look at a far more optimistic angle around CBRE Group’s new debt. The most bullish analysts were already penciling in revenue of about US$65.8b and earnings near US$3.9b by 2029, before this bond deal. That view leans on M&A and infrastructure scale, and it may shift again once this financing filters into fresh forecasts.
Explore 2 other CBRE Group fair value estimates, including one that suggests as much as 62% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your CBRE Group research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for CBRE Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CBRE Group's overall financial health at a glance.
Looking for more investment ideas beyond CBRE Group?
If CBRE Group's debt funded expansion has you thinking about portfolio balance, it can help to line it up against other opportunities with different risk and return profiles.
- If you want potential upside but care about balance sheet resilience, start with a list of solid balance sheet and fundamentals (24 results) to see which businesses pair financial strength with earnings support.
- For investors hunting for value with quality filters already built in, scan a curated 26 high quality undervalued stocks that combines robust cash flows with what our model views as attractive pricing.
- When capital preservation is front of mind, focus on stability first by reviewing a 32 resilient stocks with low risk scores and compare those profiles with CBRE Group in your own watchlist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com