


HEICO (HEI) is back on growth investors’ radar after Zacks highlighted the company as a solid growth pick, citing an expected 28.3% EPS increase this year and recent upward earnings estimate revisions.
Recent trading suggests momentum for HEICO is rebuilding, with a 7 day share price return of 4.19% and a 30 day gain of 2.04% after a 12.24% decline over 90 days. The 3 year total shareholder return of 96.90% and 5 year total shareholder return of 124.52% underline how long term holders have been rewarded, despite a softer year to date share price move of 5.61% and a flat 1 year total shareholder return of 0.13%, at a latest share price of US$310.82.
Scan beyond HEICO and spot other growth-driven industrials gaining traction with our hand picked 19 high quality undiscovered gems.
HEICO trades at US$310.82 against a consensus target of US$390.70 and only a modest intrinsic discount, after a mixed stretch for the share price. Where does fair value truly land within that spread?
Most Popular Narrative: 21% Undervalued
On Simply Wall St’s most followed narrative, HEICO’s fair value estimate of $393.70 sits meaningfully above the last close at $310.82. This puts the focus squarely on how the business is expected to compound earnings under that view.
Expanded funding capacity of up to about US$3b from new senior notes and the larger revolving credit facility, combined with a disciplined focus on targets with at least 20% EBITDA margins and rapid accretion, positions HEICO to add further high margin earnings streams and support its net income growth ambitions.
See why 26 investors see HEICO as 21% undervalued.
Result: Fair Value of $393.70 (UNDERVALUED)
Still, if supply chain headaches linger or acquisitions fall short of HEICO’s 20% EBITDA and rapid accretion hurdles, that positive undervaluation narrative could fade quickly.
Find out about the key risks to this HEICO narrative.
Another View On HEICO’s Valuation
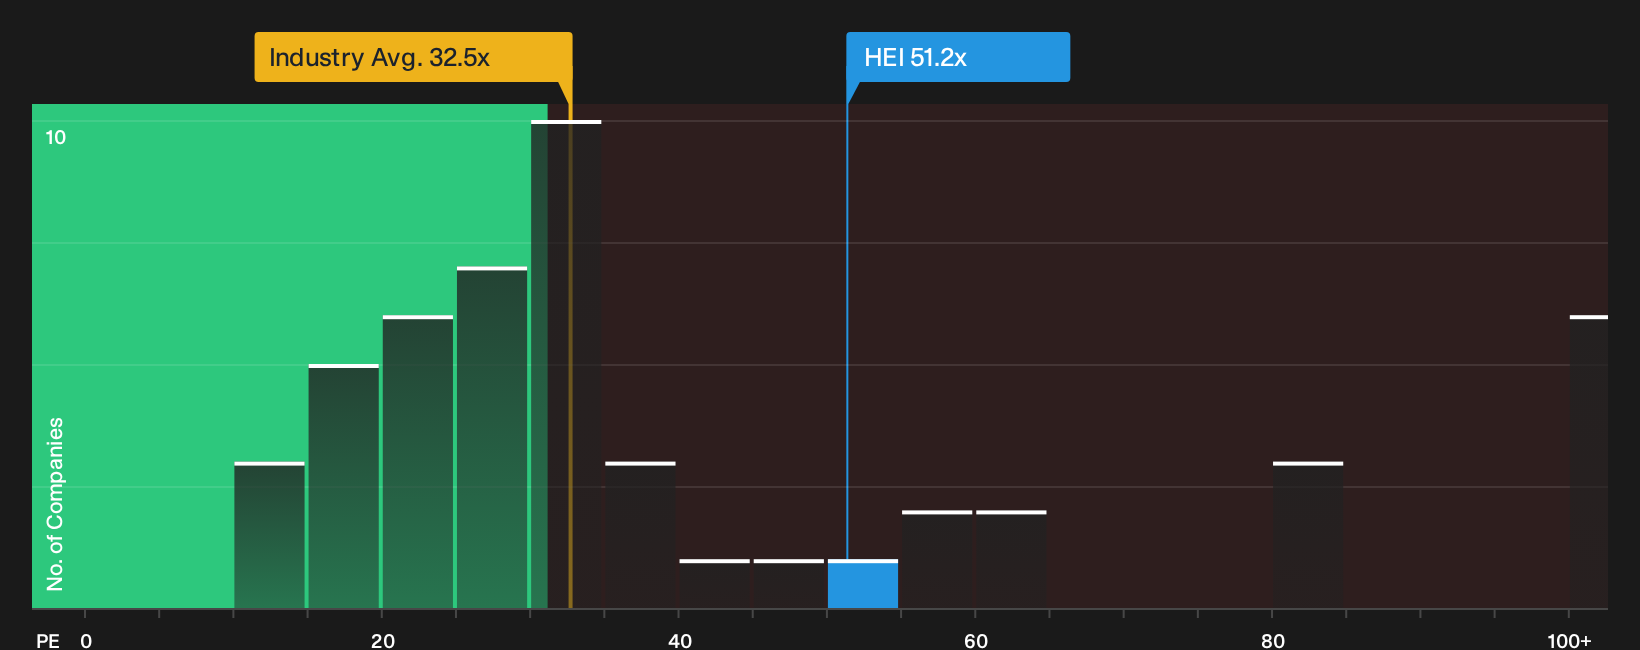
The growth narrative presents HEICO as about 21% undervalued at a fair value of $393.70, yet the P/E ratio of 51.2x tells a tougher story. That multiple is markedly higher than the US Aerospace & Defense average of 32.5x and also well above a fair ratio of 27.3x derived from broader market data.
Such a gap can mean investors are paying a premium today for earnings quality and consistency that might already be reflected in the price. This raises the risk that any slip in expectations affects the multiple rather than the profit line. The key question is whether you expect that spread to close through stronger fundamentals or through a lower valuation multiple.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on HEICO’s valuation and growth story can pull you in both directions, so move quickly and review the full picture for yourself. To weigh both the upside potential and the key concerns in one place, start with the 4 key rewards and 1 important warning sign
Want more ideas beyond HEICO?
If HEICO has your attention, do not stop here. Use Simply Wall St’s screeners to uncover other stocks that fit the kind of portfolio you want.
- Target resilient businesses that prioritise balance sheet strength and cash generation through a focused list of solid balance sheet and fundamentals (24 results).
- Hunt for potential mispricings by scanning a 26 high quality undervalued stocks that filters for quality alongside attractive valuations.
- Secure your income stream by reviewing a hand picked 6 dividend fortresses designed for investors who want yield with supporting fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com