


- OHB SE reported the successful completion of the EU funded Eu-BEST project, commissioning a full scale, modular engine and stage test bench at OHB Digital Connect’s Mainz site after receiving €4.96 million under the Horizon Europe program.
- The Eu-BEST test bench, developed with partners across France, Spain, Ireland and reviewed by ESA, CNES, DLR and the European Commission, gives OHB a flexible platform for launcher ground testing that could support future engine, stage and infrastructure contracts.
- We will now look at how OHB’s new ESA OASIS lunar infrastructure study could reshape the broader investment narrative for the group.
OHB Investment Narrative Recap
To own OHB, you need to be comfortable with a project heavy space contractor that is leaning into capacity expansion while still running at relatively thin net margins of 3.4% on €1,278.7 million of revenue. The short term focus sits on execution quality and cash conversion as large European programs ramp, rather than on headline contract wins alone.
The biggest operational risk remains underutilized facilities and rising fixed costs if awards such as Ariane 6 related work or EPS Sterna timing slip, especially after recent investment in Sweden and Saxony. The Eu BEST news appears helpful for credibility but does not fundamentally change that near term risk reward balance.
The ESA OASIS lunar infrastructure study contract ties most directly into the Eu BEST story. Both point to OHB building deeper capability along the access to space and exploration value chain, from launch infrastructure through to future lunar systems. This matters for understanding how today’s projects could feed into tomorrow’s backlog.
For catalysts, investors watching OHB can treat OASIS as another data point suggesting that its role in long duration European programs is broadening alongside Ariane 6 components and defense related missions. The key question is whether this pool of multi year work helps the business sustain a shift from cash burn to positive free cash flow.
OHB's current analyst narrative points to revenues of €2.5b and earnings of €178.1 million by 2029, built on forecast annual top line growth of 25.5% and an earnings step up of about €122 million from €56.1 million today.
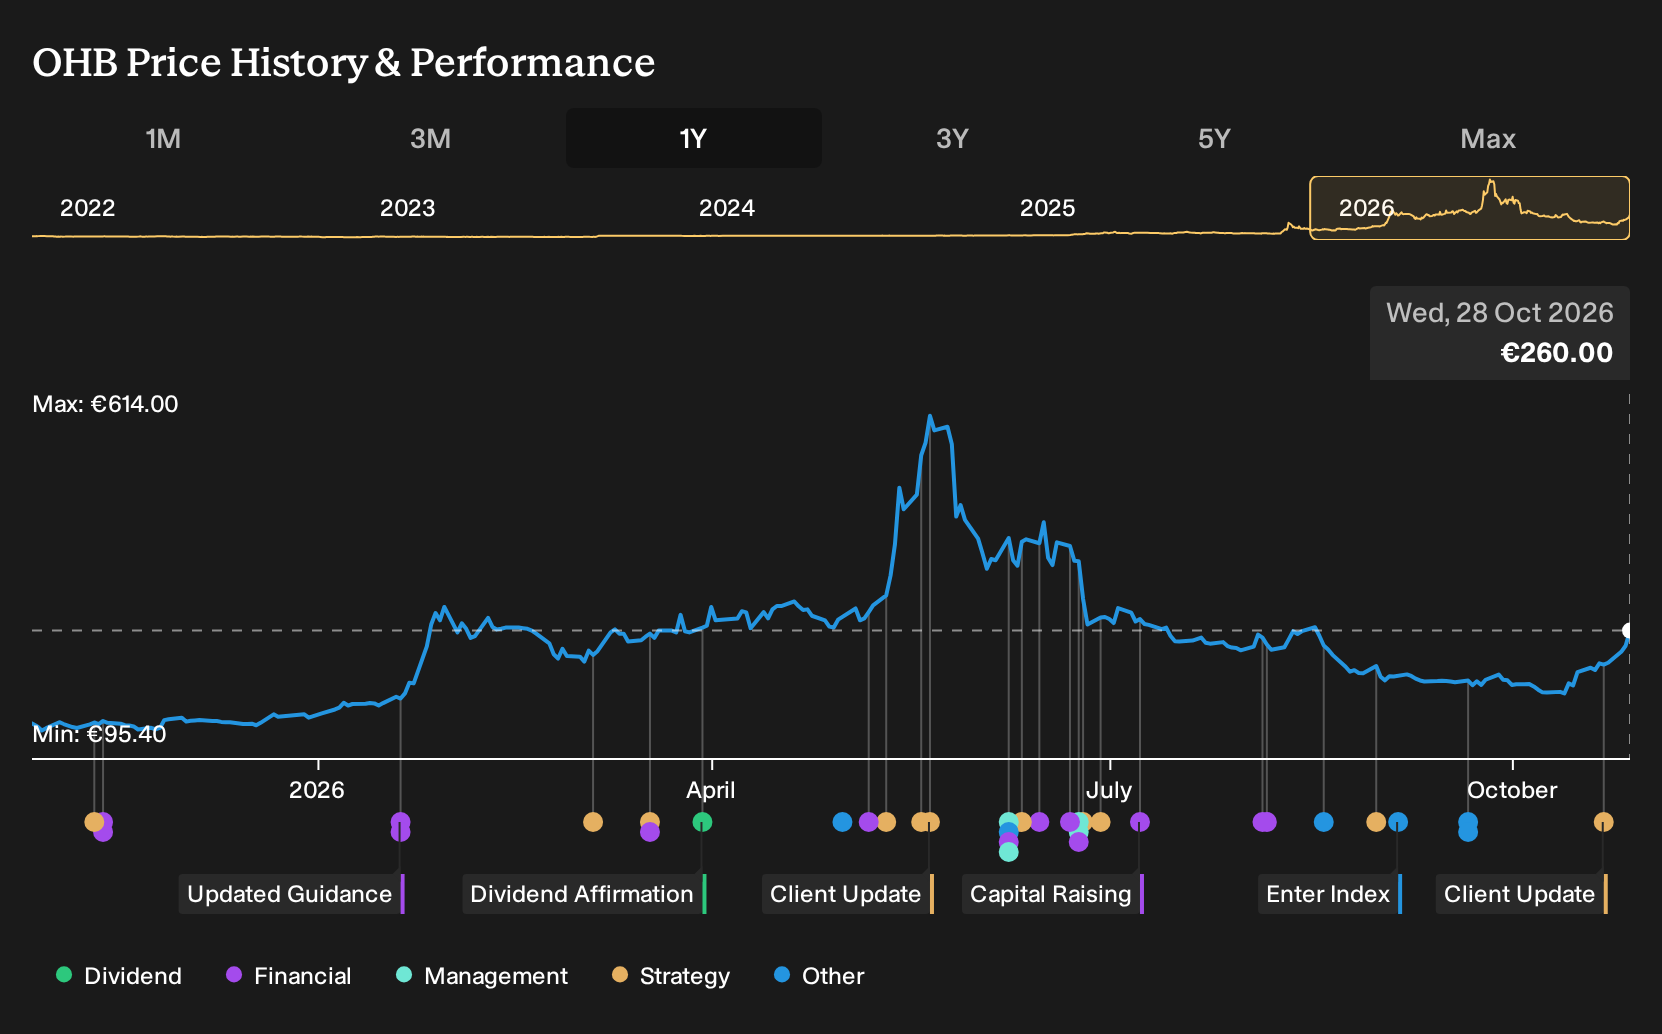
Uncover why OHB's fair value indicates an 18% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
One alternate angle on OHB focuses on earnings quality rather than contract headlines. The most cautious analysts were only pencilling in about €2.5b of revenue and €157.9 million of earnings by 2029 before this Eu BEST news, which implies weaker margins. That gap in expectations shows how widely views can differ, so it may be useful to explore several scenarios before deciding how this story might evolve.
Explore 2 other OHB fair value estimates, including one that suggests it could be worth just €267.66.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your OHB research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for OHB. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate OHB's overall financial health at a glance.
Looking For More Ideas Beyond OHB?
If you want to stress test your thesis on OHB and broaden your watchlist, it can help to line it up against other businesses with very different risk and income profiles.
- For investors who care most about resilience and capital protection, scan through a curated set of 228 resilient stocks with low risk scores that score well on stability metrics.
- If balance sheet strength is your priority, compare OHB with a list of solid balance sheet and fundamentals (203 results) and see how its financial footing stacks up.
- Or, if you are hunting for less crowded ideas with room for the story to mature, look across a 609 high quality undiscovered gems and see which ones deserve a spot on your radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com