


Wärtsilä Oyj Abp (HLSE:WRT1V) just released third quarter and nine month 2026 figures, reporting higher sales but lower quarterly net income compared with last year, which has put the latest earnings call in sharper investor focus.
Wärtsilä Oyj Abp’s share price has slipped over recent months, with a 30-day share price return of 6.06% down and a year to date share price return of 14.29% down, even though the three year total shareholder return of 160.40% still points to strong longer term momentum.
Scan how Wärtsilä Oyj Abp compares with other industrials reacting to fresh earnings and shifting sentiment by reviewing our hand picked list of solid balance sheet and fundamentals (203 results) in the same space.
The mixed share price pullback against Wärtsilä Oyj Abp’s strong multi year run sets up a simple tension. Is most of the easy money already behind the stock, or does current pricing still leave clear upside on the table?
Most Popular Narrative: 19% Undervalued
On the most followed view, Wärtsilä Oyj Abp screens as undervalued, with a narrative fair value of €33.04 against the last close at €26.64. This puts the spotlight on what is driving that gap.
Expanded engine manufacturing capacity in Vaasa, which is running at 100% of technical capacity in 2026 with order slots sold out for 2028 and largely committed for 2029, supports a long queue of deliveries that can feed Wärtsilä Oyj Abp revenue and earnings as projects are executed and invoiced.
Higher margin energy order backlog, with newbuild energy orders carrying margins about 500 basis points above 2025-vintage backlog, provides potential for an earnings mix that is more supportive of net margin compared with earlier project cohorts.
See why 21 investors see Wärtsilä Oyj Abp as 19% undervalued.
Result: Fair Value of €33.04 (UNDERVALUED)
Still, the Wärtsilä Oyj Abp story can break if marine customers continue to delay spare part orders or if tight engine capacity keeps shutting the business out of new auctions.
Find out about the key risks to this Wärtsilä Oyj Abp narrative.
Another View: Wärtsilä Oyj Abp On Earnings Multiples
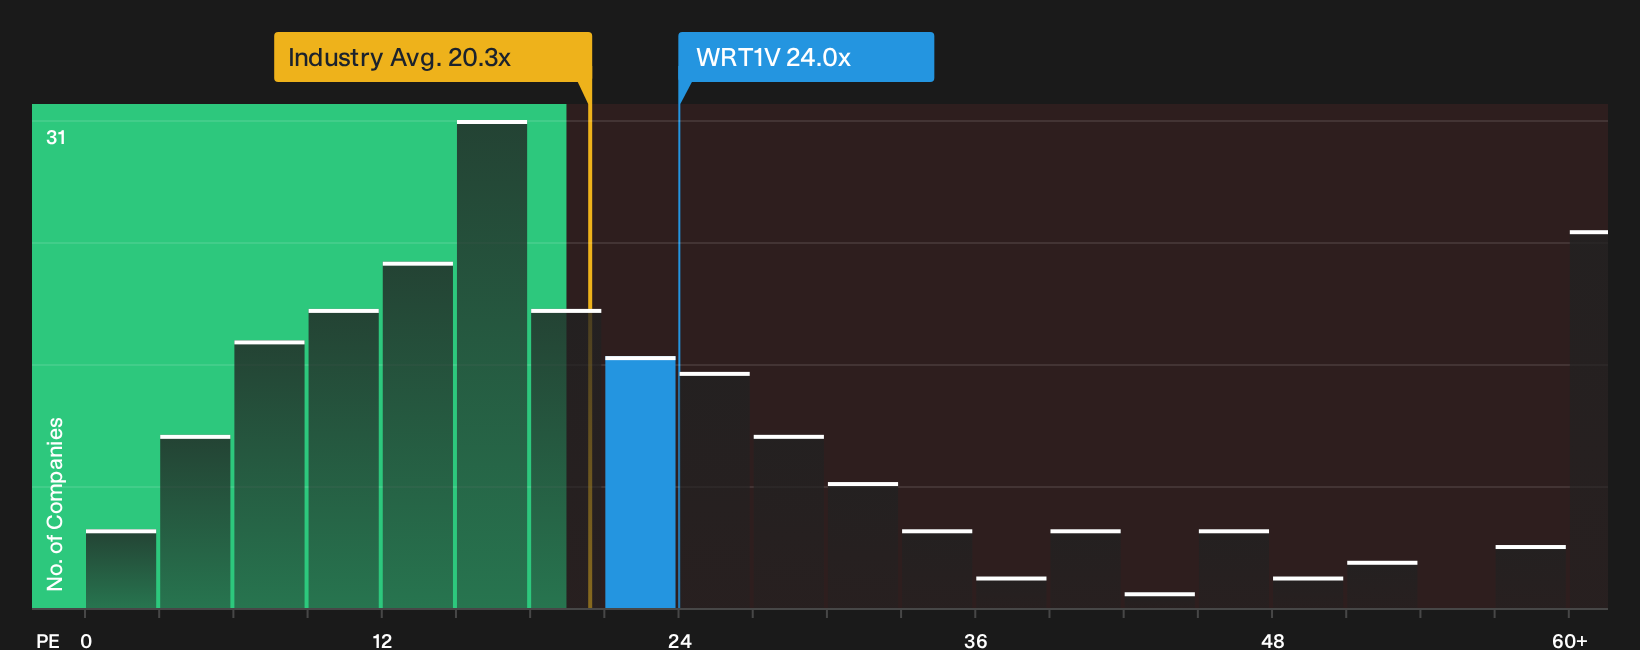
The earlier fair value story leaned on analyst forecasts and narrative modelling. On a simple P/E check, Wärtsilä Oyj Abp trades on about 24x earnings, while the European Machinery industry sits closer to 20.1x and peer averages around 19.1x. The fair ratio for the stock is estimated at 30.4x, which suggests the market is already paying a premium but still below where that ratio could move if sentiment shifts. Is that gap a valuation cushion or a sign that expectations are already loaded into the price?
To see how this earnings multiple picture fits with margins, growth and quality, take a look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If the Wärtsilä Oyj Abp story so far feels mixed, treat that as your cue to check the underlying data yourself and move quickly. To see what has investors feeling optimistic, take a closer look at the 3 key rewards.
Looking for more Wärtsilä Oyj Abp style investment ideas?
Do not stop with one interesting story. Broaden your watchlist using focused screeners that surface different kinds of opportunities other investors might overlook.
- Target potential mispricings by scanning companies that combine strong fundamentals with valuation support through the 191 high quality undervalued stocks.
- Collect income focused ideas by reviewing financially resilient businesses offering solid yields with the 226 dividend fortresses.
- Dial back portfolio risk by filtering for resilient businesses with lower risk scores using the 228 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com