


CenterPoint Energy earnings beat and guidance reset
CenterPoint Energy (CNP) just posted third quarter revenue of US$2.19b and net income of US$331m, topping analyst expectations and prompting higher earnings guidance plus a US$4b expansion of its long term capital plan.
CenterPoint Energy’s earnings beat and larger capital plan come at a time when momentum in the share price has recently picked up. The 30-day share price return is 13.57% and the year-to-date share price gain is 7.38%, contributing to a 1-year total shareholder return of 9.21% and a 5-year total shareholder return of 79.48%.
Scan other regulated utilities that follow similar demand and capital investment themes with the hand picked 44 power grid technology and infrastructure stocks now while CenterPoint Energy’s guidance reset is front of mind.
CenterPoint Energy has just run hard on upgraded guidance and a bigger capital plan, yet today’s valuation still needs to answer one thing. Has most of the upside already been captured, or is there meaningful room left?
Most Popular Narrative: 6% Undervalued
CenterPoint Energy closed at $41.59, compared to a widely followed narrative fair value of $44.41 that leans on long term capital spending and regulated growth to bridge the gap.
CenterPoint Energy expects to grow non-GAAP EPS at the mid to high end of a 7% to 9% range annually through 2028 and through 2035, which ties long dated earnings growth directly to its US$66.7b capital investment plan and large-load expansion and therefore to future revenue and earnings.
See why 5 investors see CenterPoint Energy as 6% undervalued.
Result: Fair Value of $44.41 (UNDERVALUED)
Still, the CenterPoint Energy story depends on investors staying comfortable with a premium P/E, and on elevated capex not leading to heavier dilution or pressure on margins.
Find out about the key risks to this CenterPoint Energy narrative.
Another View: CenterPoint Energy on richer earnings multiples
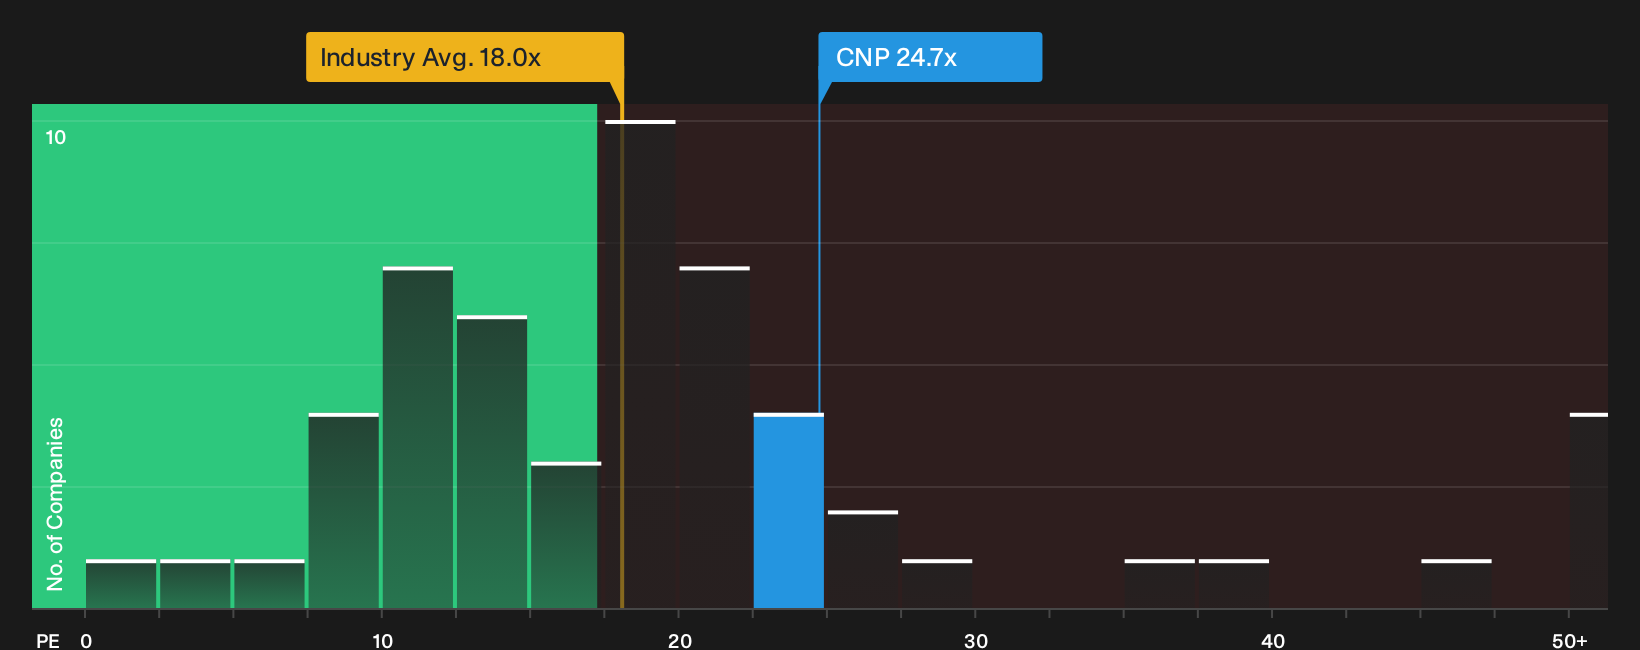
Look past the $44.41 fair value narrative and the story shifts. CenterPoint Energy trades on a P/E of 24.7x, compared with 17.9x for the global integrated utilities group and a fair ratio estimate of 20.9x. That richer multiple raises a simple question for investors: Is the premium comfort or crowding out future upside?
See what the numbers say about this price, find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and concern around CenterPoint Energy feels familiar, consider acting quickly and testing the numbers yourself before sentiment shifts. Start by weighing the 2 key rewards and 2 important warning signs
Looking for more CenterPoint Energy style investment ideas?
Do not stop with CenterPoint Energy. Use the Simply Wall St Screener to quickly surface fresh ideas before other investors start focusing on the same opportunities.
- Target resilient balance sheets and steady fundamentals by running a focused search with the list of solid balance sheet and fundamentals (24 results).
- Hunt for quality at a reasonable price as you scan our hand picked pool of 26 high quality undervalued stocks.
- Build a cash flow focused portfolio by zeroing in on the 6 dividend fortresses that can support meaningful income potential.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com