


Samsung’s record profits from AI memory chips highlight how quickly medical research is leaning on data hungry computing, which puts Australian biotech shares back in the spotlight. When drug discovery, diagnostics and personalised medicine depend more on algorithms, even early stage researchers that manage cash sensibly can gain attention. This article unpacks three Australian biotech stocks with solid balance sheets and grounded valuations from this focused screening list.
The three stocks below are only a sample from this screen. The full filter surfaced five more Australian biotech companies with similarly grounded stories that are not covered here.
To identify and analyze your own highest conviction ideas from this universe, head straight into the Biotech Stocks screener.
Vita Life Sciences (ASX:VLS)
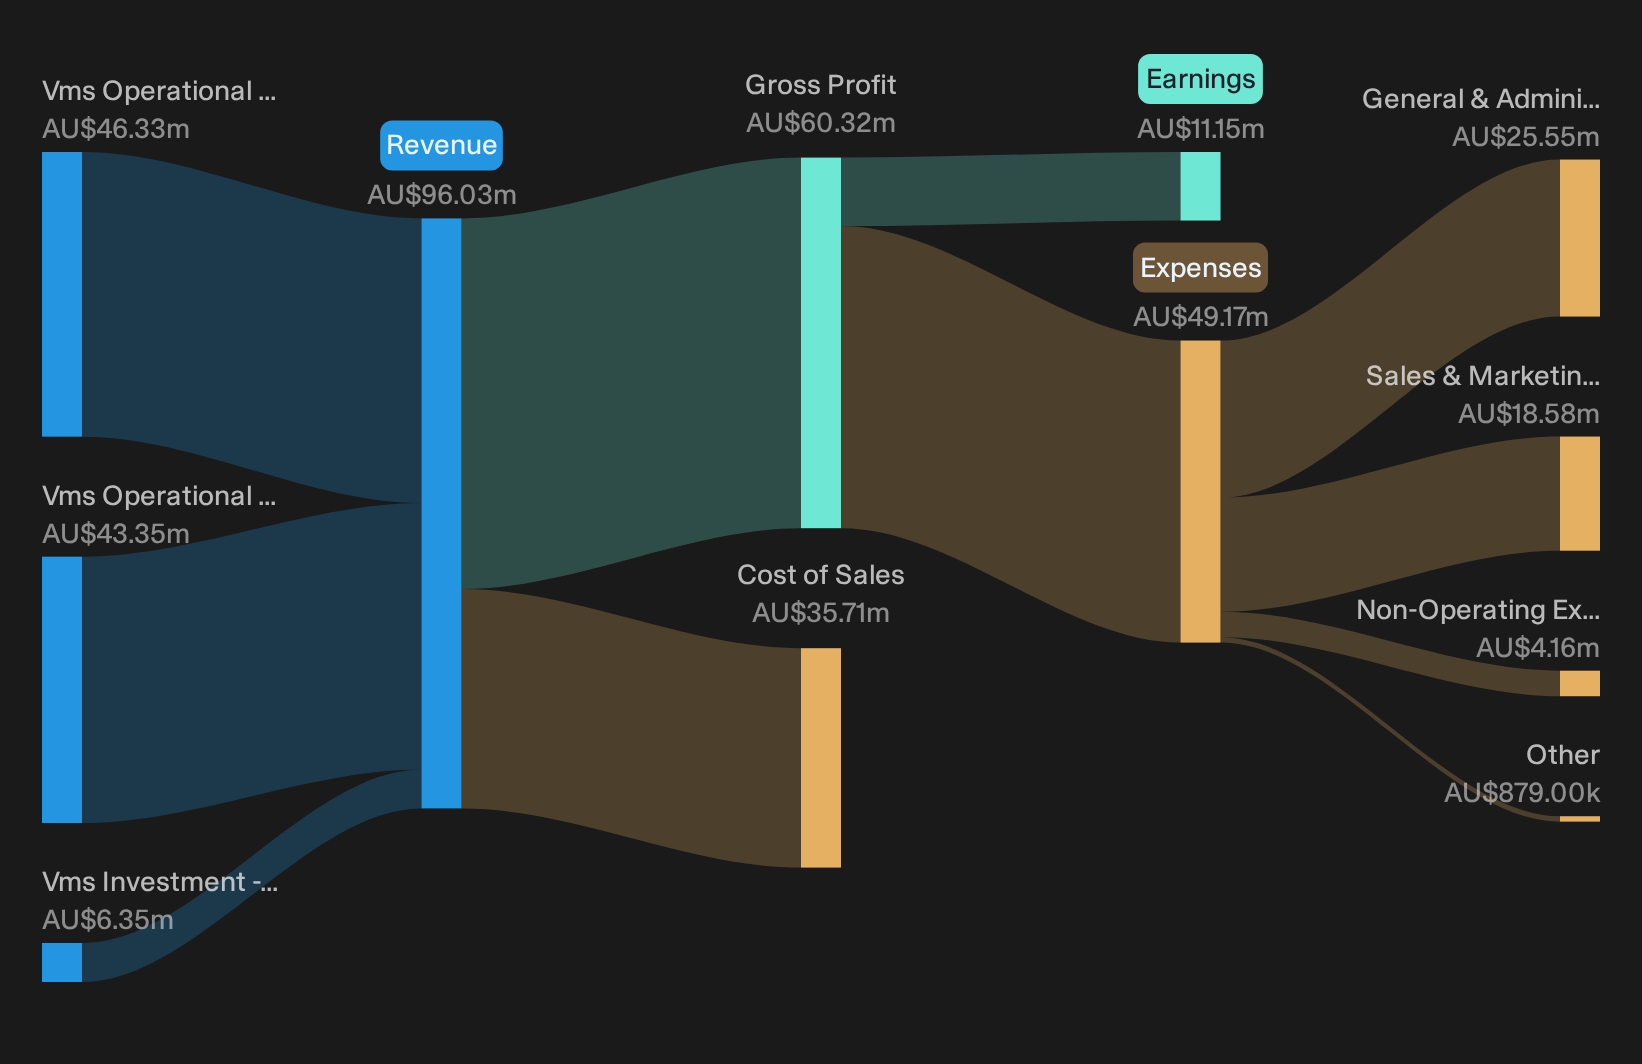
Overview: Vita Life Sciences formulates and sells biotech-linked vitamins, minerals, herbs, and superfoods under the Herbs of Gold, VitaHealth, and VitaScience brands.
Operations: Vita Life Sciences generates about A$43 million from Australian VMS operations, A$46 million from Malaysia and Singapore, and A$6 million from China and Vietnam.
Market Cap: A$149 million
Vita Life Sciences provides exposure to biotech-influenced nutraceuticals, with brands that turn nutritional science into cash flow and dividends. Earnings and margins are currently moving in a positive direction, supported by a 5% yield and a high 20% ROE in a sector where many peers are still working toward profitability. An important consideration is how the business might respond if any currently favorable earnings drivers begin to change.
If those earnings drivers start to shift, the 3 key rewards and 1 important warning sign shows what the headline numbers might be masking.
Clinuvel Pharmaceuticals (ASX:CUV)
Overview: Clinuvel Pharmaceuticals develops biotech therapies and photoprotective products built around SCENESSE and related melanocortin drugs for rare and severe skin disorders.
Operations: Clinuvel Pharmaceuticals records A$94 million in biopharmaceutical revenue, with A$53 million from Ireland, A$41 million from the United States, and under A$1 million elsewhere.
Market Cap: A$362 million
Clinuvel Pharmaceuticals fits this Biotech Stocks screener because its SCENESSE franchise already earns cash while a broader melanocortin pipeline aims to extend that rare disease and dermatology footprint.
"Progression of the Phase III vitiligo program through CUV105 top line data and the planned CUV107 study, together with ongoing engagement with EMA and FDA on endpoints and trial design, gives Clinuvel Pharmaceuticals a path to add a second indication that could broaden the SCENESSE revenue base beyond EPP and support longer term earnings."
The real swing factor is how one future decision around this expanding treatment portfolio reshapes Clinuvel Pharmaceuticals' mix of growth and profitability.
How that decision tilts the balance, and the full narrative for Clinuvel Pharmaceuticals shows how Clinuvel Pharmaceuticals could shift if pipeline risks and cash generation start decoupling.

Mayne Pharma Group (ASX:MYX)
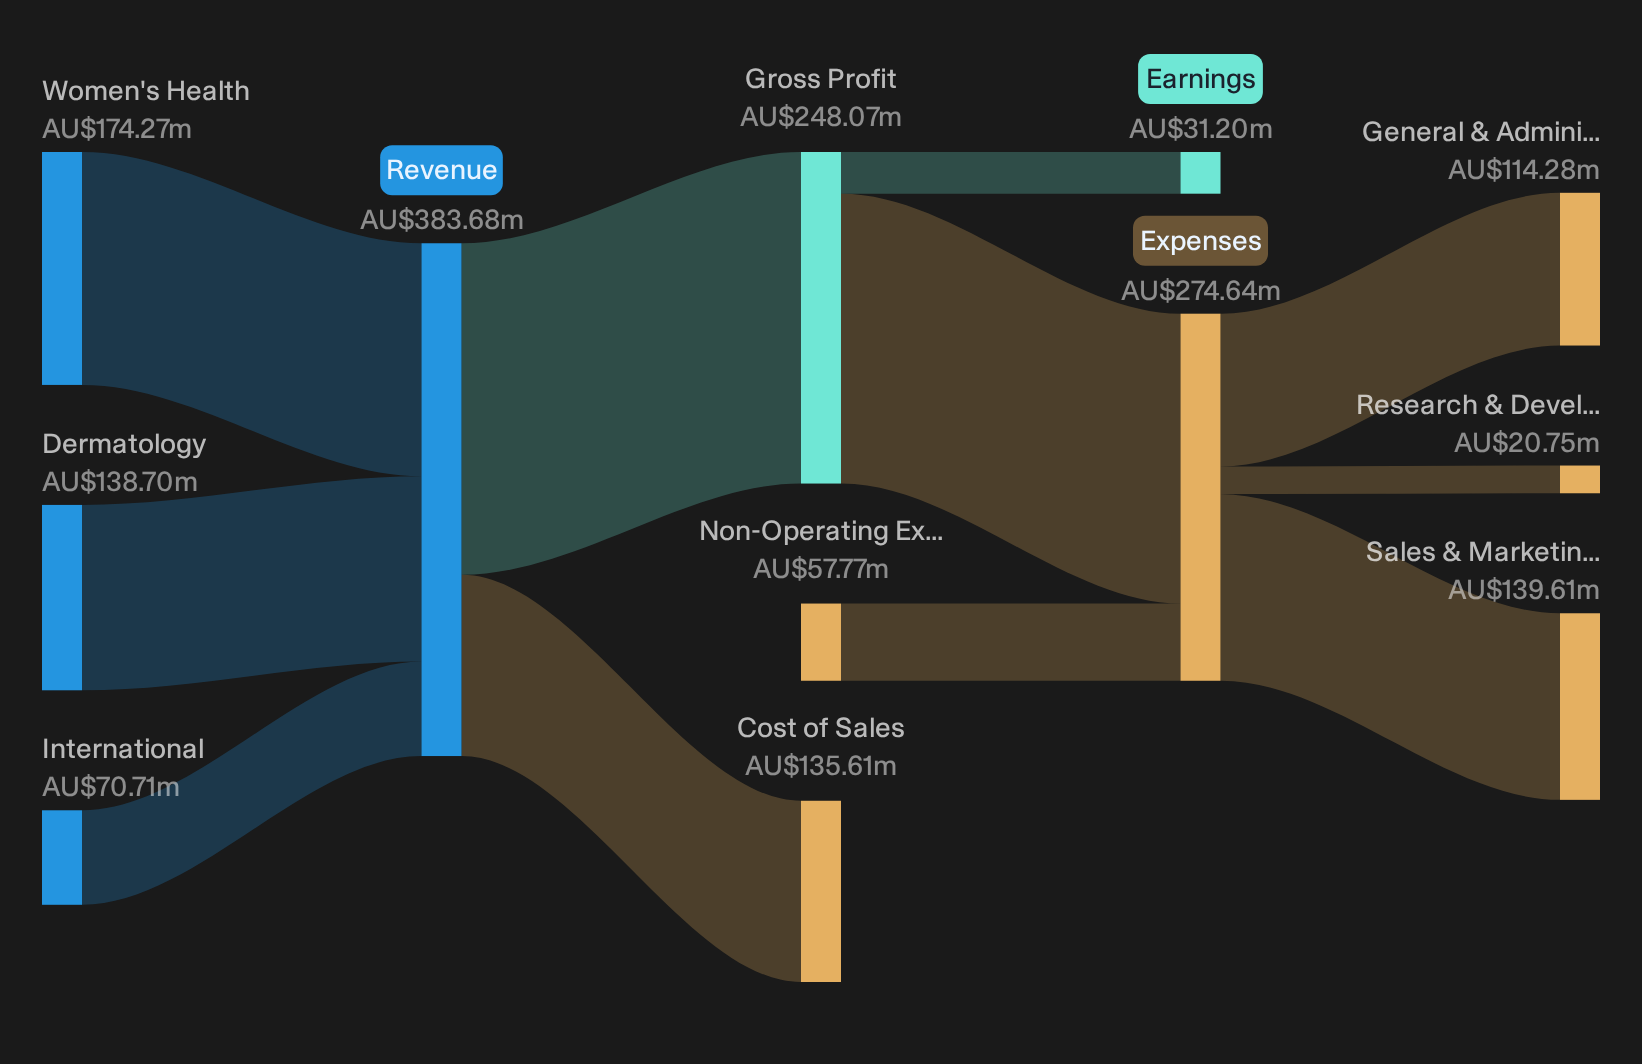
Overview: Mayne Pharma Group commercialises women’s health and dermatology drugs and offers oral drug delivery and CDMO services across global markets.
Operations: Mayne Pharma Group generates A$174 million from Women's Health, A$139 million from Dermatology and A$71 million from International, mostly in the United States.
Market Cap: A$215 million
For a biotech-focused investor, Mayne Pharma Group matters because it earns its keep by putting women’s health and dermatology therapies onto pharmacy shelves, then backing that with development and manufacturing know how that keeps it directly plugged into real drug pipelines.
"Removal of the U.S. government black box warning for certain hormone replacement therapy products, including BIJUVA and IMVEXXY, is encouraging more discussion between patients and prescribers, which can support wider adoption and potentially higher net revenue in the Women's Health segment."
What happens if one quiet shift in how those products reach patients meaningfully changes pricing power and the mix of high margin prescriptions?
If that shift is starting to build, the full narrative for Mayne Pharma Group examines whether Mayne Pharma Group’s pricing power, margins and upside or downside risk are accelerating or quietly stalling.
Seeking Alternatives Before The Crowd?
Fresh ideas can move quickly when momentum builds, and by the time everyone notices, the best entry points are often gone. Scan these under the radar lists and act now.
- Target reliable income streams by checking out 5 dividend fortresses that aim to keep portfolios paying while others chase stories without cash returns.
- Spot potential market leaders early and review 15 high quality undiscovered gems quietly building quality before bigger investors start bidding prices higher.
- Position ahead of the next upgrade cycle and track 44 power grid technology and infrastructure stocks preparing to modernise electricity networks while the opportunity is still under followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com