


The UK market has been under pressure, with the FTSE 100 and FTSE 250 indices experiencing declines amid concerns about China's economic recovery and its impact on global trade. In such uncertain times, growth companies with high insider ownership can be appealing as they often indicate a strong alignment between management and shareholders, potentially providing resilience in challenging market conditions.
Top 10 Growth Companies With High Insider Ownership In The United Kingdom
| Name | Insider Ownership | Earnings Growth |
| TPXimpact Holdings (AIM:TPX) | 19.5% | 106% |
| TEAM (AIM:TEAM) | 32% | 85.3% |
| Mortgage Advice Bureau (Holdings) (LSE:MAB1) | 18.5% | 22.4% |
| Hochschild Mining (LSE:HOC) | 38.3% | 21.6% |
| Gulf Keystone Petroleum (LSE:GKP) | 12.6% | 21.1% |
| Energean (LSE:ENOG) | 19.3% | 32.8% |
| EARNZ (AIM:EARN) | 10.1% | 104.2% |
| Crimson Tide (AIM:TIDE) | 33% | 119.1% |
| Built Cybernetics (AIM:BUC) | 22.6% | 122.1% |
| Beauty Tech Group (LSE:TBTG) | 19.5% | 23.8% |
Below we spotlight a couple of our favorites from our exclusive screener.
Kistos Holdings (AIM:KIST)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Kistos Holdings Plc is engaged in the development and production of gas and hydrocarbon reserves across the United Kingdom, Norway, and the Netherlands with a market cap of £251.02 million.
Operations: The company's revenue primarily comes from its oil and gas exploration and production segment, generating $336.93 million.
Insider Ownership: 20.8%
Kistos Holdings has demonstrated substantial growth, becoming profitable this year with sales reaching $211.9 million for the first half of 2026. The company completed a significant acquisition of Blocks 3 & 4, adding valuable reserves and generating $51 million EBITDA in the first half. Despite trading below fair value estimates, Kistos faces challenges with interest coverage but benefits from forecasted earnings growth at 12.9% annually, surpassing UK market expectations. Recent fixed-income offerings bolster financial flexibility.
- Dive into the specifics of Kistos Holdings here with our thorough growth forecast report.
- Our expertly prepared valuation report Kistos Holdings implies its share price may be lower than expected.
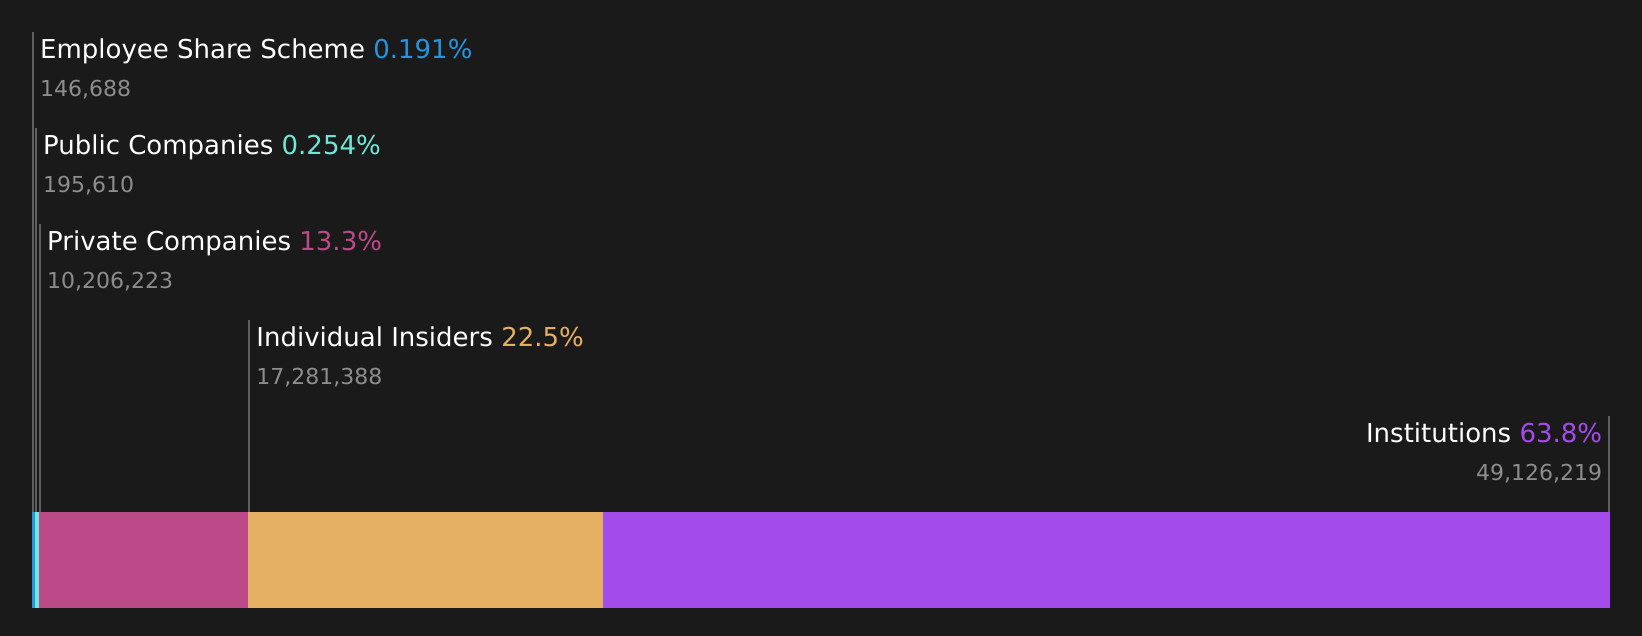
Next 15 Group (AIM:NFG)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Next 15 Group plc operates in the data, technology, and activation sectors across various regions including the UK, US, Europe, the Middle East, Africa, and Asia Pacific with a market cap of £329.35 million.
Operations: Next 15 Group plc generates revenue through its operations in the data, technology, and activation sectors across regions such as the UK, US, Europe, Middle East, Africa, and Asia Pacific.
Insider Ownership: 11.6%
Next 15 Group faces challenges with declining sales and a net loss of £3.44 million for the half year ended July 31, 2026. Despite trading significantly below fair value estimates, the company is expected to become profitable within three years, with earnings forecasted to grow substantially. However, revenue is projected to decline annually by 7.7%. The company's high debt levels and unsustainable dividend coverage pose additional risks despite analyst optimism about future stock price increases.
- Delve into the full analysis future growth report here for a deeper understanding of Next 15 Group.
- Upon reviewing our latest valuation report, Next 15 Group's share price might be too pessimistic.
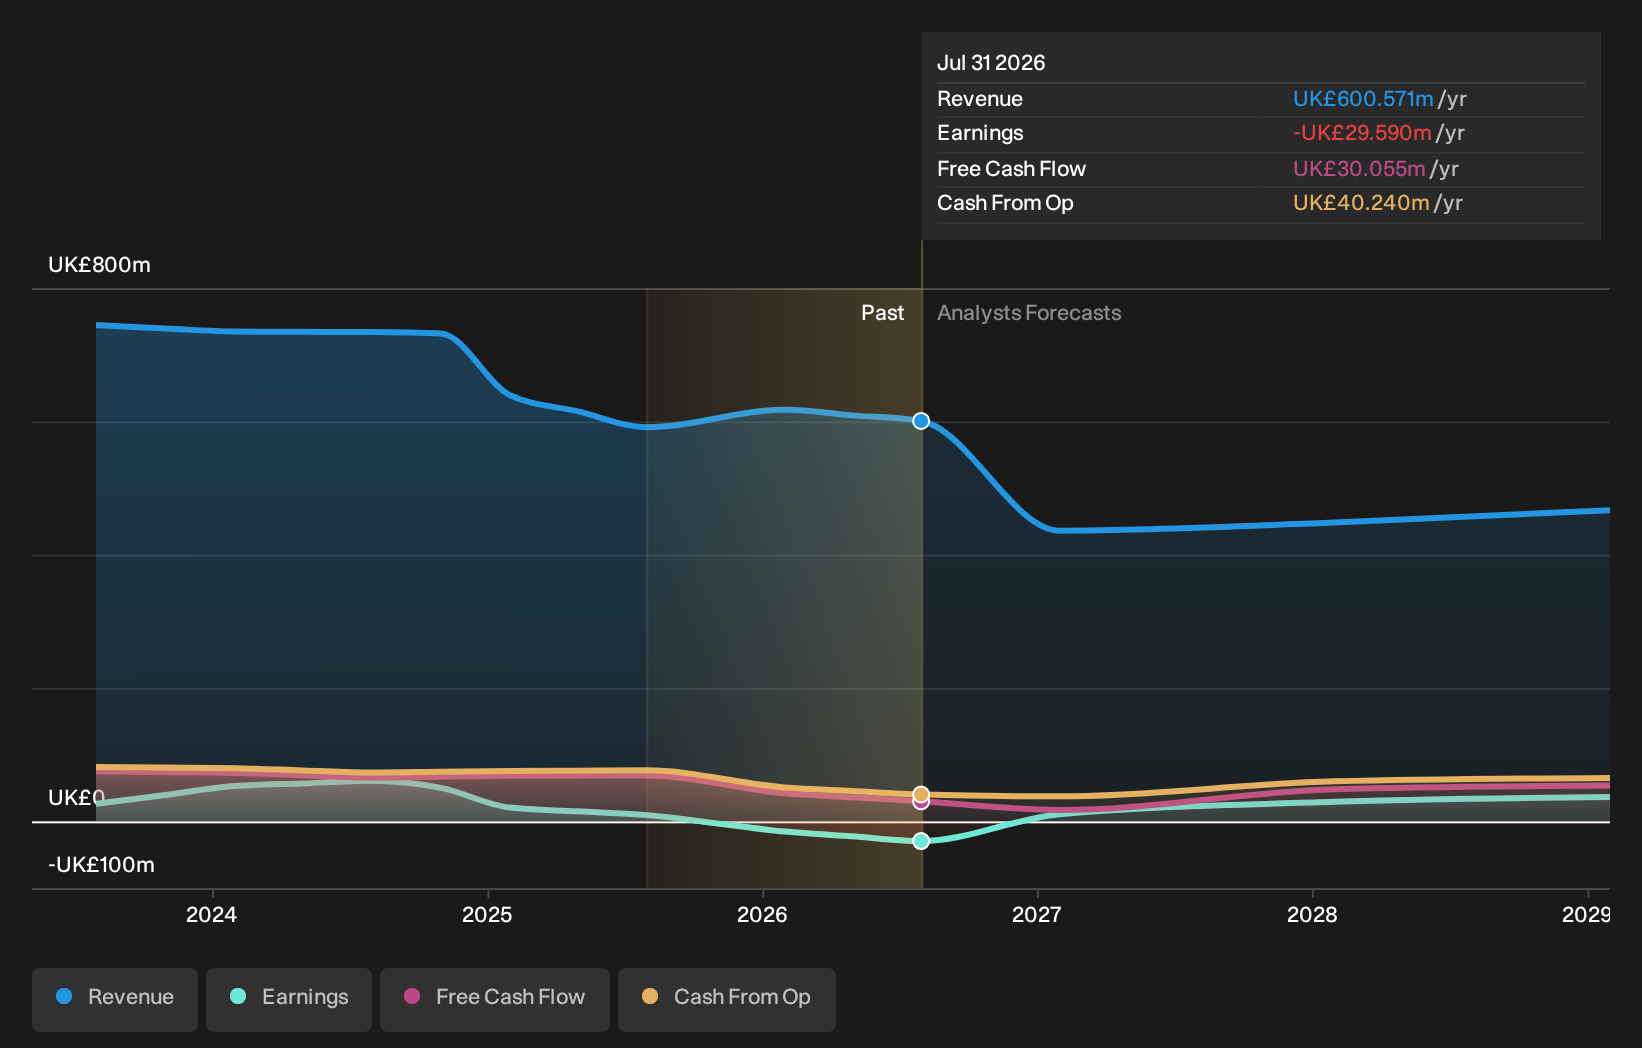
Foresight Group Holdings (LSE:FSG)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Foresight Group Holdings Limited is an infrastructure and private equity manager operating in the United Kingdom, Italy, Luxembourg, Ireland, Spain, and Australia with a market cap of £520.17 million.
Operations: The company generates revenue from Real Assets amounting to £114.81 million and Private Equity totaling £50.11 million.
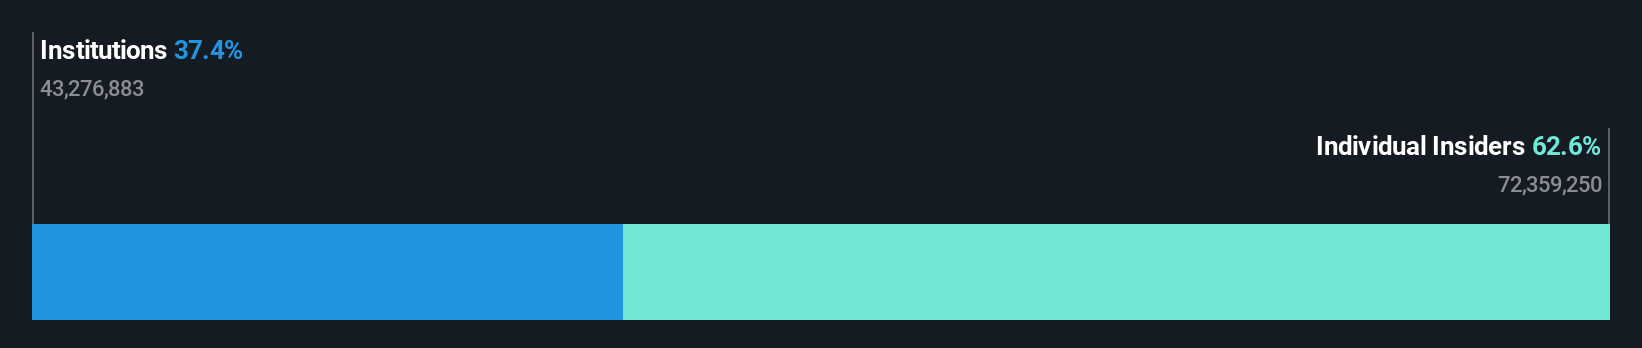
Insider Ownership: 35.7%
Foresight Group Holdings exhibits promising growth potential, with earnings forecasted to grow at 16.2% annually, outpacing the UK market average. Despite a slower revenue growth projection of 10.4% per year, its Return on Equity is expected to reach a very high level in three years. The stock trades at substantial value compared to peers and industry standards and is priced significantly below fair value estimates, suggesting potential upside as analysts anticipate a 47.1% price increase.
- Click here to discover the nuances of Foresight Group Holdings with our detailed analytical future growth report.
- Our valuation report unveils the possibility Foresight Group Holdings' shares may be trading at a discount.
Make It Happen
- Click here to access our complete index of 65 Fast Growing UK Companies With High Insider Ownership.
- Looking For Alternative Opportunities? Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com