


Lemonade (LMND) just widened its renters insurance footprint again, rolling out its low cost, app based policies to Idaho after a recent launch in Alabama.
Lemonade’s latest state launches come against a mixed price backdrop, with the share price down about 40% year to date and roughly 7% lower over the past three months, yet supported by a very large 3 year total shareholder return above 300%, which suggests that earlier momentum is now cooling.
Scan for other insurers pursuing similar rollout plays and stronger financial profiles using our curated list of list of solid balance sheet and fundamentals (24 results).
Bulls see Lemonade’s low cost, app heavy rollout as the backbone of a scalable insurance platform, while bears focus on ongoing losses and a falling share price. Which story does the current valuation lean toward?
Most Popular Narrative: 7% Undervalued
Lemonade’s most followed valuation storyline pegs fair value at $48.95, a little above the last close at $45.36. This puts the current pullback in a tighter context for anyone weighing the recent rollout news against longer term expectations.
Ignore the 79%. In-force premium, the measure of how much insurance Lemonade actually has on the books, grew 32.4% to $1.43 billion. Revenue grew 79% because ceded premiums fell roughly 49% as the company retained a larger share of its own risk. The company says as much in its letter.
See why 4 investors see Lemonade as 7% undervalued.
Result: Fair Value of $48.95 (UNDERVALUED)
Still, the Lemonade narrative leans on assumptions about loss ratios and risk retention. These assumptions could crack quickly if catastrophe claims or growth targets disappoint.
Find out about the key risks to this Lemonade narrative.
Another View: Lemonade Looks Expensive On Sales
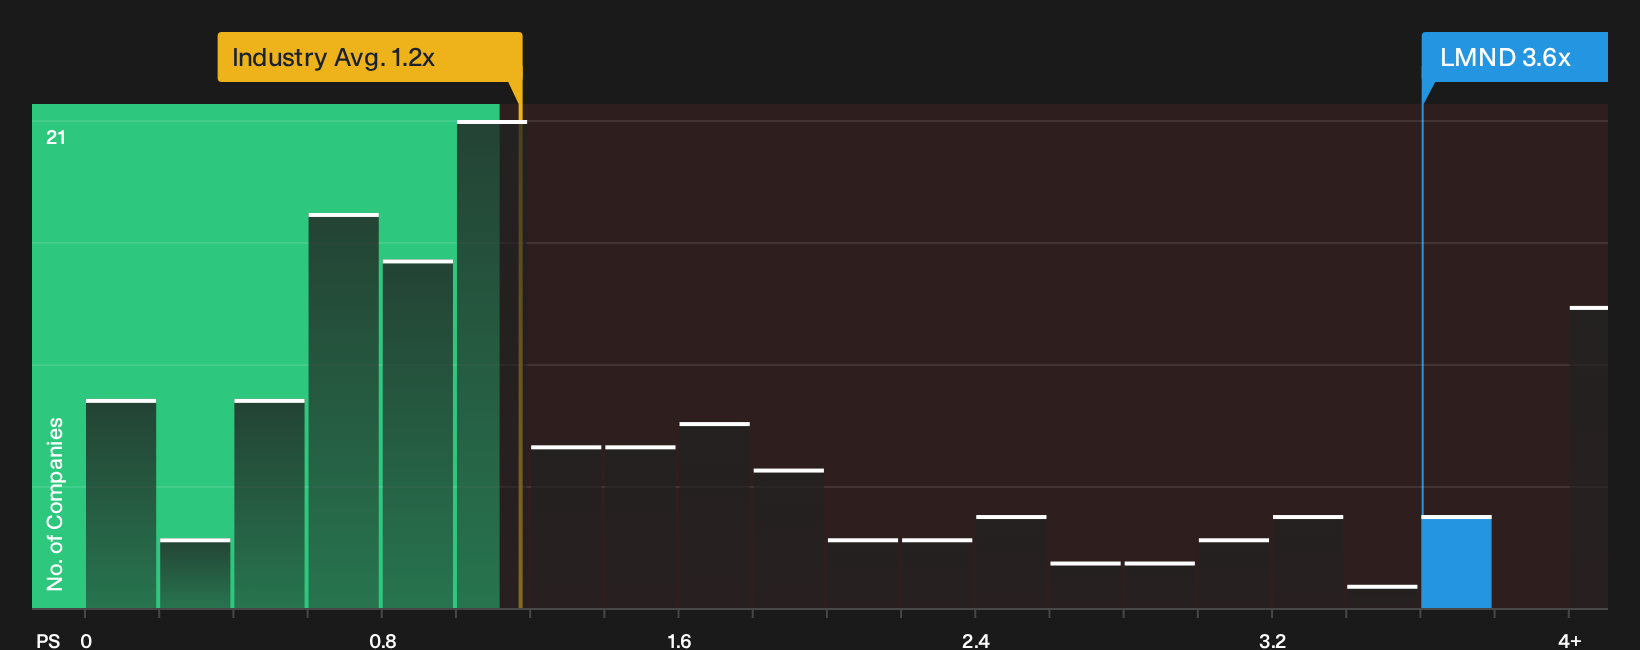
Lemonade’s most followed story points to a fair value of $48.95, yet its P/S of 3.6x tells a tougher story. That ratio is more than double the estimated fair ratio of 1.6x and well above the US insurance group on 1.2x and peers around 2.1x, which raises the risk that expectations, not current fundamentals, are doing the heavy lifting. If the market leans back toward those lower P/S anchors, how comfortable are you with what you are paying for each dollar of revenue today?
For a closer look at how these sales based metrics line up against the rest of the sector, and where the fair ratio might pull the price over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
The story around Lemonade is clearly split, with strong past returns sitting next to concerns on losses and valuation pressure. Act quickly and look through both sides of the data so you can decide where you land on 2 key rewards and 1 important warning sign
Looking for more ideas beyond Lemonade?
You have seen how divided the story around Lemonade looks. Now widen the lens and give yourself more options before committing fresh capital.
- Target potential upside with companies that combine quality fundamentals and attractive pricing by reviewing our 26 high quality undervalued stocks.
- Strengthen your income stream by focusing on businesses with higher yields and resilient payouts through the 6 dividend fortresses.
- Prioritize capital protection by zeroing in on resilient companies with lower risk profiles using the 32 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com