


- NOV Inc. reported Q3 2026 revenue of US$2.23b and net income of US$90 million, with earnings per share of US$0.25 beating analyst expectations.
- The Energy Products and Services segment delivered margin improvements supported by higher manufacturing throughput and efficiency gains, while demand from the Middle East and Latin America provided key volume support despite logistics issues.
- We will now assess how NOV Inc.'s earnings beat and margin gains could influence the existing investment narrative around offshore growth.
NOV Investment Narrative Recap
To own NOV, you need to be comfortable with a long-cycle energy equipment story in which offshore projects, international unconventional work and digital services drive the heavy lifting over time. Q3 showed that better execution can support margins even when logistics and tariffs bite. Management’s guidance for Q4 2026 revenue to be roughly flat year over year suggests the latest beat does not materially change the near term top line picture.
The short term swing factor now is execution on the existing offshore and international backlog while keeping costs under control as tariffs and freight remain elevated. The biggest risk is that trade expenses and regional disruptions in areas like the Middle East or Latin America persist or widen, which could offset efficiency gains and keep net margins and free cash flow under pressure despite healthy activity indicators.
The clearest data point to focus on is NOV’s Q3 2026 earnings release, which framed the quarter’s US$2.23b in revenue, US$90 million in net income and US$0.25 in diluted EPS from continuing operations. Those figures, together with management commentary about stronger offshore equipment bookings in 2027 and 2028, tie directly into the thesis that long duration projects and multi year order books are the key drivers to watch.
For you as an investor, that update gives a cleaner read on both catalysts and risks. Margin progress, record Energy Equipment profitability and structural cost savings show where upside can come from if execution stays tight. At the same time, negative free cash flow, higher tariff expense and the guidance for flat Q4 revenue highlight why working capital discipline, trade costs and any fresh disruption in key international regions remain central to the NOV story over the next few quarters.
NOV's current narrative assumes annual revenue growth of 3.4%, with earnings today of US$95.0 million stepping up to a forecast consensus of US$538.9 million by 2029. This implies an earnings increase of about US$444 million and ties to analyst projections for US$9.6b in revenue in that same forecast year.
Uncover why NOV's fair value indicates a 15% potential upside to its current price that may not last much longer.
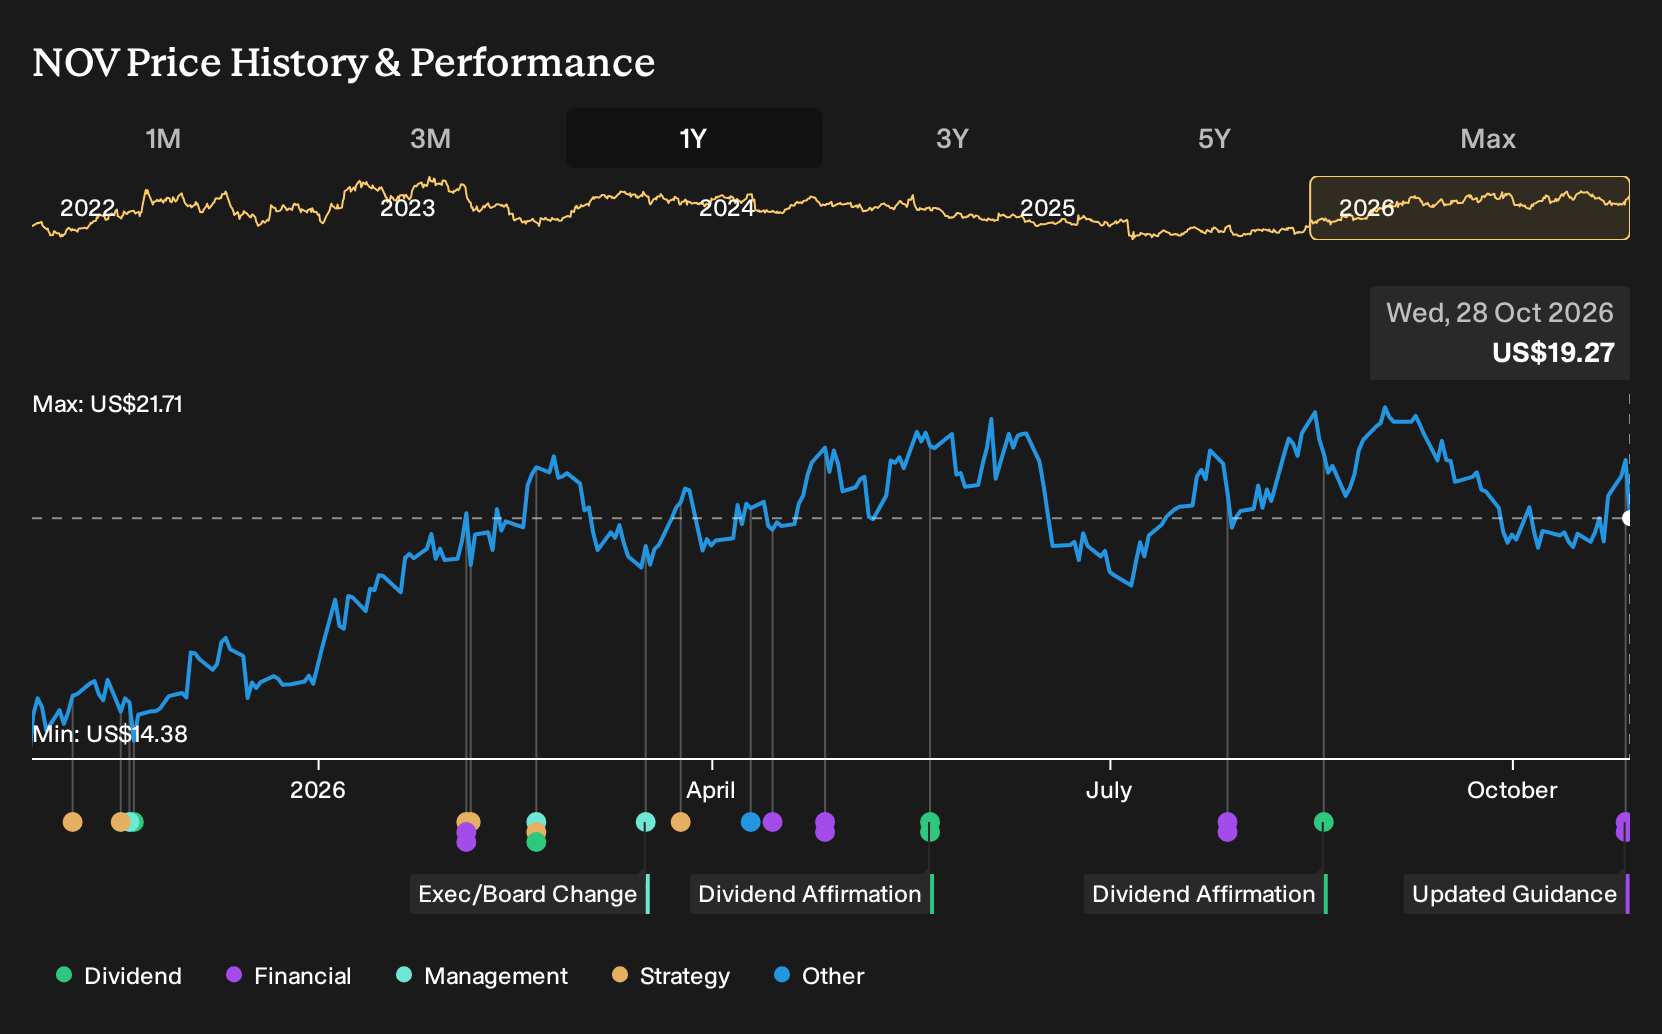
Exploring Other Perspectives
One alternate take focuses on free cash flow rather than offshore upside. The most cautious analysts were only penciling in about US$9.4b of 2029 revenue and roughly US$536.0 million of earnings before this quarter’s beat and flat Q4 guidance. That group sees NOV as fairly valued and recommends stress testing several different viewpoints.
Explore 2 other NOV fair value estimates, including one that suggests it could be worth just $22.08.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your NOV research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for NOV. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NOV's overall financial health at a glance.
Looking for more investment ideas beyond NOV?
If NOV's long-cycle profile appeals to you, it can help to line it up against other opportunities with different risk and income profiles using the Simply Wall St Screener.
- For investors who want potential value with quality fundamentals, scan a curated set of 19 high quality undiscovered gems that might not yet be widely followed.
- If capital preservation sits high on your list, compare NOV with 32 resilient stocks with low risk scores and see how it stacks up on resilience and downside protection.
- For those focused on balance sheet strength and business durability, review a list of solid balance sheet and fundamentals (24 results) that can complement a more cyclical holding like NOV.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com