


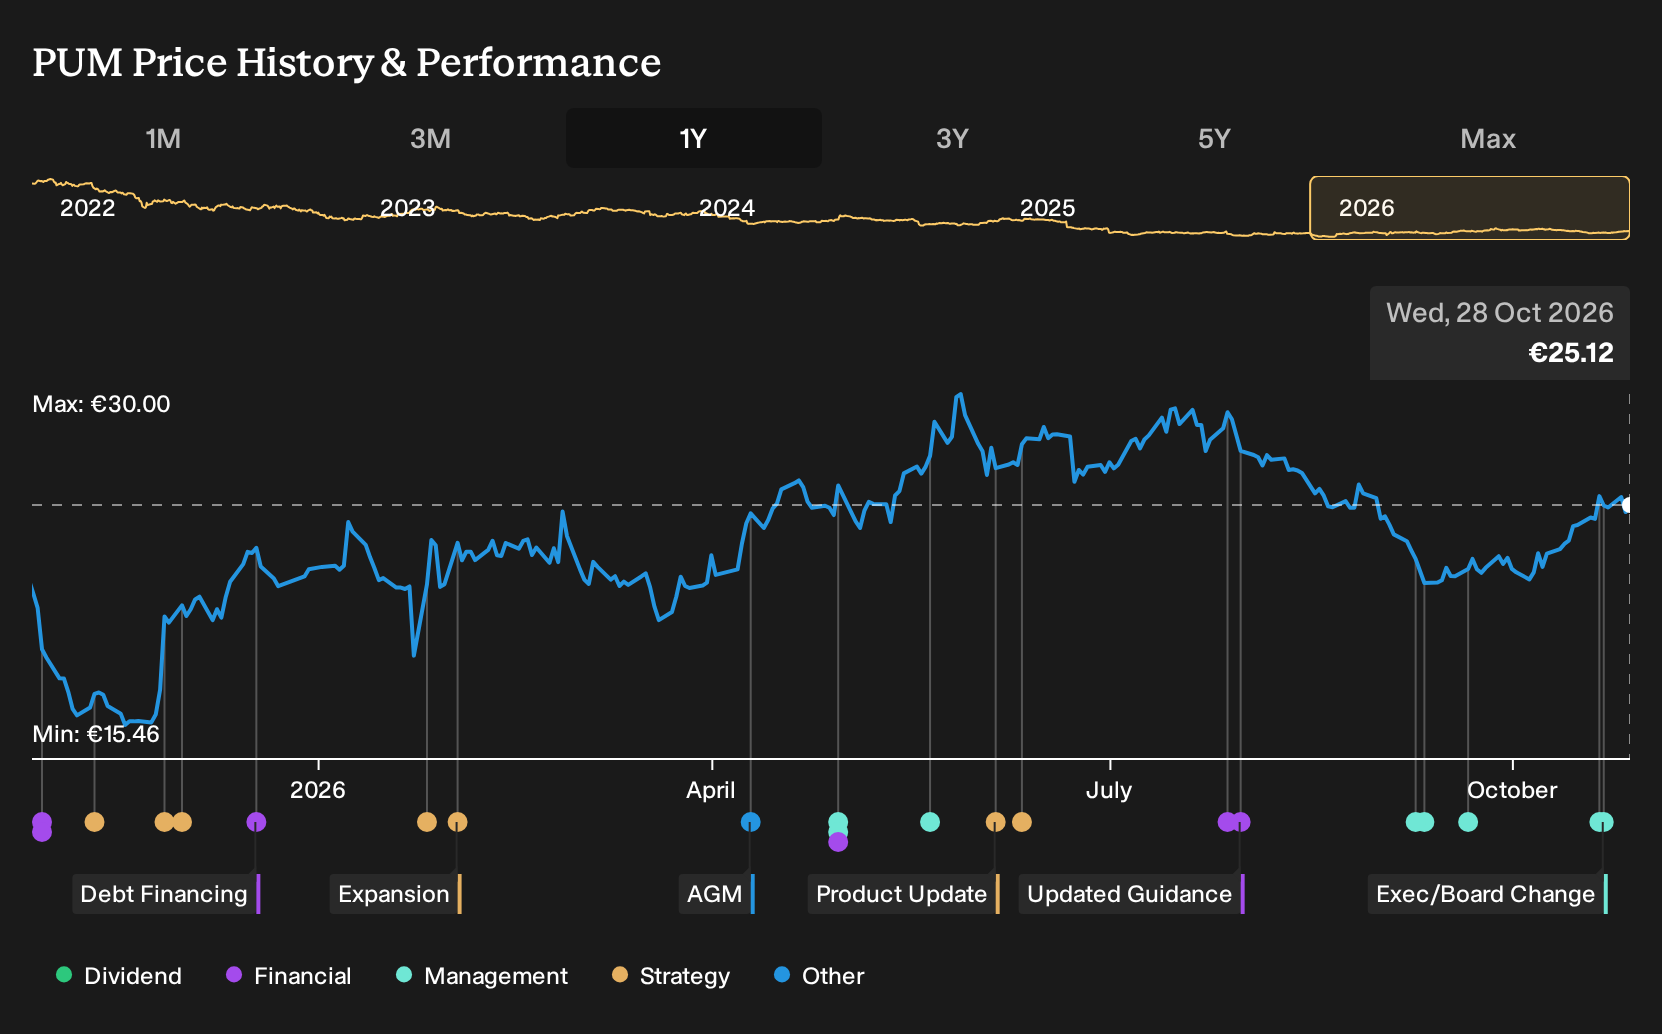
- PUMA announced significant leadership moves in October 2026, including appointing Arne Arens as Chief Commercial Officer and naming Dennis Tao as Supervisory Board Chairman after ANTA Sports acquired a large stake.
- The new leaders bring deep experience in performance sportswear, branding and capital markets, which could influence how PUMA balances commercial execution, governance and its ongoing business transformation.
- This article now examines how PUMA's refreshed Supervisory Board leadership could shape the investment narrative around its ongoing three year transformation.
Scan how PUMA’s leadership reshuffle compares with peers by reviewing hand-picked 609 high quality undiscovered gems that may be quietly rebuilding their management bench and brand momentum.
PUMA Investment Narrative Recap
PUMA appeals to shareholders who buy into a long, three year clean up and rebuild rather than a straight growth story. The key near term swing factor is whether the reset away from mass merchants, tighter wholesale segmentation and DTC push can stabilise sales after the recent constant currency declines and support better product mix without over relying on discounting.
The biggest current risk sits in execution. Inventories around €2.1b, working capital above €1.5b and net debt just over €1b leave less room if sell through in outlets or wholesale partners disappoints, or if ANTA’s 29% stake keeps Greater China partners cautious for longer than management planned.
The Supervisory Board shift to Dennis Tao and the appointment of Arne Arens as CCO matter most for how PUMA runs this transformation, rather than for any immediate financial effect. Tao’s capital markets and governance background, plus prior Amer Sports board experience, tie directly into oversight of working capital, debt and restructuring discipline.
Arens’ remit over global commercial operations and marketplace strategy links straight into the main catalyst, the move toward higher quality revenue via DTC and more selective wholesale. Investors will likely watch how wholesale partner behaviour, especially in Greater China and Europe, responds to the new leadership bench during 2027 as range reductions, HYROX and NITRO focused assortments roll through.
What The PUMA Consensus Numbers Assume
PUMA's narrative projects €8.0b revenue and €243.1m earnings by 2029. This implies 4.5% yearly revenue growth and an earnings swing of about €698m from earnings today of a €455.1m loss.
Uncover why PUMA's fair value indicates an 11% potential upside to its current price that could narrow faster than many investors expect.
Exploring Other Perspectives
Some of the most optimistic analysts pinned their thesis on a single catalyst. They expected PUMA’s cleaner 60% wholesale and 40% DTC mix to support around €8.7b in revenue and €358.1m in earnings by 2029. Those projections came before the Arens and Tao news, so you should expect views to shift and several alternatives to be explored.
Explore 3 other PUMA fair value estimates, including one that suggests as much as 57% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your PUMA research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for PUMA. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate PUMA's overall financial health at a glance.
Looking For More Investment Ideas Beyond PUMA?
If you want to pressure test your PUMA view against other opportunities, the Simply Wall St Screener can help you quickly sort listed businesses by quality, valuation and risk profile.
- For investors who want potential mispricings backed by fundamentals, scan a 191 high quality undervalued stocks that may align more closely with your return and risk expectations.
- If capital preservation is front of mind, focus on a 228 resilient stocks with low risk scores that screens for resilience rather than excitement.
- When balance sheet strength is non negotiable, filter companies using a list of solid balance sheet and fundamentals (203 results) and see which ones deserve a spot on your watchlist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com