


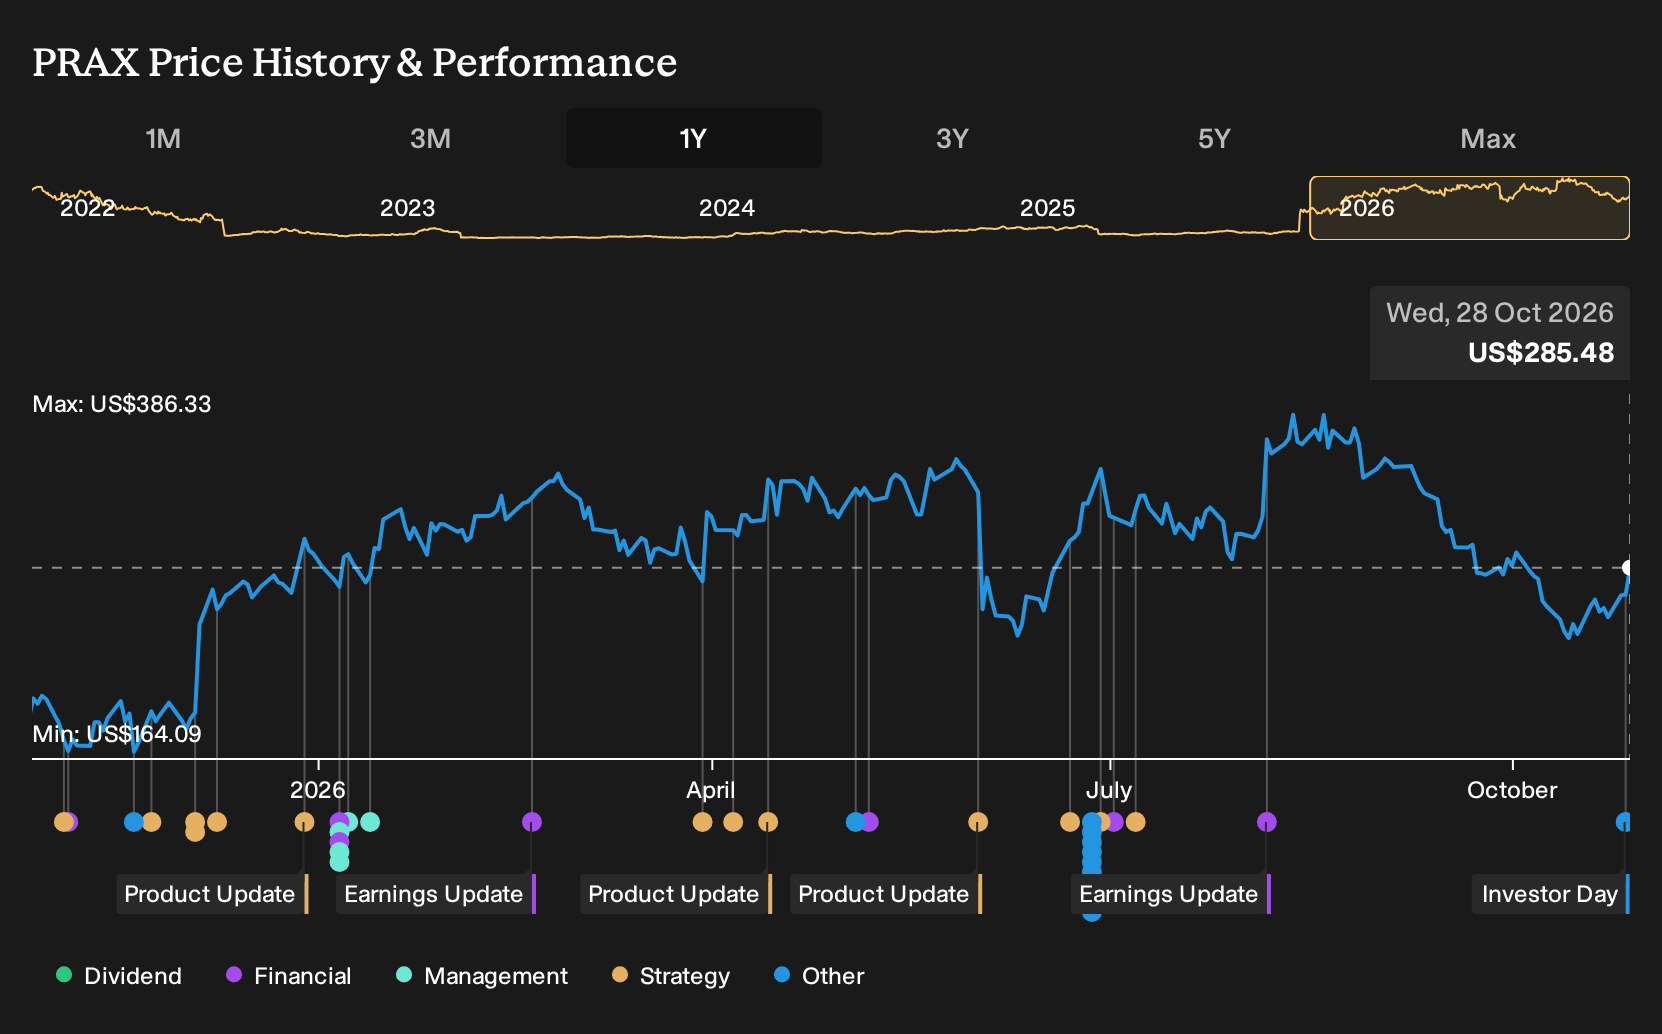
- Praxis Precision Medicines recently outlined plans to report third quarter 2026 results and host a November Investor Day focused on commercial preparations for ulixacaltamide and relutrigine, while also appearing at several healthcare investor conferences.
- The focus on launch readiness for two FDA reviewed programs signals a shift from pure R&D toward building a commercial epilepsy franchise that could reshape Praxis Precision Medicines’ operating profile.
- We will now test how Praxis Precision Medicines’ investment narrative is affected by its upcoming Investor Day spotlight on commercial launch readiness.
Scan beyond Praxis Precision Medicines and explore other epilepsy and neurology specialists that could be preparing for their own launch windows with the 36 healthcare AI stocks.
Praxis Precision Medicines Investment Narrative Recap
To own Praxis Precision Medicines, you need to believe this is a pre revenue, epilepsy focused biotech that can convert late stage CNS assets into a functioning commercial business. The short term hinge is still regulatory and clinical progress on vormatrigine and relutrigine, while the move toward launch planning does not change that core dependency.
The biggest near term risk remains execution against multiple pivotal epilepsy programs and any delay or weak data affecting eventual label scope. Commercial build out now adds another layer of execution, since a mis step in launch timing, pricing, or physician education could blunt the benefit of clinical wins and increase future funding needs.
The upcoming November Investor Day sits closest to the current story because it will detail commercial plans for ulixacaltamide and relutrigine under FDA review. That event, paired with third quarter 2026 results, should give you a better read on how far Praxis Precision Medicines has progressed from a science heavy story toward an operating epilepsy franchise.
What matters from that session is not just messaging but also practical signals on salesforce build, patient access infrastructure, and spending commitments heading into potential approvals. Those choices intersect directly with the key catalysts and risks around late stage trial outcomes, future dilution, and the firm’s ability to turn pipeline breadth into sustainable, epilepsy focused revenue streams.
Praxis Precision Medicines' current analyst narrative points to revenue of US$1.7b and earnings of US$761.6m by 2029, from earnings today of a US$339.1m loss. This implies an earnings swing of roughly US$1.1b and a very large revenue ramp from a pre revenue base.
Discover why Praxis Precision Medicines' fair value indicates a 125% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate angle on Praxis Precision Medicines focuses on cost risk rather than launch upside. Bullish analysts were still projecting about US$3.1b in 2029 revenue and roughly US$1.7b in earnings before this news, while more cautious voices flagged rising quarterly cash use as a reason to expect a much tougher path. That gap in expectations is wide. Treat this Investor Day as a chance to compare those competing stories and decide which assumptions you find more realistic.
Explore 3 other Praxis Precision Medicines fair value estimates, including one that suggests as much as 1011% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own independent research.
- A great starting point for your Praxis Precision Medicines research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Praxis Precision Medicines. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Praxis Precision Medicines' overall financial health at a glance.
Looking For More Ideas Beyond Praxis Precision Medicines?
If the Praxis Precision Medicines story has you thinking about where else late stage pipelines, cleaner balance sheets, or steadier cash flows might show up, the Simply Wall St Screener can help you cast a wider net without losing focus on quality.
- For investors who want potential upside without ignoring balance sheet strength, consider filtering for a list of solid balance sheet and fundamentals (24 results) that can better withstand funding pressure.
- If capital preservation comes first for you, map out a shortlist built from a 32 resilient stocks with low risk scores that may offer a smoother ride through volatility.
- When you want something less crowded, widen your search to a 19 high quality undiscovered gems that are already showing strong fundamentals but attract far less attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com