


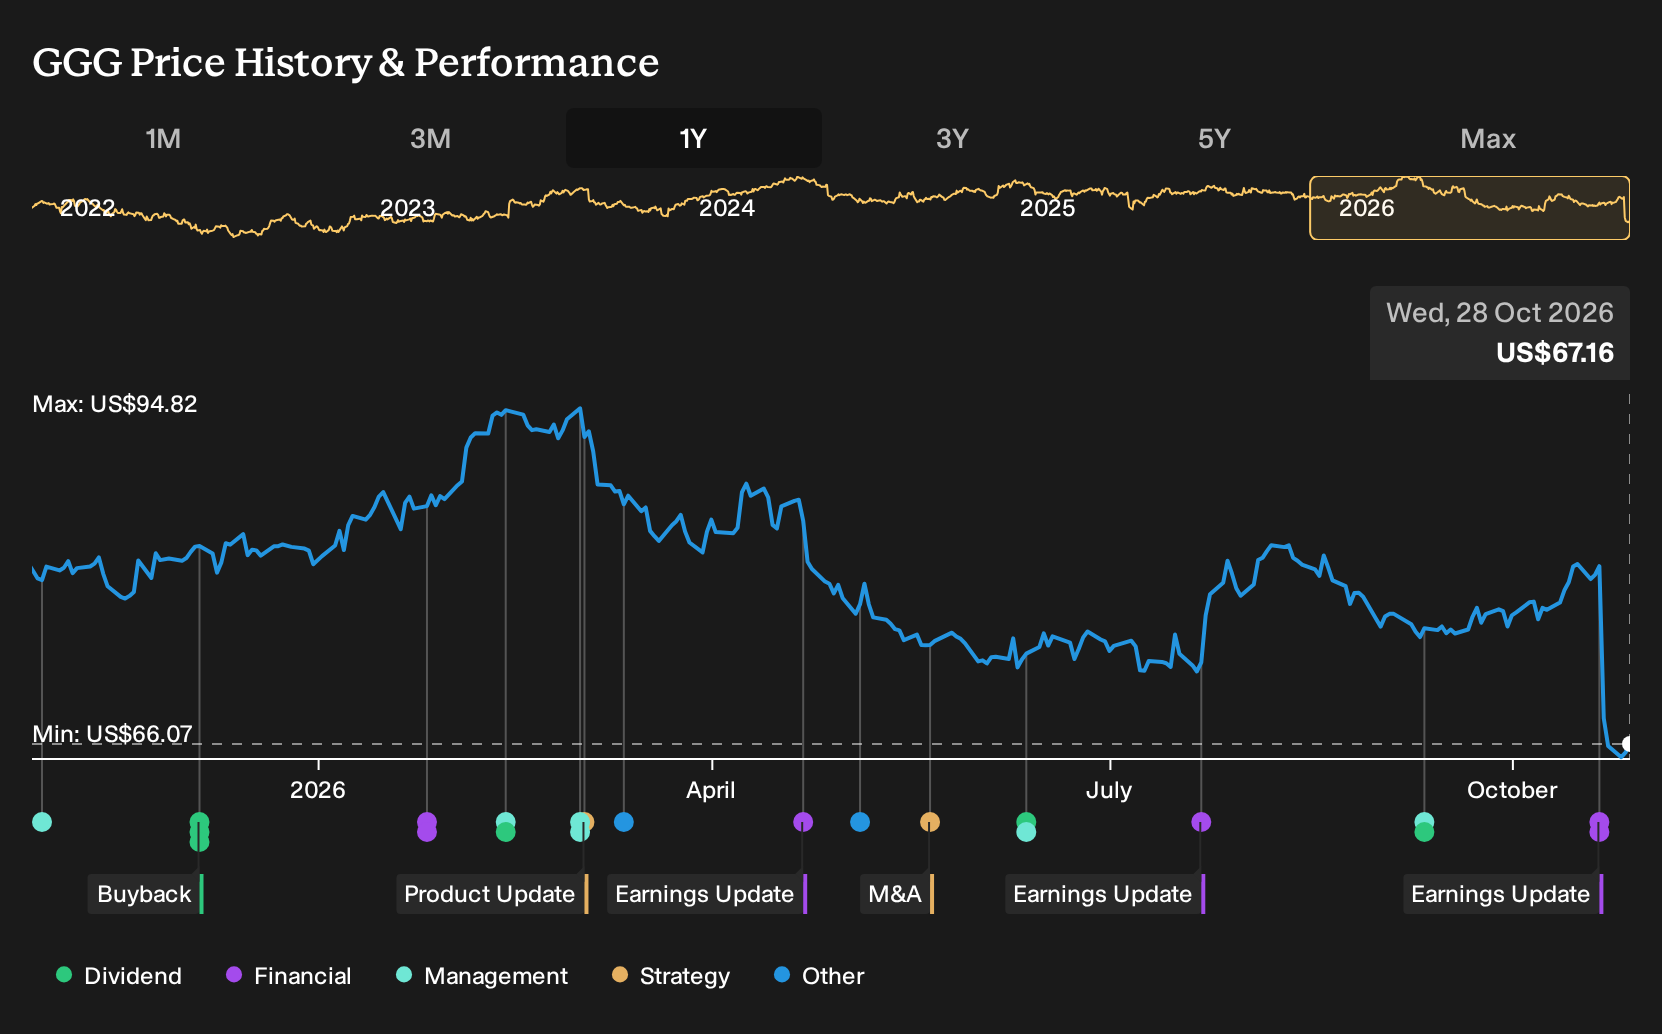
- Graco reported third quarter 2026 sales of US$586.39 million and net income of US$121.56 million, with nine month sales at US$1.72b and net income at US$384.99 million.
- The company paired higher sales with lower quarterly net income and issued fourth quarter 2026 revenue guidance of US$610 million to US$640 million, giving investors fresh insight into demand and pricing trade offs.
- We will examine how Graco's investment narrative relates to this combination of rising sales and softer quarterly earnings performance.
Graco Investment Narrative Recap
To own Graco, you need to be comfortable with a story where solid demand supports sales while profitability moves around more quarter to quarter. The latest results fit that pattern. Third quarter sales reached US$586.39 million, yet net income came in at US$121.56 million. This keeps attention on cost control, mix and pricing rather than headline revenue.
The near term swing factor is whether Graco can defend gross margins while tariffs, product costs and factory volumes all pull in different directions. Earnings softness in the quarter keeps that risk very visible. If pricing power or volumes weaken further, the main pressure point is earnings and free cash flow, not the top line.
The fresh fourth quarter 2026 revenue outlook of US$610 million to US$640 million is the announcement that ties most closely to this update. It gives you a concrete range for near term demand, which matters if you are tracking how Contractor, Industrial and Expansion Markets recover or stall from here.
Graco’s guidance now sits alongside existing catalysts such as new Contractor products and the integration of COROB, Color Service and Radia. Those projects are still about execution quality and timing. The current guidance range does not settle the margin debate. However, it frames the volume side of the equation that investors are watching most closely.
What The Current Graco Forecasts Assume
Graco's current analyst storyline leans heavily on steady top line expansion and a measured lift in profitability rather than any dramatic reset. Forecasts build in revenue rising at 8.1% a year for the next few years, with profit margins edging up from 22.4% today to 23.7% by 2029. Earnings sit at about US$517.5 million today and the consensus view targets US$693.0 million of profit and US$2.9b of revenue in 2029, which would mean a sizeable earnings step up and a business that is expected to convert a little more of every sales dollar into profit.
Graco's narrative projects US$2.9b revenue and US$693.0 million earnings by 2029. This assumes 8.1% yearly revenue growth and roughly a US$175 million earnings increase from about US$517.5 million today.
Uncover why Graco's fair value indicates a 33% potential upside to its current price, which could narrow quickly as expectations catch up.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between US$60 and about US$90.83, so private investors are clearly not marching in lockstep on Graco. Pair that spread with tariff and cost risks on one side and product launches plus acquisition integration on the other, and you get strongly differing performance expectations that are worth exploring in detail.
Explore 2 other Graco fair value estimates, including one that suggests as much as 11% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Graco research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Graco. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Graco's overall financial health at a glance.
Looking For More Graco-Sized Investment Ideas?
If you like the way Graco combines resilient demand with detailed financial disclosure, it can help to scan for other businesses with similar qualities and then compare their balance sheets, cash flows and income statements side by side using the Simply Wall St Screener.
- For investors who care about balance sheet strength and staying power, start with a curated list of solid balance sheet and fundamentals (24 results) that already clears basic quality and fundamentals checks.
- If potential mispricings interest you more than headline stories, use the focused 26 high quality undervalued stocks to surface companies where fundamentals and current pricing look out of sync.
- Income focused readers who want yield without ignoring risk can work through a targeted 6 dividend fortresses that filters for higher distributions backed by fundamental data.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com