


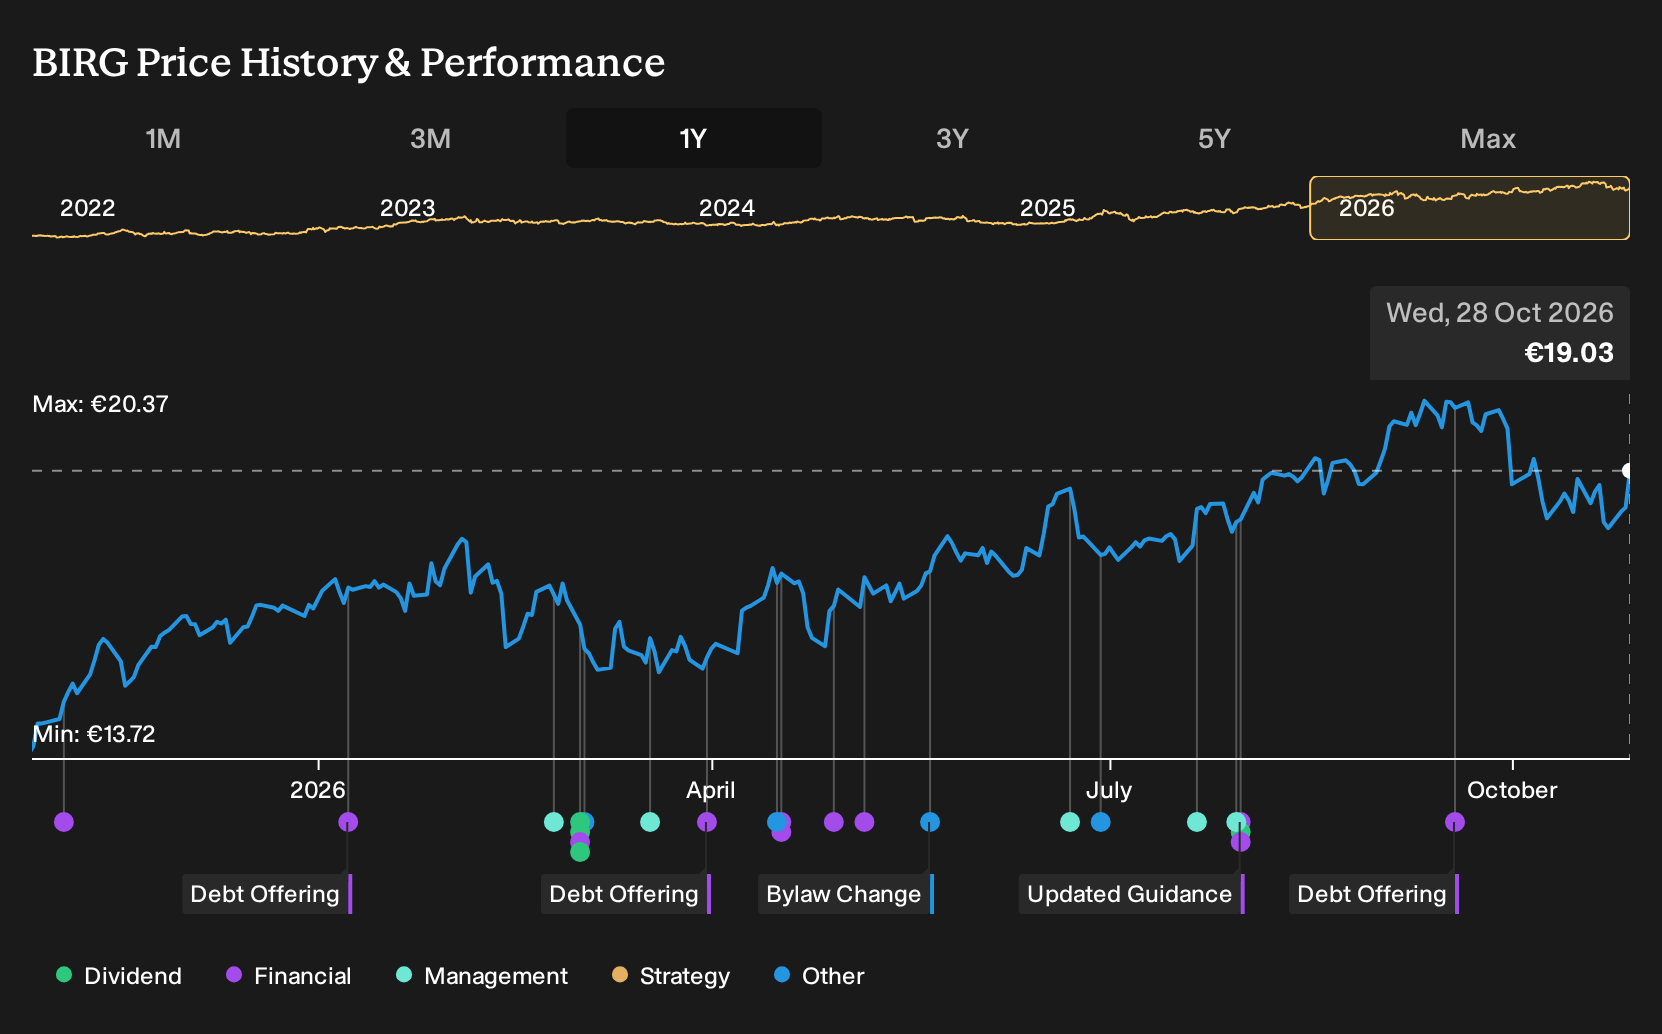
- Bank of Ireland Group released its Q3 2026 Interim Management Statement on 28 October 2026, updating investors on recent operating trends and management’s current read of the business.
- The interim statement call offered fresh commentary on lending activity, deposit behaviour and cost discipline, giving investors new information on how the group is executing against its medium term goals.
- We will now examine how Bank of Ireland Group's investment narrative could be influenced by the Q3 2026 Interim Management Statement commentary.
Scan how Bank of Ireland Group is handling lending, deposits and costs this quarter, then compare that approach with a curated list of solid balance sheet and fundamentals (203 results) for context on balance-sheet strength.
Bank of Ireland Group Investment Narrative Recap
To own Bank of Ireland Group, you need to be comfortable with a fairly traditional banking story. Loan, deposit and wealth activity are expected to carry the earnings engine, while management looks for further efficiency gains. The Q3 2026 call mainly refreshed that operating picture rather than reshaping it, so the underlying thesis around lending, fee income and cost control remains broadly intact.
Right now, the key near term swing factor is how net interest income holds up as rates evolve and the corporate book is managed. The biggest risk still sits in pressure on margins and asset quality, especially with a relatively low bad loan allowance and ongoing cost reduction plans that carry execution risk.
With no new company announcements around capital returns or major restructuring tied directly to this Q3 2026 update, the most relevant reference point is management’s existing medium term ambition to lift return on tangible equity above 17% by 2027. The call essentially acts as a checkpoint on whether current lending, deposits and wealth flows keep that goal in play.
For investors, the link to catalysts is practical. Progress on digital investment, the small business lending platform and efficiency initiatives, as reiterated on the call, feeds directly into that RoTE target and future distribution capacity. Any sign that margin pressure, competition in Irish mortgages or non core charges starts to erode those ambitions could affect how investors weigh the risks and potential rewards in Bank of Ireland Group.
Bank of Ireland Group Consensus Forecasts in Focus
Bank of Ireland Group's analyst narrative points to forecast revenue of €5.0 billion and projected earnings of €1.9 billion by 2029. This aligns with expectations for 6.0% yearly revenue growth and implies an earnings increase of about €600 million from current earnings of €1.3 billion.
Uncover why Bank of Ireland Group's fair value indicates an 11% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between €21.08 and €33.49, so retail opinions on Bank of Ireland Group already span a wide band. When these are set against risks around margin pressure, cost cuts and non core charges, there are strong reasons to compare several viewpoints before committing fresh capital.
Explore another Bank of Ireland Group fair value estimate, including one that suggests as much as 76% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Bank of Ireland Group research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Bank of Ireland Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bank of Ireland Group's overall financial health at a glance.
Looking For More Ideas Beyond Bank of Ireland Group?
Once you have formed a view on Bank of Ireland Group, it can help to set that opinion alongside a wider watchlist of opportunities that share some of the qualities you care about most. The Simply Wall St screener lets you filter for financial strength, income potential and overlooked opportunities so you can build a shortlist that fits your own risk and return preferences.
- If you want companies that already pass a tough quality and balance sheet test, start by scanning a 228 resilient stocks with low risk scores that prioritise resilience and controlled downside.
- For readers focused on long term compounding potential, compare Bank of Ireland Group with a 191 high quality undervalued stocks that combine healthy fundamentals with prices that still look restrained.
- If the goal is to spot under the radar opportunities before they attract wider attention, build a watchlist sourced from a 609 high quality undiscovered gems with solid underlying metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com