


Xencor (XNCR) has become a talking point after updated Phase 1 data for its XmAb819 kidney cancer program, presented at ESMO 2026, highlighted confirmed responses in heavily pre-treated patients with advanced clear cell renal cell carcinoma.
At a share price of US$29.99, Xencor has seen momentum build, with a 7-day share price return of 16.06%, a 30-day move of 19.96% and a 90-day gain of 48.39%. The year-to-date share price return of 101.01% and 1-year total shareholder return of 112.24% show how the recent XmAb819 data and related events have shifted how the market prices both potential upside and risk, even though the 5-year total shareholder return is still down 29.67% over a longer horizon.
Scan other antibody developers showing similar clinical momentum to Xencor with our curated list of 36 healthcare AI stocks for the next wave of healthcare focused catalysts.
The surge has rerated expectations around XmAb819 and the broader Xencor pipeline. After a move this sharp, does the current price still leave enough upside to justify the clinical and execution risk, or has the balance shifted?
Most Popular Narrative: 22% Undervalued
At a last close of $29.99 against a most-followed fair value estimate of $38.33, Xencor is framed as undervalued by narrative-driven modeling, with that gap resting heavily on how its antibody platform translates into future revenue and margins.
The robust and flexible XmAb platform allows for modular drug development and the creation of differentiated assets, expected to reduce development costs and timelines, directly benefiting future operating margins and net profitability. Clinical trial strategy emphasizes efficient dose ranging and selection, ongoing biomarker efforts, and combination-therapy optionality, positioning the company to respond rapidly to evolving standards of care and maximize the commercial potential of its pipeline, with positive implications for recurring revenue and ultimate earnings leverage.
See why 8 investors see Xencor as 22% undervalued.
Result: Fair Value of $38.33 (UNDERVALUED)
Still, the Xencor narrative leans heavily on successful late stage trials and regulatory discussions. Any delay or weaker IBD data could quickly undercut today’s fair value story.
Find out about the key risks to this Xencor narrative.
Another View: What Xencor's Sales Multiple Is Signaling
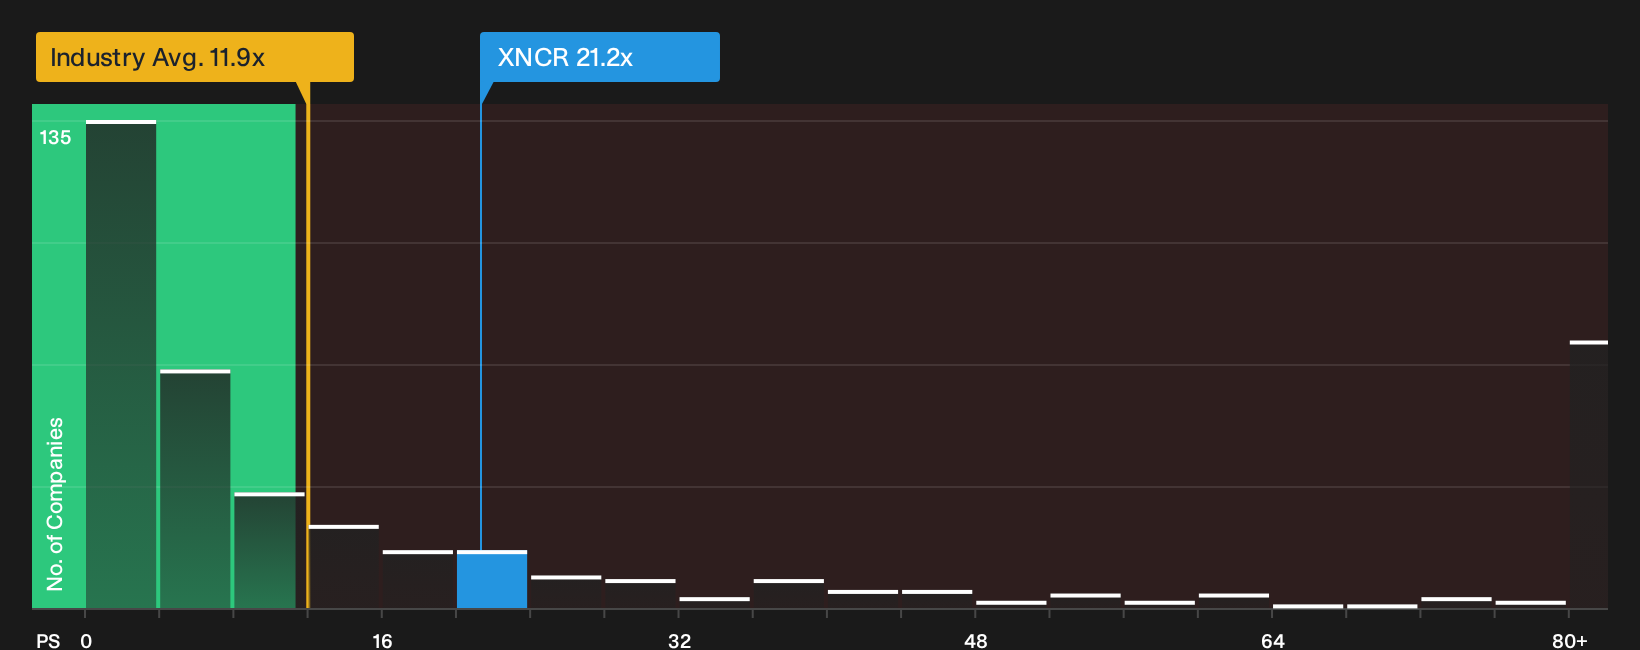
Xencor might look inexpensive relative to a US$38.33 fair value narrative, but its current P/S of 21.2x suggests a tougher story. That figure is higher than the US Biotechs sector at 11.3x, and far above a fair ratio estimate of 0.7x, which points to meaningful valuation risk if sentiment cools.
Compared with closer peers, the picture softens, since the 21.2x P/S is below a 35.9x peer average. That gap can be interpreted as some potential upside cushion or simply less downside if growth or trial progress disappoints. Which side of that trade-off seems more realistic to you today?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling torn between the optimism around Xencor and the clear risks on the table is reasonable, so move fast on your own homework and weigh both sides with 1 key reward and 1 important warning sign.
Looking for more Xencor-like investment ideas?
If Xencor has sharpened your appetite for focused research, do not stop here. Use targeted screeners to spot other opportunities before they move without you.
- Target resilient income potential by reviewing companies in the 6 dividend fortresses that pair higher yields with underlying business strength.
- Hunt for mispriced opportunities early and scan the 19 high quality undiscovered gems before wider attention closes the valuation gap.
- Prioritize capital preservation first and filter for steadier tickers through the 32 resilient stocks with low risk scores so big drawdowns do not catch you off guard.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com