


- Argan is working against a large backlog of natural gas power and data center related projects while dealing with cost pressure in its Industrial operations, and that mix of strength and strain has drawn fresh attention from investors.
- The key tension is whether Argan’s established position in complex power projects can offset thinner margins and execution risks that are now more visible across both its Power and Industrial segments.
- We will now see how Argan’s investment narrative is affected by mounting execution risk on industrial projects despite strong power infrastructure demand.
Scan how Argan’s power buildout story compares to other infrastructure plays by reviewing our curated list of 44 power grid technology and infrastructure stocks in the current market cycle.
Argan Investment Narrative Recap
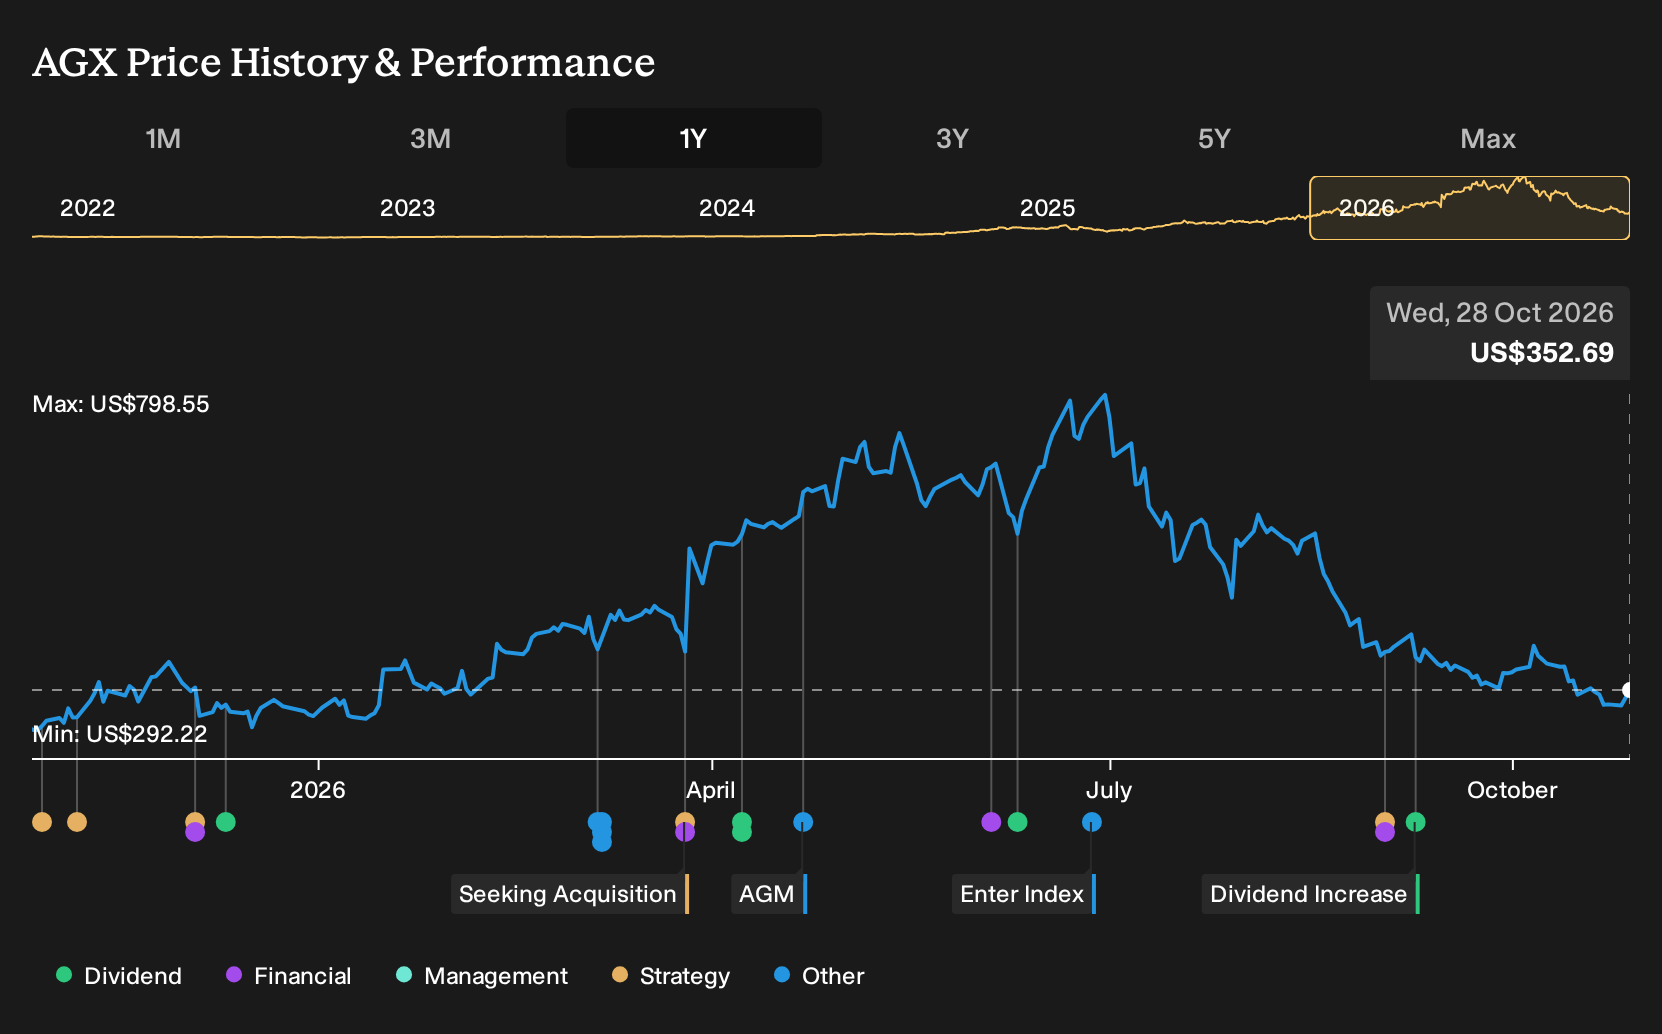
To own Argan, you need to believe the large backlog in gas fired power and data center related projects can support steady work while margins in the Power and Industrial segments stabilize. The recent pullback in AGX, with the stock down about 39% over 90 days, mostly sharpens focus on execution rather than changing the core thesis.
Right now the key near term swing factor is whether newer power contracts and data center projects convert cleanly into revenue without further pressure on consolidated gross margin. The biggest risk is that thin Industrial margins around 7.3% persist or repeat on new work, turning a growing revenue base into more volatile profitability.
With no fresh company announcements disclosed alongside this move, the most relevant reference point is still Argan’s reported backlog around US$2.5b, heavily weighted to natural gas and some renewables. That committed book of work is what links the current share price debate back to actual projects and timing of cash conversion.
For you as an investor, the question is how that backlog interacts with execution risk on Industrial and Teledata jobs, including the second North Carolina fabrication facility and data center related work. If project delivery in these areas becomes smoother while power projects stay on track, that could support the main earnings catalysts investors are watching.
What The Current Argan Forecasts Are Asking You To Believe
Argan's narrative points to forecast revenues of US$1.8b and consensus earnings of US$233.8m by 2029, based on analyst assumptions of 15.2% yearly revenue growth and an earnings increase of about US$54.5m from US$179.3m today.
Uncover how Argan's fair value indicates a 62% potential upside to its current price before the market closes.
Exploring Other Perspectives
One optimistic twist on Argan focuses on backlog quality rather than margin risk. The most bullish analysts emphasize the US$2.9b order book and had been penciling in about US$2.5b of revenue and US$322.2m of earnings by 2029. That is far above consensus, and the latest news could prompt both views to shift.
Explore 3 other Argan fair value estimates, including one that suggests as much as 62% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Argan research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Argan. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Argan's overall financial health at a glance.
Looking For More Investment Ideas Beyond Argan?
Once you have a view on Argan, it can help to compare it with other opportunities that fit different risk and income profiles. The Simply Wall St Screener lets you filter by quality, balance sheet strength, income focus, and more, so you can build a watchlist that suits your own approach.
- If capital preservation sits high on your priority list, start with a group of companies that score well on stability through the 32 resilient stocks with low risk scores.
- For investors who want to lean toward quality at a reasonable entry point, scan for businesses with robust fundamentals trading below their estimated worth using the 26 high quality undervalued stocks.
- If steady income matters as much as price appreciation, focus on companies with stronger payouts and higher yields through the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com