


Cash rich companies are back in the spotlight after Wall Street recently rewarded businesses that can fund big AI and tech ambitions from their own cash flow. That puts low risk Canadian leaders with strong balance sheets in a sweet spot. You get resilience when markets wobble and firepower when opportunities appear. This article highlights three of the strongest options from that group and explains why they deserve a closer look.
The three stocks below are just a starting sample, and the full Low Risk Leaders screen surfaced 5 more companies with equally compelling balance sheet strength and risk profiles that are not covered here.
If you want to identify, compare, and analyze those extra contenders alongside your own holdings, head straight into the Low Risk Leaders screener
China Gold International Resources (TSX:CGG)
Overview: China Gold International Resources operates large scale gold and copper mines in China, with CSH providing steady, asset backed cash flow.
Operations: The business generates about $399 million from produced gold and $1.24b from copper concentrate, with mining as its main revenue source.
Market Cap: CA$13.27b
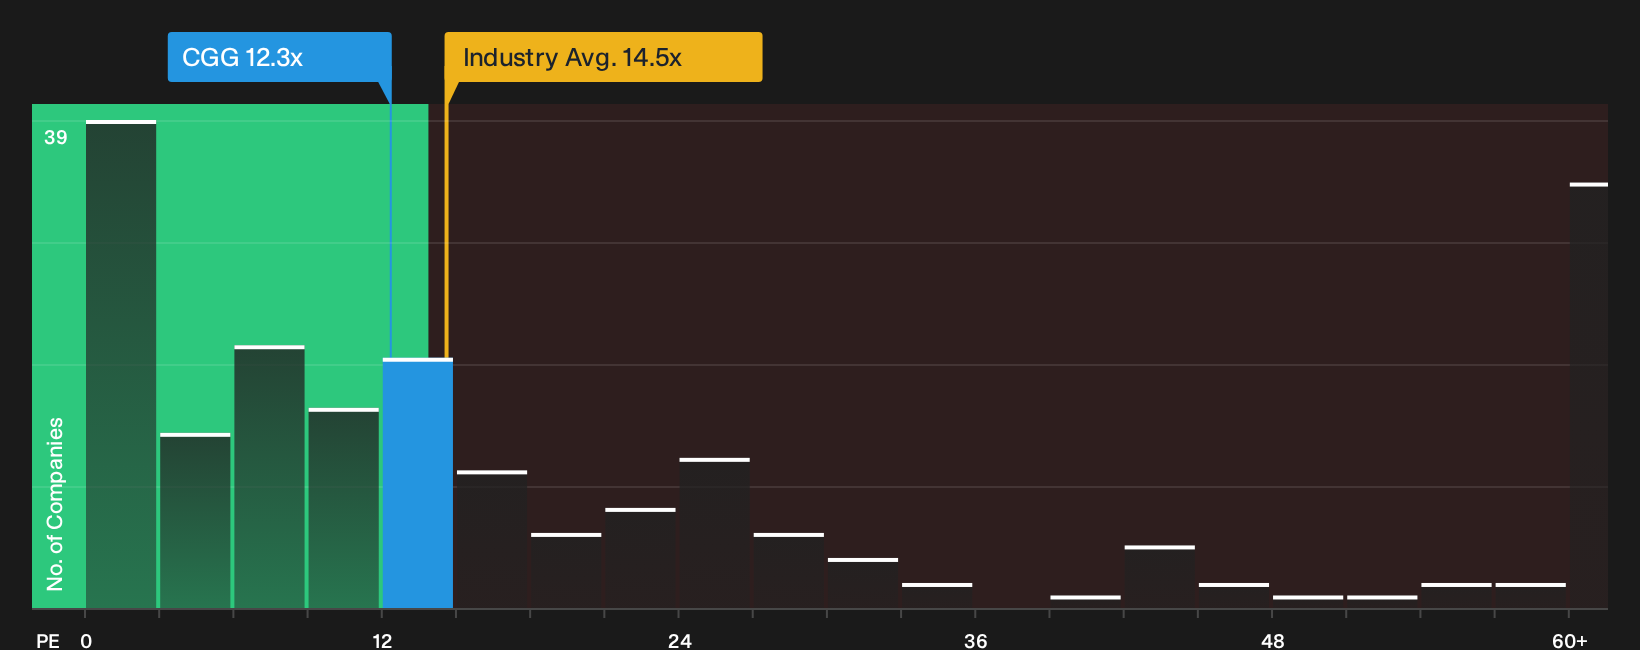
China Gold International Resources fits the Low Risk Leaders theme through high ownership of the producing CSH gold mine, which supports predictable cash generation and strong asset backing. Investors currently see low P/E pricing relative to peers and very high recent profitability. One unresolved funding structure pressure could meaningfully influence how durable those margins feel over time.
To see how that funding structure pressure shows up in the risk and upside mix, go straight to the 4 key rewards and 1 important warning sign
Sprott (TSX:SII)
Overview: Sprott is a Toronto based asset manager that runs precious metals funds and ETFs with tightly audited, physically backed bullion holdings.
Operations: Sprott generates about $224 million from exchange listed products, $95 million from managed equities, and $80 million from private strategies, primarily in Canada.
Market Cap: CA$3.87b
Sprott gives this Low Risk Leaders list a mix of audited physical bullion funds, conservative custody practices, and fee based profitability. This is supported by Q2 2026 revenue of US$80.22 million and net income of US$34.26 million.
That steady fee engine is only half the story, so walk through the analysis report for Sprott to see how Sprott’s precious metals focus could reshape its next chapter.

DPM Metals (TSX:DPM)
Overview: DPM Metals is a Toronto based miner that acquires, develops, and operates gold focused projects in Bulgaria, Bosnia, Serbia, and Ecuador. It uses current production and near term European gold assets to support the Low Risk Leaders theme of asset backed resilience.
Operations: DPM Metals generates about $744 million from the Chelopech mine, $275 million from Ada Tepe, and holds a $272 million segment adjustment.
Market Cap: CA$12.00b
DPM Metals matters for this Low Risk Leaders screen because its producing European gold assets and liquidity position give it cash funded growth options that do not rely heavily on fresh borrowing.
"The successful advancement of the Čoka Rakita project, including progress on the underground feasibility study and permitting steps that support a potential early 2027 construction start, points to future high margin gold production that could support revenue and earnings growth once the mine enters its initial years of operation."
What happens to DPM Metals’ margin profile if a single embedded cost pressure shifts against that high grade European growth plan?
If that single cost input really is the swing factor, read the full narrative for DPM Metals to see how DPM Metals could still accelerate its next phase.

Seeking Fresh Alternatives Before They Fly
Market leaders can change fast. Fresh ideas move from quiet accumulation to full breakout while most investors are caught watching yesterday’s winners. Scan these curated shortlists before the momentum is gone and consider them while they are still early.
- Target resilient income streams by reviewing a curated mix of companies in the 3 dividend fortresses before yields change and prices move away from today’s starting range.
- Identify potential compounders by filtering for a carefully selected 4 high quality undervalued stocks that may still sit under the radar for now, before renewed momentum affects the current discount.
- Review opportunities in the metals space by studying a focused group of 35 elite gold producer stocks while sentiment is still evolving and institutional money has not fully moved in.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com