


Warrior Met Coal (HCC) is back in focus after its board approved a regular quarterly cash dividend of $0.08 per share, with payment set for November 13, 2026.
Recent trading tells a mixed story for Warrior Met Coal. The share price has pulled back, with a 1-day share price return of 4.49% down and a 30-day share price return of 9.07% down. However, the 1-year total shareholder return of 30.39% and 5-year total shareholder return of 288.75% point to strong longer term momentum, as investors weigh the freshly affirmed dividend alongside expectations for the upcoming November earnings release and previous analyst commentary around the stock.
Compare Warrior Met Coal with other miners that are under pressure or gaining traction by checking our hand picked list of list of solid balance sheet and fundamentals (24 results)
The recent pullback in Warrior Met Coal could either reflect the market cooling on sentiment after a strong multi year run, or a misread of the underlying earnings power. The next step is to test the valuation.
Most Popular Narrative: 24% Undervalued
Against the last close of $83.43, the most followed narrative pegs Warrior Met Coal’s fair value at about $109.33. This frames the recent pullback as a question of whether cash generation from Blue Creek is being fully reflected in the price.
The ahead-of-schedule and on-budget launch of the Blue Creek longwall in early Q1 2026 accelerates Warrior Met Coal's transition from capital investment to higher-volume revenue generation. Q2 2026 record sales volumes of 3.7 million short tons and a 45% increase in production indicate further potential impact on revenue and net margins as low-cost volumes continue to ramp.
See why 36 investors see Warrior Met Coal as 24% undervalued.
Result: Fair Value of $109.33 (UNDERVALUED)
Still, the Warrior Met Coal story can be knocked off course if freight and demurrage costs stay elevated, or if steel demand weakens further and pressures realized pricing.
Find out about the key risks to this Warrior Met Coal narrative.
Another View: Warrior Met Coal Through The P/E Lens
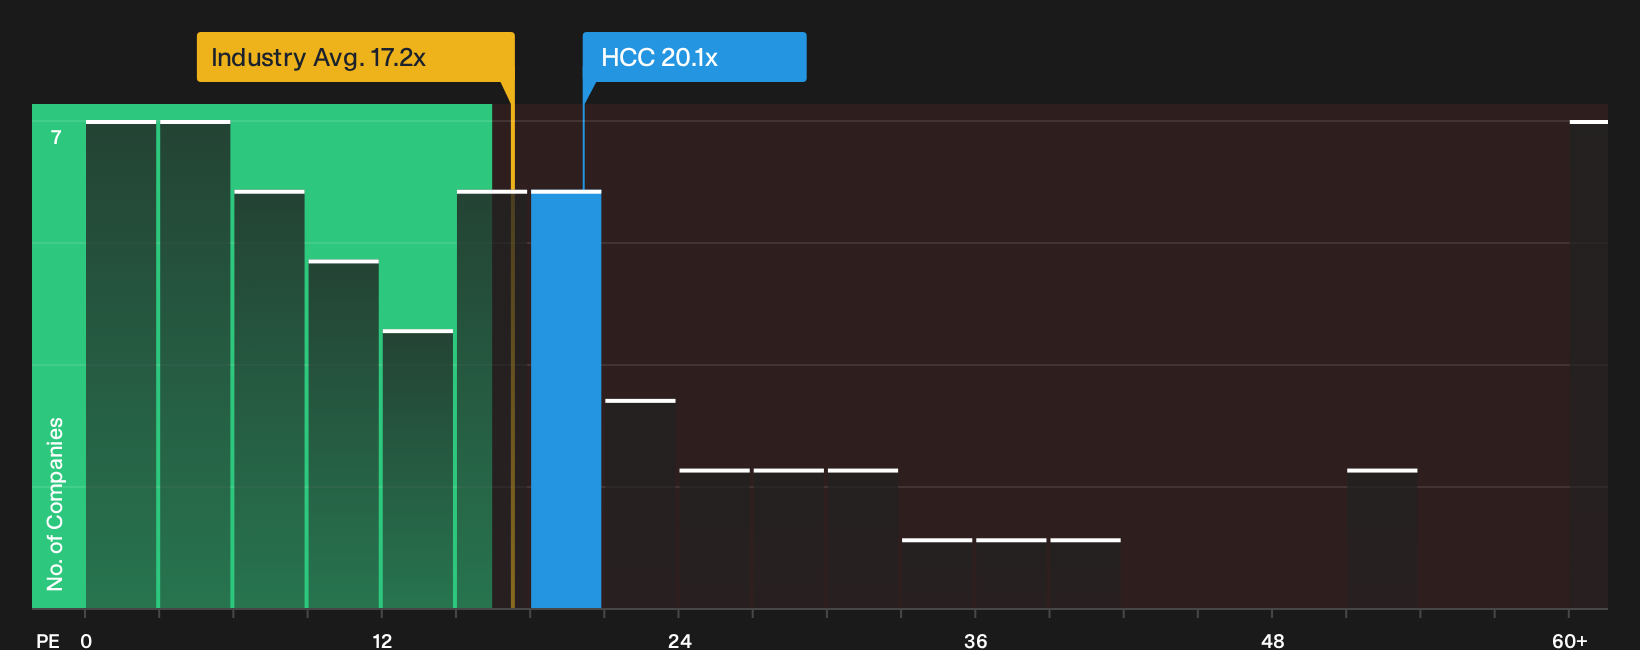
One narrative says Warrior Met Coal is about 24% undervalued on a fair value of $109.33. The P/E picture tells a cooler story. The stock trades on 20.1x earnings, slightly above a fair ratio of 20x and above the US Metals and Mining industry at 17.2x, which points to less margin for error if sentiment turns.
Given that gap, the question is whether you treat the current P/E as paying up for quality, or as a sign to demand a bigger discount before committing fresh capital.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Warrior Met Coal is split, which is exactly why it pays to move quickly, check the underlying data yourself, and decide where you stand in light of the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Warrior Met Coal?
Do not park your research on Warrior Met Coal and stop there. Broaden your watchlist with fresh ideas that fit clear, disciplined criteria using targeted screeners.
- Target potential mispricings by reviewing companies on our carefully filtered list of 26 high quality undervalued stocks.
- Strengthen your income stream by scanning stocks on the 6 dividend fortresses that offer higher yields with specific supporting metrics.
- Limit downside risk by focusing on companies highlighted in our 32 resilient stocks with low risk scores that show more resilient financial profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com