


- Enerpac Tool Group reported Q4 2026 sales of US$185.7 million and net income of US$24.4 million, with adjusted earnings and revenue ahead of analyst expectations.
- The firm paired this earnings beat with an ESOP related shelf registration and a long dated amended credit facility that reshapes its funding flexibility and capital structure.
- We will examine how Enerpac Tool Group's investment narrative is influenced by the earnings beat and its cash flow profile.
Scan how Enerpac Tool Group’s latest earnings and financing moves compare with peers by lining it up against 26 high quality undervalued stocks that also pair cash generation with balance sheet discipline.
Enerpac Tool Group Investment Narrative Recap
To own Enerpac Tool Group, you need to be comfortable with a slow but steady industrial story that leans on infrastructure, energy transition projects and higher margin tools. The latest quarter showed US$185.7 million in sales and US$24.4 million in net income, with adjusted earnings above expectations but headline profit lower than a year ago.
The key short term catalyst remains execution on project demand while integrating acquisitions and EMEA service restructuring. The biggest near term risk still looks like softer industrial activity in core regions, which would make it harder to turn new products and cost work into higher earnings.
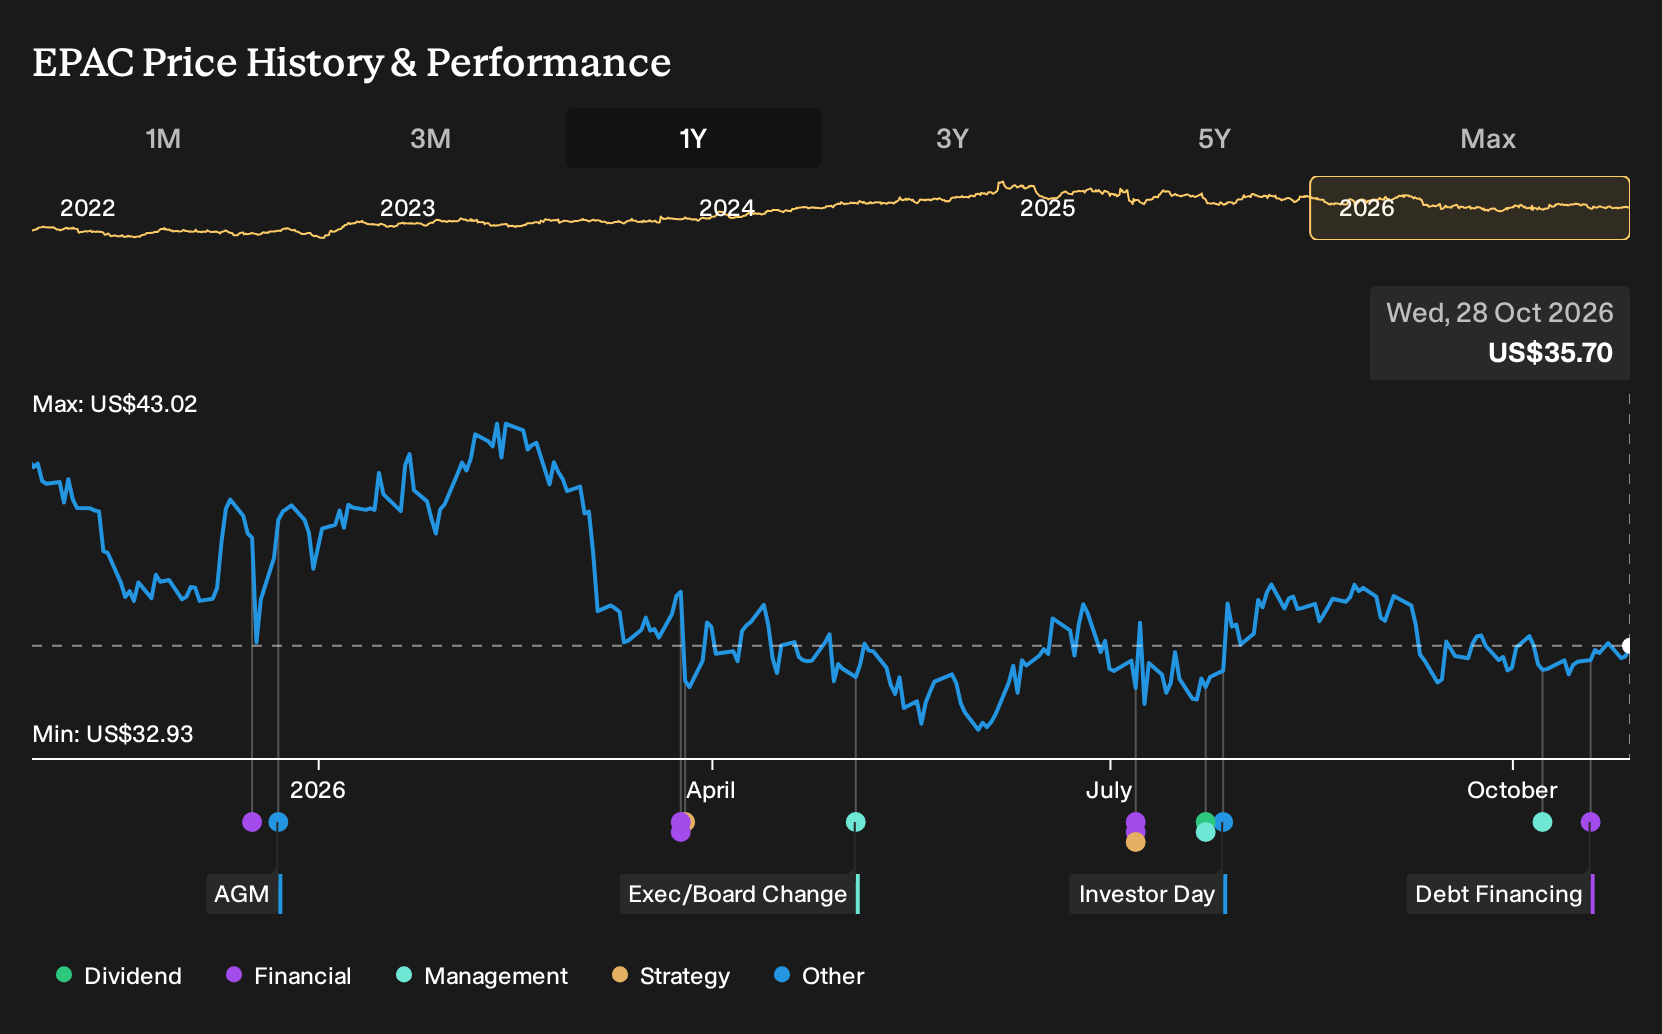
The most relevant update here is the amended and restated Credit Agreement. Enerpac Tool Group now has a US$550 million revolving credit facility and a US$300 million term loan that run to October 16, 2031, replacing the prior structure that was due in 2027.
This longer dated debt, with interest costs tied to the net leverage ratio, gives the business room to fund M&A, restructuring and product launches while keeping financial covenants in focus. For investors, execution against those operational catalysts under this new capital structure is what will matter most.
What The Current Analyst Framework Implies For Enerpac Tool Group
Analysts currently frame Enerpac Tool Group around moderate top line expansion and firmer profitability rather than a high growth story. The consensus view points to revenue growth of 4.7% a year over the next three years, with earnings today of US$93.3 million and a forecast of US$123.6 million by 2029. That shift implies an earnings increase of about US$30 million, with the forecast horizon focused on the 2029 financial year.
Enerpac Tool Group's narrative projects US$727.5 million revenue and US$123.6 million earnings by 2029. This requires 4.7% yearly revenue growth and about US$30 million earnings increase from US$93.3 million today.
The consensus valuation framework ties those operating assumptions directly into the current share price debate. On the numbers provided, the business would reach US$727.5 million of revenue and US$123.6 million of earnings in 2029, with the stock trading on a P/E of 22.9x versus 19.1x today and below the cited 24.5x multiple for the wider US machinery peer group. For investors, that set up essentially asks whether a low to mid single digit revenue trajectory and higher margin profile, discounted at 8.6%, is enough to justify that P/E step up.
Uncover why Enerpac Tool Group's fair value indicates a 34% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
The three fair value estimates from the Simply Wall St Community cluster between about US$44.55 and US$48 per share, which still leaves room for disagreement on Enerpac Tool Group after the latest earnings, credit agreement and ESOP shelf. Use that spread, along with the mix of tariff risk, industrial demand and infrastructure or energy transition catalysts, as a prompt to compare several contrasting viewpoints before forming your own view.
Explore 2 other Enerpac Tool Group fair value estimates, including one that suggests it could be worth just $44.55!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Enerpac Tool Group research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Enerpac Tool Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Enerpac Tool Group's overall financial health at a glance.
Looking for more investment ideas beyond Enerpac Tool Group?
Once you understand where Enerpac Tool Group fits in your portfolio, it often helps to compare it with a wider range of opportunities that share some of the qualities you value most, whether that is balance sheet strength, income potential, or mispriced quality.
- If capital preservation and smoother ride potential matter most to you, scan a curated set of resilient candidates through the 32 resilient stocks with low risk scores.
- For investors who care about strong finances first and story second, sort through a targeted list of solid balance sheet and fundamentals (24 results) to see which businesses match that profile.
- If you want to widen the search beyond well known tickers, cast a wider net across a 19 high quality undiscovered gems that combine quality fundamentals with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com