


AI related spending is giving the US economy fresh momentum, and investors are rewarding companies that can fund big projects from steady cash flows. Reliable dividend payers with higher yields suddenly look less boring and more like a practical way to stay invested while growth stories play out. This article highlights three long running income stocks that combine resilience with yields above 5%, and explains what sets each apart.
The three high yield Dividend Aristocrats covered below are just a sample, and the full screen surfaced 221 more income stocks with similarly robust stories that are not covered in this article. To identify and analyze the highest conviction ideas, go straight to the Dividend Aristocrats screener.
Dah Sing Banking Group (SEHK:2356)
Overview: Dah Sing Banking Group is a Hong Kong based bank providing personal and corporate banking, mortgages, cards, and treasury services across Greater China.
Operations: The bank generates most of its HK$6.5b revenue from Personal Banking at HK$3.7b and Treasury and Global Markets at HK$2.2b, with smaller contributions elsewhere.
Market Cap: HK$18.46b
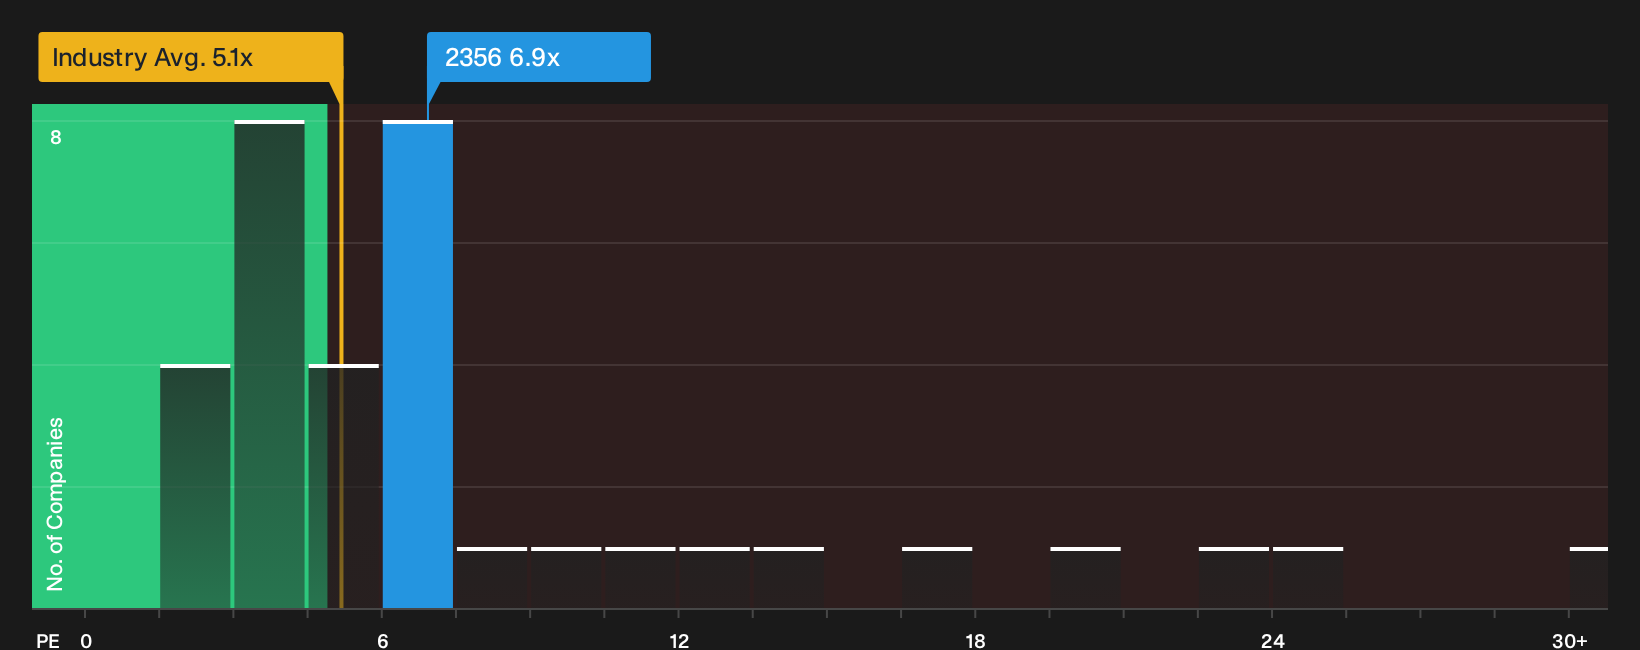
Dah Sing Banking Group leans on interest income from mortgages, deposits, and its treasury book to fund a dividend yield above 5%. Its P/E of 6.9x and net interest income of HK$2,970.27 million suggest earnings power that supports those payouts. Income-focused investors may wish to monitor how any unresolved pressure on loan quality could influence future dividend decisions.
With dividend resilience tied to that loan book, now is the time to read the 3 key rewards and 3 important warning signs and see what the headline yield might be masking.
Chongqing Rural Commercial Bank (SEHK:3618)
Overview: Chongqing Rural Commercial Bank is a Chongqing headquartered lender focused on retail and corporate deposit and lending services across mainland China.
Operations: The bank generates CN¥7.7b from Retail Banking, CN¥9.8b from Corporate Banking and CN¥6.5b from Financial Market Operations, almost entirely within the PRC.
Market Cap: HK$90.48b
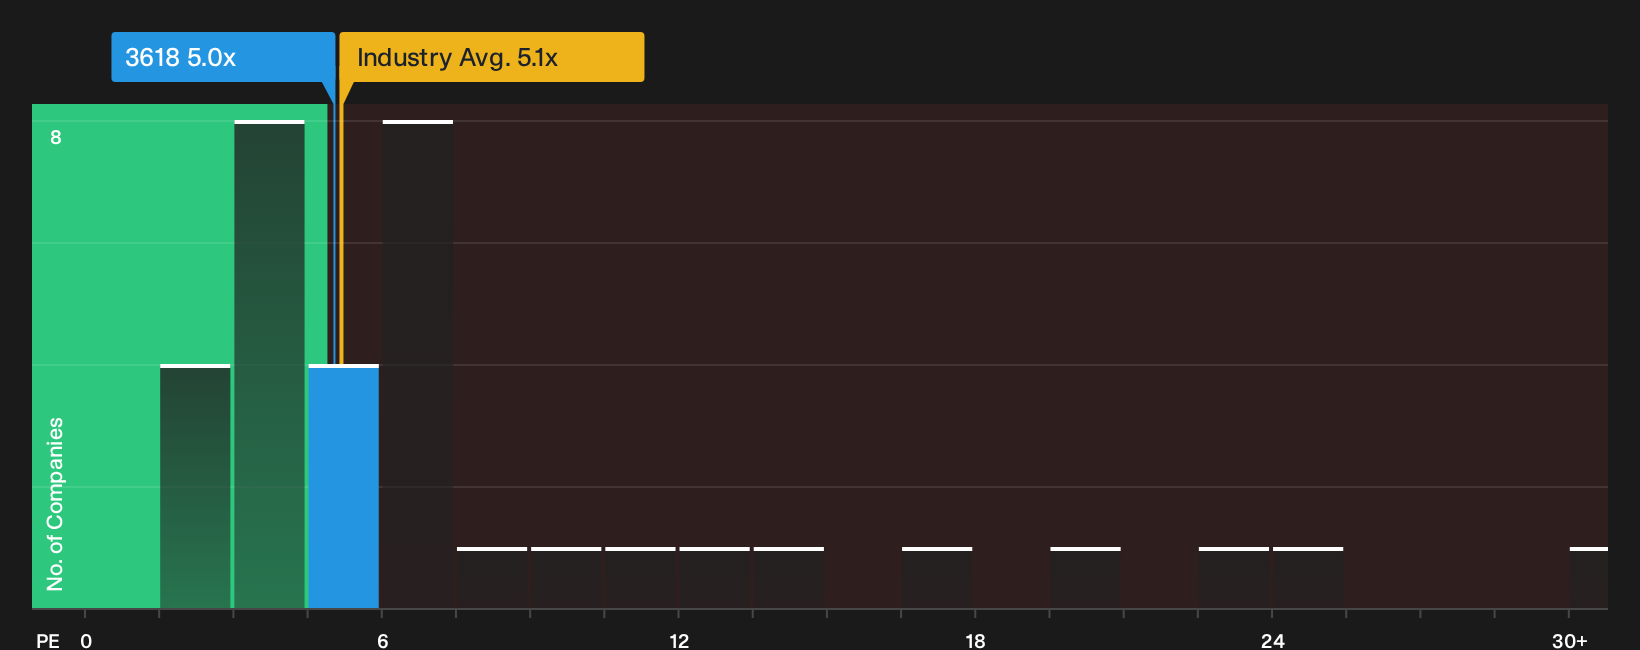
Chongqing Rural Commercial Bank brings a high net profit margin of 51.3% and a P/E of 5x to the Dividend Aristocrats theme. Its large retail and corporate lending and deposit base provides recurring interest income that can underpin a 5%+ yield. Income-focused investors see a combination of earnings quality and an apparent discount to fair value, while the outlook for that headline yield is still linked to how one unresolved dividend stability issue is ultimately addressed.
That unresolved dividend question makes it worth reading the 4 key rewards and 1 important warning sign to see whether Chongqing Rural Commercial Bank’s yield is masking something or is underappreciated.
Nippon Shokubai (TSE:4114)
Overview: Nippon Shokubai is a Japanese chemical producer supplying acrylics, superabsorbent polymers and construction related polymers that support steady infrastructure demand.
Operations: Nippon Shokubai generates about ¥313.3b from its Materials segment and ¥125.9b from Solutions, with a small unallocated adjustment.
Market Cap: ¥382.0b
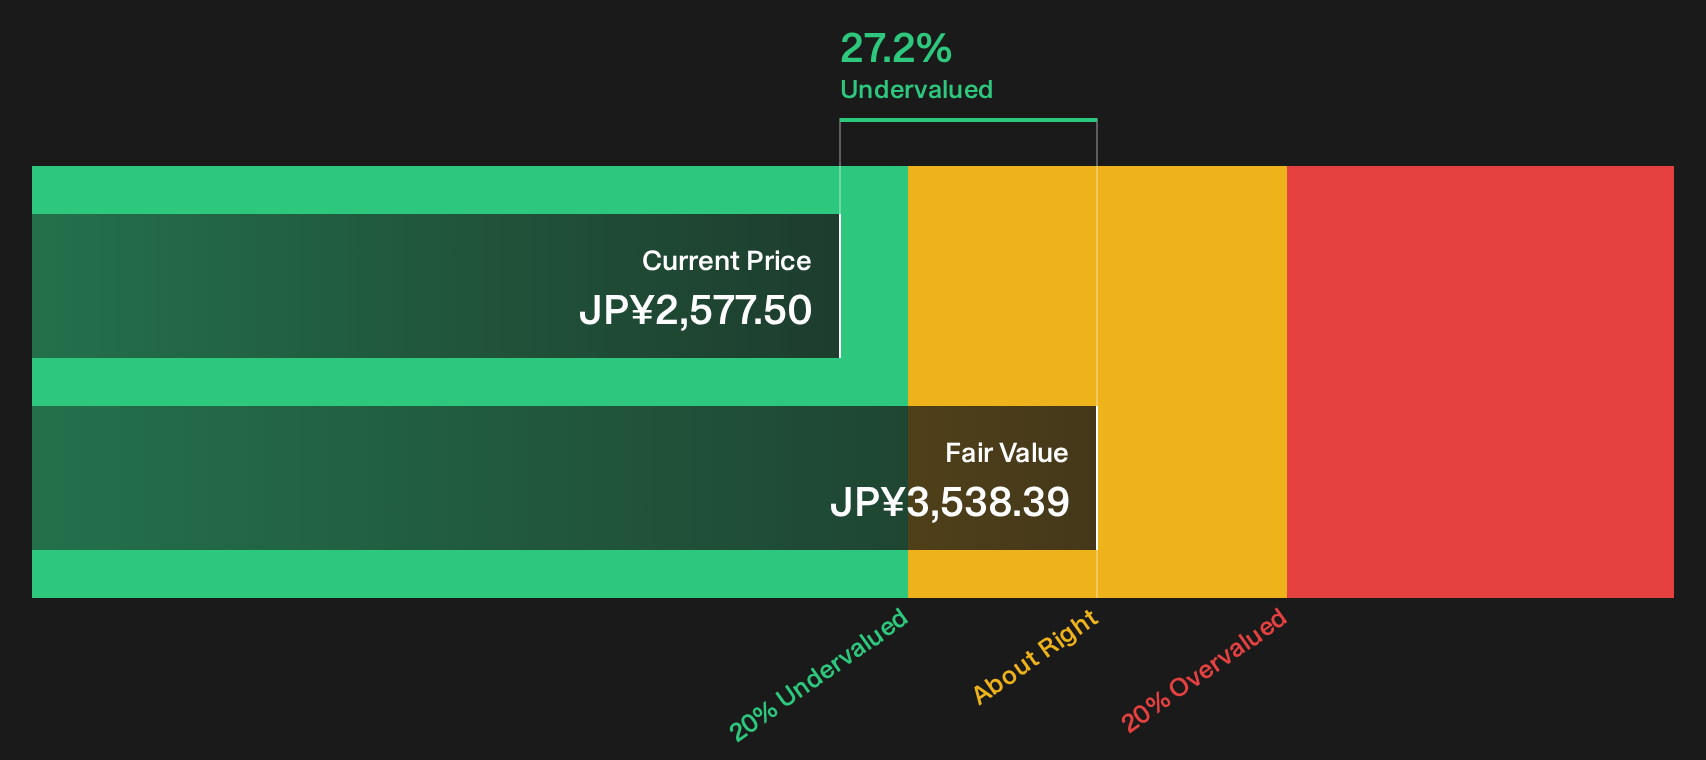
Nippon Shokubai links into the Dividend Aristocrats idea through its construction focused polymers that serve infrastructure projects, where demand tends to be long lived. A 5.4% yield, 32% earnings growth over the past year and an indicated discount to estimated fair value may interest income-focused investors, although one pressure on cash flows could still reshape how secure that payout feels.
That pressure on cash flows makes Nippon Shokubai a classic case for the 3 key rewards and 1 important warning sign where the headline yield meets the full story behind it.
Seeking Fresh Alternatives Beyond Dividends?
Some of the most interesting ideas start to move quietly, then momentum builds and prices fly before most investors notice. Scan these fresh lists while it matters and get in early.
- Target reliable cash generators by focusing on companies described as list of solid balance sheet and fundamentals (203 results) so you are not caught chasing fragile balance sheets after prices have already broken out.
- Hunt for future leaders in automation by scanning 96 robotics and automation stocks before the crowd prices in the potential and early gains start dropping out of reach.
- Position for the next wave of energy infrastructure by reviewing 44 power grid technology and infrastructure stocks while many of these opportunities are still flying under the radar for now.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com