


- The UK government has agreed to provide Rolls-Royce Holdings with up to £1.25b of taxpayer support to keep development and production of its next-generation UltraFan turbofan engine in Britain, alongside £2.5b of planned company investment over 10 years targeting the short-haul aircraft market.
- This funding package ties Rolls-Royce’s future engine technology roadmap directly to domestic industrial policy and job creation, with plans for 3,300 UK roles by 2029. This could influence how investors view the durability of the civil aerospace franchise and the company’s UK manufacturing footprint.
- The focus now is on how Rolls-Royce Holdings’ investment narrative absorbs large UK taxpayer support for UltraFan development and domestic production commitments.
Scan how government-backed engineering stories like Rolls-Royce Holdings stack up against other potential opportunities by running your eye over our curated shortlist of list of solid balance sheet and fundamentals (10 results)
Rolls-Royce Holdings Investment Narrative Recap
To own Rolls-Royce Holdings, you effectively need to believe the current uplift in profitability, cash generation and capital returns can be sustained while big programmes like UltraFan, SMRs and Power Systems stay on track. The new £1.25b UK support plus £2.5b of planned UltraFan spending ties that bet even more tightly to execution in civil aerospace.
In the near term, the main swing factor is still how reliably higher margin long term service agreements and Power Systems orders convert into cash, given supply chain cost pressures and tighter component availability. The primary risk remains that persistent input cost inflation and any disruption from large new engine programmes erode margins and free cash flow.
With no fresh company announcements beyond the UltraFan package flagged here, the most relevant context is the existing plan for higher civil aerospace contract margins through 2028 and the ambition to extend that cash benefit well beyond the current planning window. Government backing does not change those contracts, but it does underpin the engineering roadmap that supports future service revenues.
For you as a shareholder, that means the operational story still hinges on three moving parts. Rolls-Royce Holdings needs to deliver the time on wing gains it is targeting on in service engines, turn Power Systems order intake into profitable shipments for data centers and governments, and keep UltraFan development and domestic production commitments from creating cost overruns that dilute the high margin aftermarket and SMR opportunities.
Rolls-Royce Holdings' analyst narrative links the UltraFan push to a broader set of expectations that revenues reach £30.4b and earnings come in at £4.7b by 2029, based on 9.5% yearly revenue growth and an earnings uplift of about £1.7b from £3.0b today.
Uncover why Rolls-Royce Holdings' fair value indicates a 37% potential upside to its current price, which could close faster than many investors expect.
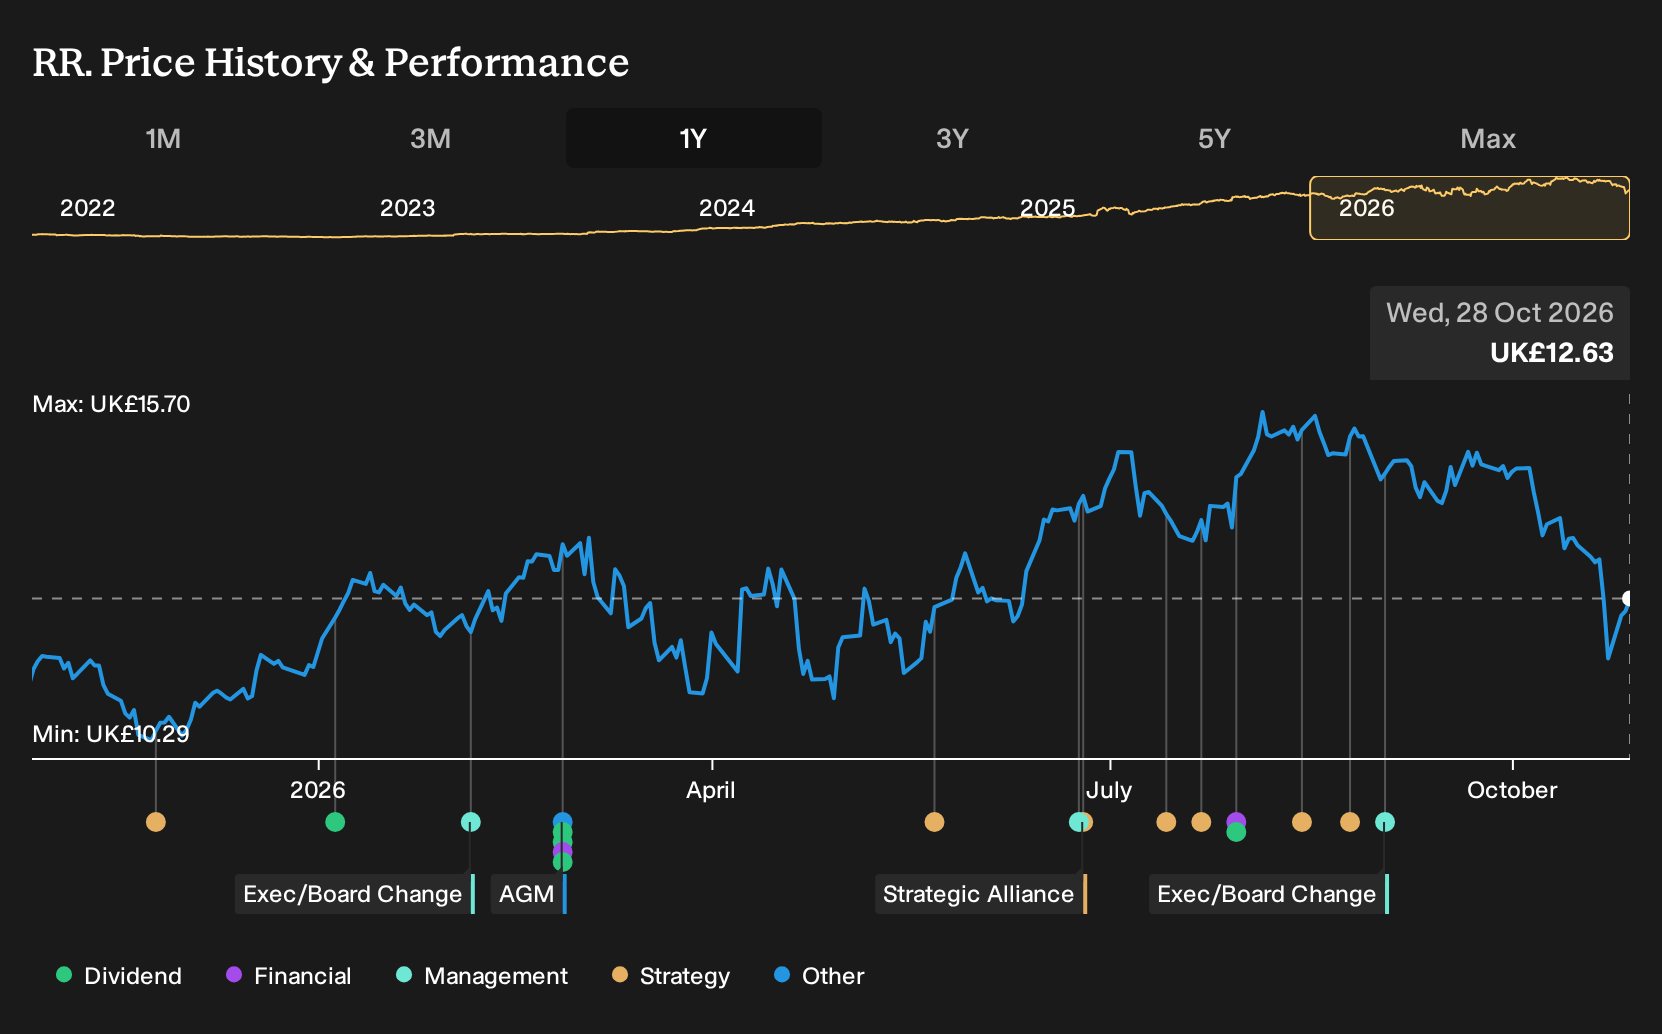
Exploring Other Perspectives
Some of the most optimistic analysts already had a different angle on Rolls-Royce Holdings before this UK funding news. They were working off revenue expectations of about £33.0b and earnings near £6.4b by 2029, assuming stronger civil and Power Systems momentum. You can compare that upbeat view with your own read on taxpayer backed UltraFan support and how opinions might shift from here.
Explore 6 other Rolls-Royce Holdings fair value estimates, including one that suggests as much as 58% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Rolls-Royce Holdings research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Rolls-Royce Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Rolls-Royce Holdings' overall financial health at a glance.
Looking For More Ideas Beyond Rolls-Royce Holdings?
If the Rolls-Royce Holdings story has sharpened your thinking, use that momentum to size up a wider field of opportunities with the Simply Wall St Screener.
- If you want companies that look cheap relative to their fundamentals, scan our curated list of 10 high quality undervalued stocks that may warrant a closer look.
- If capital preservation matters just as much as upside, filter for steadier candidates across our 5 resilient stocks with low risk scores and see which ones match your comfort level.
- If you prefer firms with sturdier finances, start with the list of solid balance sheet and fundamentals (10 results) to focus on businesses backed by stronger balance sheets and fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com