


Principal Financial Group Q3 earnings and dividend decision
Principal Financial Group (PFG) caught investor attention after Q3 2026 results showed revenue of US$4,616.4 million and net income of US$631.9 million, alongside an 8% increase in the quarterly dividend to US$0.85 per share.
At a share price of US$111.84, Principal Financial Group has delivered a 25.07% year to date share price return. The 1 year total shareholder return, including dividends, sits at 39.83%, and the 5 year total shareholder return of 94.94% points to momentum that has been building rather than fading, despite recent short term share price softness around the Q3 earnings and dividend increase headlines.
Scan beyond Principal Financial Group and compare its recent momentum and dividend profile with a curated group of income-focused stocks in the 6 dividend fortresses
Principal Financial Group now trades slightly above average analyst targets yet screens at a wide intrinsic value discount. Is the market rightly cautious after the recent run, or mispricing what the latest numbers signal about resilience?
Most Popular Narrative: 1% Overvalued
The most followed narrative currently places Principal Financial Group's fair value at about $111.17, just below the last close of $111.84. This frames the Q3 rally as largely in line with that thesis rather than a clear bargain or bubble.
The updated thesis on Principal Financial Group largely reaffirms the prior view while putting more weight on the shift toward fee based, scalable platforms and the mix change in asset management that could support a steadier earnings profile.
Earlier, Principal Financial Group was framed broadly around growth in retirement, asset management, and international expansion. Now the focus is more specific, with an emphasis on fee based, scalable retirement platforms and small business benefits that tie directly to recurring revenue.
See why 7 investors see Principal Financial Group as 1% overvalued.
Result: Fair Value of $111.17 (OVERVALUED)
Still, the PFG narrative leans on a tightrope, with fee pressure and recent US$11b active equity outflows both capable of quickly challenging that fair value view.
Find out about the key risks to this Principal Financial Group narrative.
Another view on Principal Financial Group's value
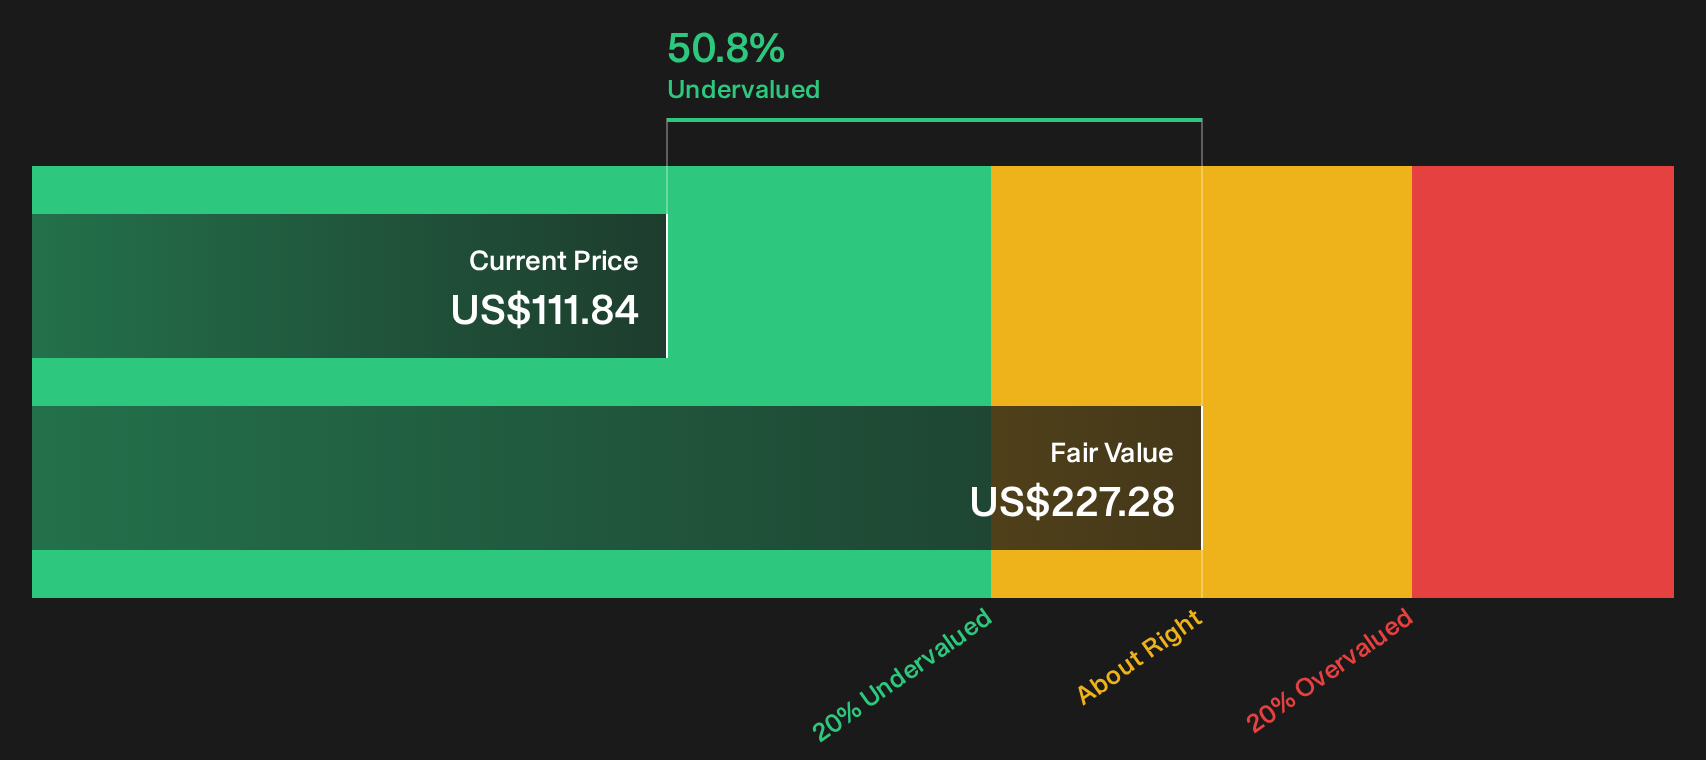
While the fair value narrative pegs Principal Financial Group near US$111 per share and calls it 1% overvalued, the SWS DCF model points in the opposite direction. On that cash flow view, PFG at US$111.84 trades roughly 51% below an estimated value of US$227.28. Which lens should carry more weight for you?
Our DCF uses explicit cash flow assumptions, a discount rate and long term growth inputs that can differ meaningfully from analyst multiples. It can be useful to see how those mechanics drive such a wide gap. Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Principal Financial Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 26 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Seeing mixed signals around Principal Financial Group and its value case is normal, especially after a strong run into fresh results. Act while the data is fresh and pressure test the optimism by weighing the 4 key rewards
Looking for more Principal Financial Group style investment ideas?
If Principal Financial Group has sharpened your focus, do not stop here. Broaden your watchlist now so you are not late to the next move.
- Target resilient value by scanning companies that combine quality fundamentals with attractive pricing in the 26 high quality undervalued stocks.
- Strengthen portfolio stability by reviewing a list of solid balance sheet and fundamentals (24 results) that can help anchor returns when conditions get tougher.
- Spot early opportunities by filtering for 19 high quality undiscovered gems before wider attention arrives.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com