


- Westgold Resources reported that the Beta Hunt underground mine in Kambalda reached a record annualised 2Mtpa mining rate in September 2026, after removing legacy infrastructure constraints and commissioning an interim primary ventilation system ahead of schedule.
- The upgrade program at Beta Hunt, including new ventilation, renewed water reticulation and broader underground services, turns a previously infrastructure limited orebody into a more modern operation that can better match its scale and mineralised strike length.
- We will now look at how Westgold Resources' investment narrative could be influenced by Beta Hunt reaching a 2Mtpa mining rate.
Scan how Westgold Resources compares with other producers pushing volumes higher by reviewing the hand-picked 35 elite gold producer stocks, which are also leaning on scale and infrastructure upgrades.
Westgold Resources Investment Narrative Recap
Owning Westgold Resources means believing the heavy investment in mines like Beta Hunt and Higginsville can support higher, more consistent throughput while bringing AISC under control. The shift to a 2Mtpa platform at Beta Hunt speaks directly to that thesis. In the short term, the key swing factor remains whether higher volumes can stabilise operating performance without fresh bottlenecks.
The biggest risk right now is cost pressure. Q1 FY27 production of 98.4koz at AISC of A$2,912/oz shows the company is not yet operating at the lower end of its own cost guidance. Any delay in converting the new infrastructure into smoother output could keep margins tight and make the growth story harder to sustain.
The operating results to 30 September 2026 are the most relevant announcement here. Beta Hunt hitting a 2Mtpa run rate coincides with group quarterly output broadly flat on Q4 FY26 and unit costs still elevated. For an investor, that places the spotlight on execution rather than new promises.
Gold volumes are already near the 100koz a quarter mark, so the near term catalyst is whether the new ventilation, water reticulation and mine services at Beta Hunt help Westgold Resources run that level more reliably while working AISC down. If the upcoming Q1 2027 earnings call shows cleaner operating trends at Kambalda, it would feed directly into that narrative.
What The Analyst Framework Implies For Westgold Resources
In the analyst playbook, Westgold Resources is treated as a volume and margin story that stretches well beyond the Beta Hunt ventilation upgrade. Consensus models assume revenue can rise at about 5.9% a year for the next three years, while profit margins move from 18.2% today to 30.6% by around 2029. That combination ties the current heavy spend on mines and processing hubs directly to higher profitability rather than just bigger output.
The earnings bridge is sizable. Forecast consensus points to A$887.3 million of earnings by 2029 compared with A$443.5 million today, which is roughly a 2x step up. Analysts differ on the exact landing point, with estimates running from A$621.3 million through to A$1.1b, so the range of possible outcomes is wide even before factoring in gold price swings, grade variation or cost surprises across the Western Australian portfolio.
Westgold Resources' narrative projects A$2.9b revenue and A$887.3 million earnings by 2029. This requires 5.9% yearly revenue growth and roughly a 2x earnings increase from A$443.5 million.
Those earnings expectations link directly into how the stock is framed on valuation screens. At the current consensus, analysts are effectively asking you to treat Westgold Resources as a miner that trades on a P/E of about 9.8x those potential 2029 earnings, compared with 10.7x today and 11.3x cited for the broader Australian metals and mining group. The story is that higher throughput from hubs like Higginsville and the integrated Karora assets supports bigger profits without needing a premium multiple.
Revenue forecasts sit at A$2.9b by 2029, paired with the A$887.3 million earnings outlook, so the implied profit margin in these models is meaningfully above the current 18.2% level. That margin lift does a lot of heavy lifting for the projected fair value even before any discussion of dividends or buybacks, given analysts also assume the share count declines by about 0.54% a year over the next three years as Westgold Resources retires stock.
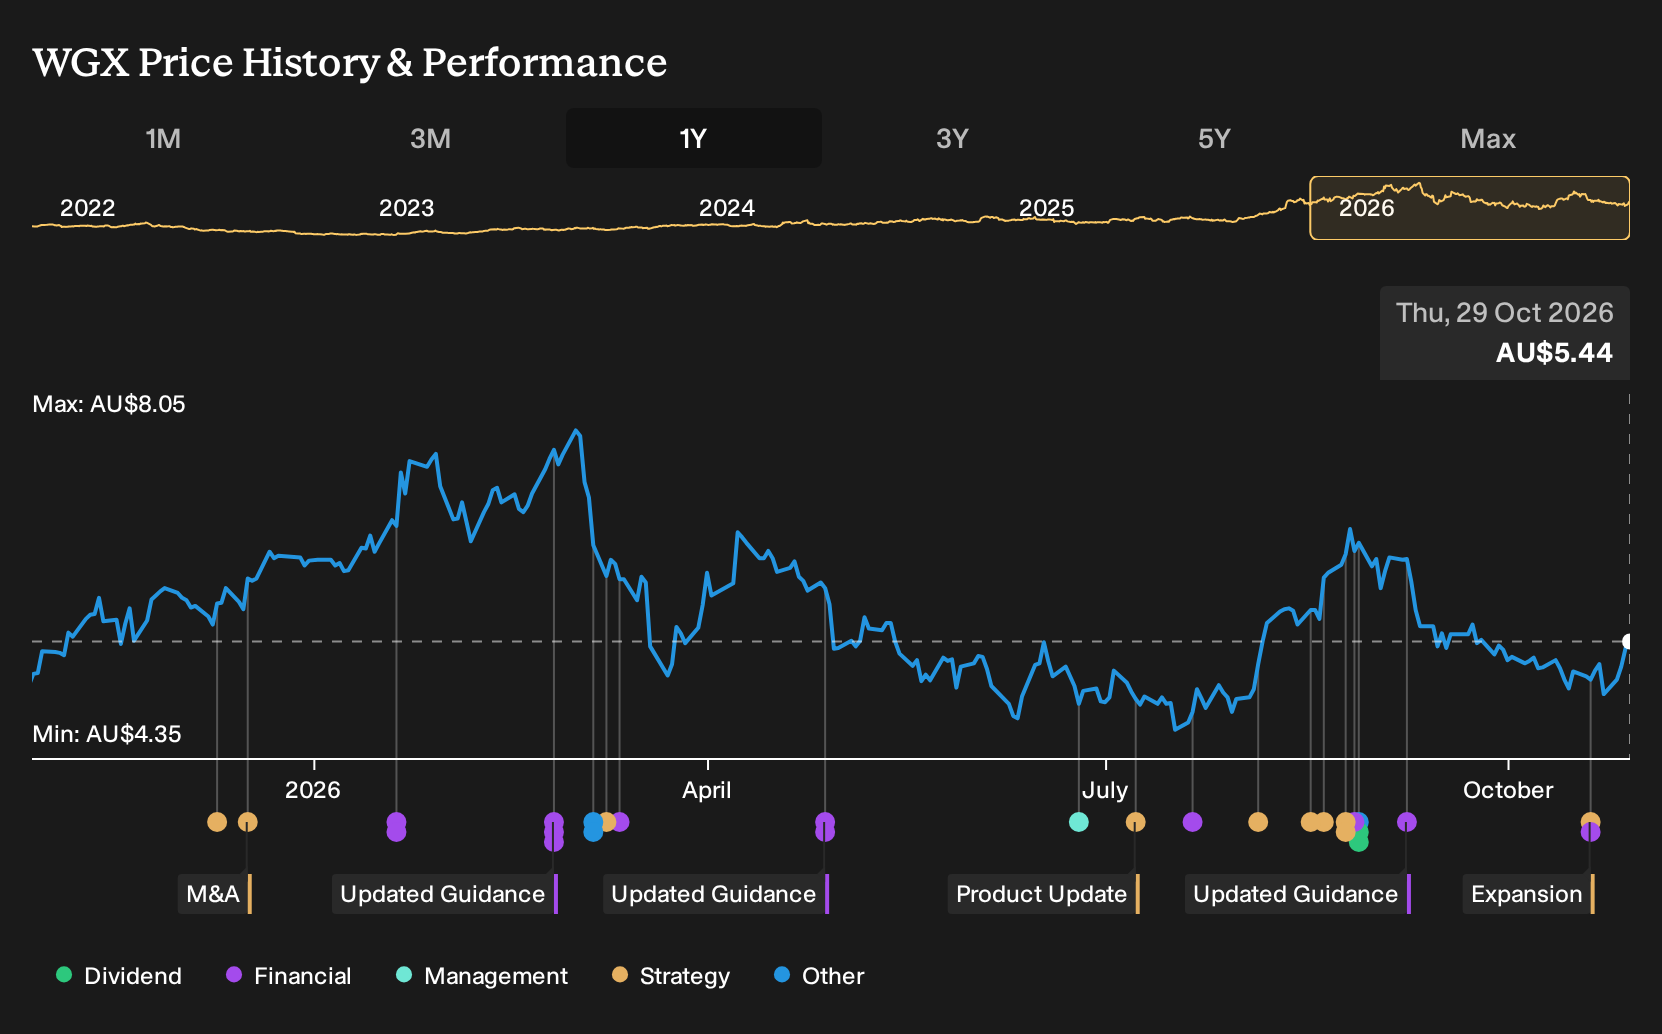
Against a share price of A$5.07, the consensus target of A$7.37 is framed as 31.2% higher. That gap is not a prediction; it is just the output you get if the market eventually prices the stock on 9.8x earnings once revenue reaches about A$2.9b and margins track closer to 30.6%. For you as an investor, the more useful takeaway is which parts of that equation feel realistic given what you know about Beta Hunt, Higginsville and the broader operating track record.
Uncover why Westgold Resources' fair value indicates a 35% potential upside to its current price. This reflects a valuation gap that could narrow quickly if sentiment shifts.
Exploring Other Perspectives
One alternate view on Westgold Resources focuses on reserve conversion risk rather than Beta Hunt’s new 2Mtpa platform. The most cautious analysts previously pencilled in A$2.5b of revenue and about A$520.2m of earnings by 2029, which is far below the consensus bridge. That more guarded script could shift once this latest infrastructure news is fully digested.
Explore 4 other Westgold Resources fair value estimates, including one that suggests it could be worth just A$7.35!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Westgold Resources research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Westgold Resources. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Westgold Resources' overall financial health at a glance.
Looking For More Investment Ideas Beyond Westgold Resources?
Once you have a view on Westgold Resources, it can help to compare that thesis with other opportunities that share similar qualities on cash flows, balance sheets or income potential. The Simply Wall St Screener lets you do that quickly by filtering for financial traits that fit the way you like to invest.
- If you care most about paying a fair price for strong fundamentals, consider screening for companies using the 2 high quality undervalued stocks that currently line up on quality and valuation.
- For readers who put capital preservation first, focus on businesses that score well on financial resilience by starting with the 6 resilient stocks with low risk scores and see which tickers match your comfort level.
- If you want to widen the opportunity set beyond well covered stocks, scan the 15 high quality undiscovered gems to spot under-followed companies with promising fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com