


- Agnico Eagle Mines reported third quarter 2026 net income of US$1.35b and basic EPS from continuing operations of US$2.67, with both quarterly and nine month results above the prior year and consensus expectations for earnings and revenue.
- The business reported earnings above analyst expectations over the last four quarters, indicating that current operations and cost control are supporting stronger profitability than analysts had modeled.
- We will look at how Agnico Eagle Mines' investment narrative is shaped by this earnings result and the stronger quarterly profit profile.
Agnico Eagle Mines Investment Narrative Recap
To own Agnico Eagle Mines, you need to be comfortable with a story that leans on low costs, high free cash flow and long life assets across Canada, Finland, Mexico and Australia. The latest quarter delivered US$1.35b in net income and US$2.67 in basic EPS from continuing operations, which supports that profitability story in the near term.
The key short term swing factor remains execution at existing sites while absorbing the Barnat pit issues and keeping safety performance tight. Barnat related volume losses and any further disruptions are the biggest operational threat. This earnings beat helps cushion that risk but does not remove it.
The most relevant data point in this context is the full nine month 2026 result. Management reported net income of US$4.65b versus US$2.94b a year ago, with basic EPS from continuing operations at US$9.25 compared with US$5.85. That is a sizable uplift in earnings power through the first three quarters.
For you as a shareholder, that nine month performance increases Agnico Eagle Mines’ capacity to fund its key projects, absorb Barnat related reserve pressure and keep investing in automation and regional hubs. It also partly offsets analyst expectations for declining earnings over the next three years, while leaving operational and safety risks squarely in focus.
How Agnico Eagle Mines’ earnings profile lines up with sector expectations
Agnico Eagle Mines is now being valued against a fairly tight analyst script that assumes steady earnings and only modest top line expansion. Consensus models build in revenue growth of 1.7% a year over the next three years, with profit margins easing from 40.4% today to 38.8% by 2029 as costs and project spending take a larger share of each dollar of sales.
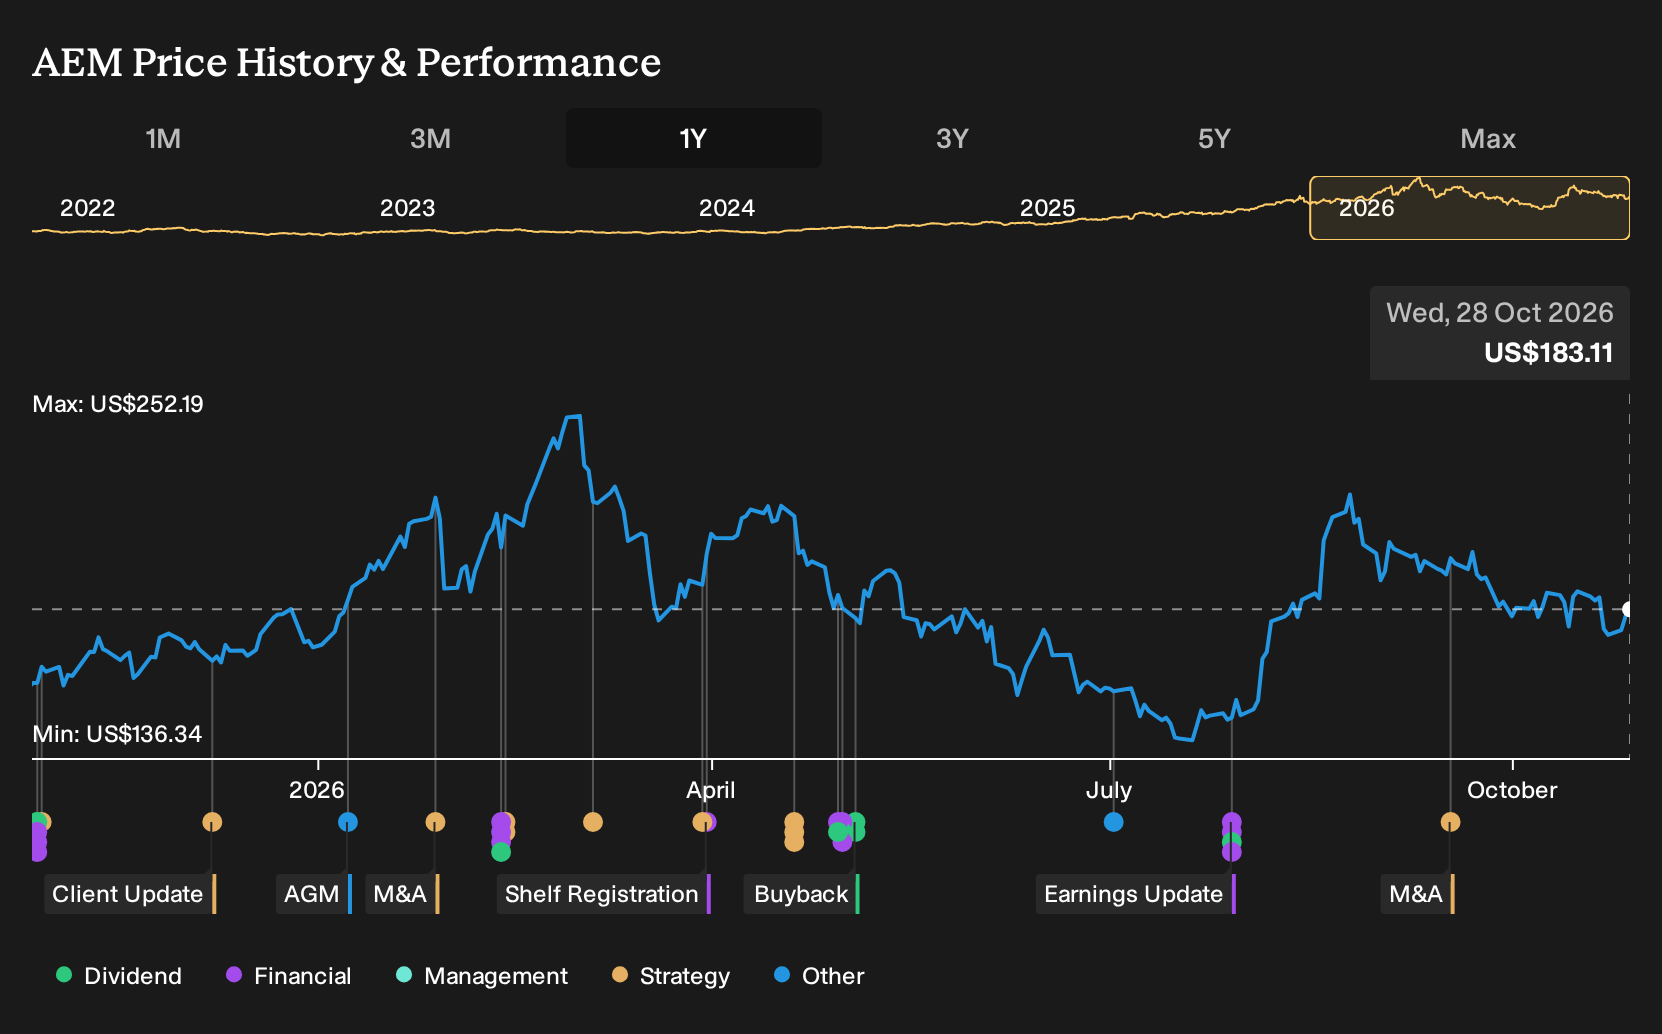
On those numbers, analysts are anchoring on current earnings of US$5.9b and forecast consensus earnings of US$5.9b again in 2029, implying no earnings growth across the period despite the higher revenue base. The key moving part is valuation, not profits. To reach the US$211.37 consensus price target, the stock would need to trade on a P/E of 23.6x those 2029 earnings, up from 15.2x today and above the 18.1x level referenced for the wider US metals and mining group.
The same framework underpins the sector comparison with the CTA_SCREENER_GOLD peer set. While each gold producer faces its own mix of ore body quality, jurisdiction risk and capital needs, the shared debate is whether investors are comfortable paying a P/E multiple above the broader industry for relatively flat earnings and modest revenue growth. For Agnico Eagle Mines, the question becomes whether its lower cost profile, multi country asset base and project pipeline justify that higher earnings multiple relative to the typical gold stock captured by CTA_SCREENER_GOLD.
Agnico Eagle Mines' narrative projects US$15.3b revenue and US$5.9b earnings by 2029. This setup assumes 1.7% yearly revenue growth and earnings staying flat at US$5.9b relative to current earnings.
Uncover why Agnico Eagle Mines' fair value indicates a 15% potential upside to its current price, which could narrow quickly if sentiment catches up.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Agnico Eagle Mines’ project pipeline as a potential upside catalyst. Before this earnings release, that group was penciling in revenue of about US$17.3b and earnings near US$5.7b by 2029, and applying a P/E of 30.2x. That is far more upbeat than consensus. Treat this quarter as a fresh data point and explore how these views might shift.
Explore 6 other Agnico Eagle Mines fair value estimates, including one that suggests as much as 67572% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Agnico Eagle Mines research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Agnico Eagle Mines. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Agnico Eagle Mines' overall financial health at a glance.
Looking for more investment ideas beyond Agnico Eagle Mines?
If Agnico Eagle Mines has sharpened your interest in the sector, it can help to line it up against other opportunities that fit different risk and income profiles. Use the Simply Wall St Screener to build a watchlist that fits how you want your portfolio to behave, not just what is in the headlines today.
- If capital preservation is your priority, start with companies that show resilient balance sheets and steady fundamentals through the list of solid balance sheet and fundamentals (24 results).
- If you are hunting for mispriced opportunities backed by strong underlying numbers, compare Agnico Eagle Mines against a 26 high quality undervalued stocks and see how the risk reward trade off looks across the market.
- If you want ideas that are off most investors’ radar, widen your research with a 19 high quality undiscovered gems that still screen well on quality and fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com