


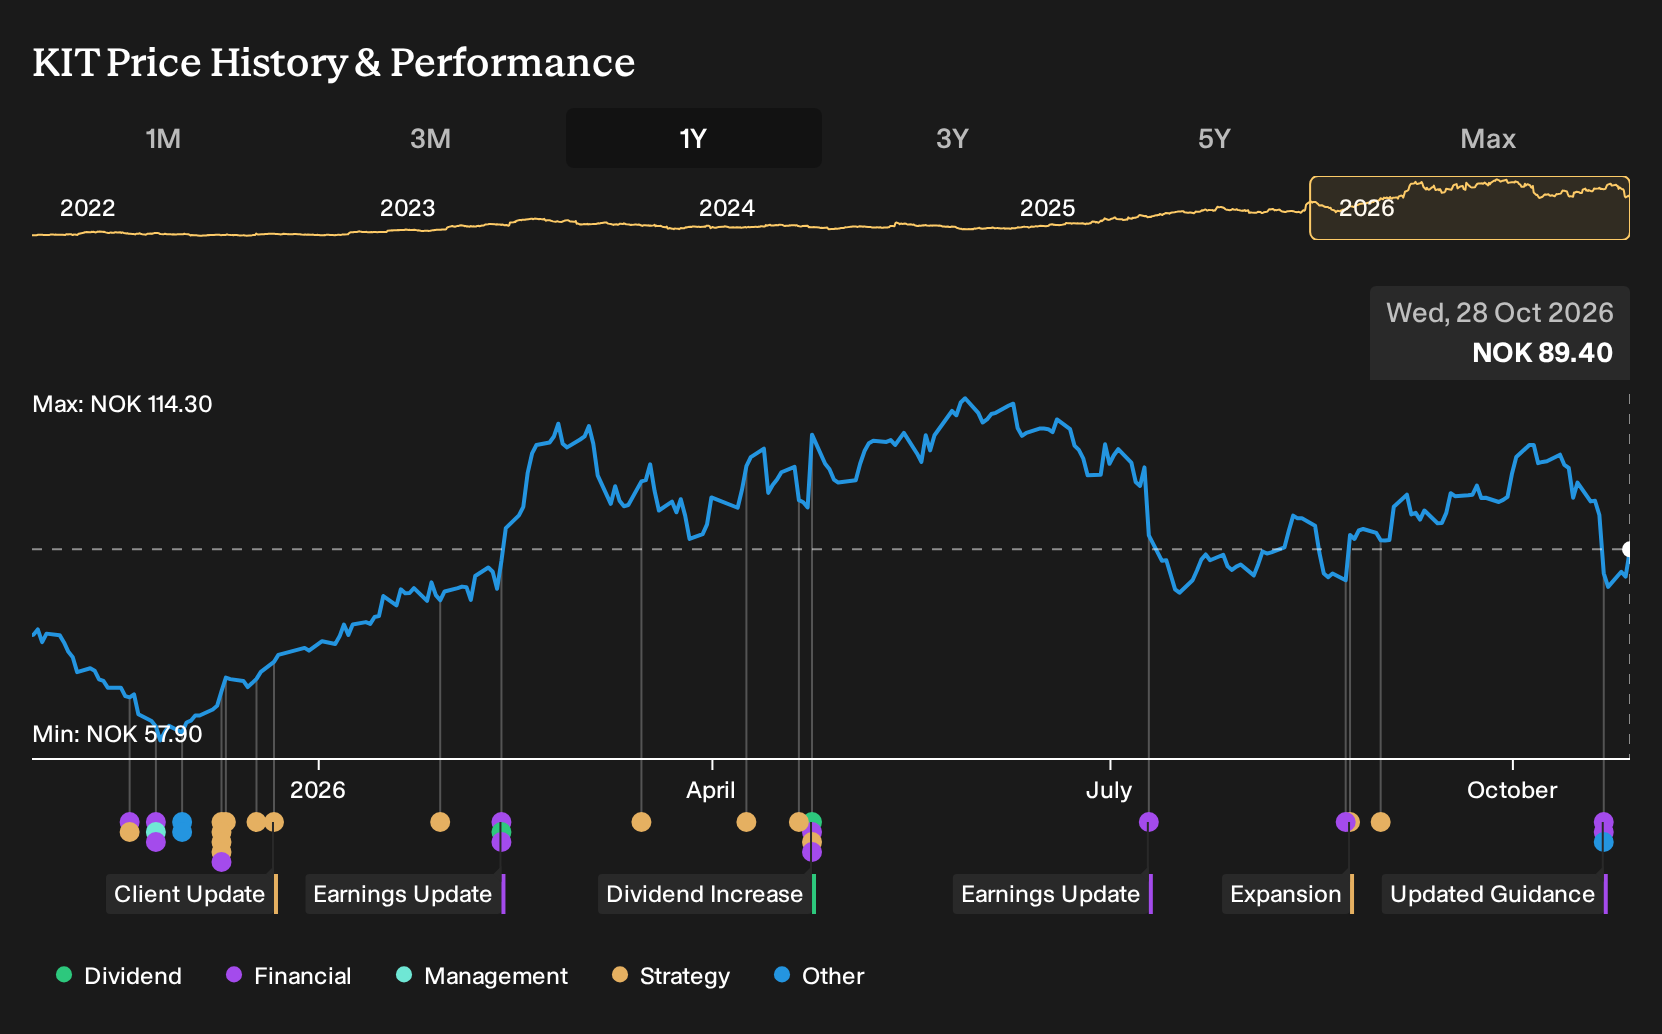
- Kitron reported third quarter 2026 sales of €266.8 million and net income of €17.4 million, with nine month sales of €835.2 million and net income of €58.8 million, and reaffirmed full year 2026 revenue and EBIT guidance.
- The reaffirmed 2026 outlook, alongside higher basic earnings per share from continuing operations, reflects management’s confidence in current demand patterns and execution.
- The focus now shifts to how Kitron’s investment narrative aligns with this reaffirmed 2026 guidance and substantially higher year to date earnings.
Scan beyond Kitron’s reaffirmed guidance and step into a curated field of peers by reviewing our hand picked list of solid balance sheet and fundamentals (202 results) that also pair earnings power with balance sheet strength.
Kitron Investment Narrative Recap
To own Kitron, you need to be comfortable with an electronics manufacturer that leans heavily on a large order backlog in Defense and Aerospace, Electrification and Industry, and is working to turn that backlog into steady earnings. The Q3 2026 report, with higher year to date profit and EPS, supports that conversion story and keeps the operational thesis intact.
The key short term catalyst remains execution on this backlog while new capacity in places like Longum and Horsens is ramped and used efficiently. The biggest risk still sits in working capital swings and tight component supply. The latest results and reaffirmed guidance do not radically change that near term risk balance.
The reaffirmed 2026 revenue and EBIT outlook is the announcement that matters most here. Kitron now expects full year revenue between €1,050 million and €1,150 million, with EBIT of €97 million to €112 million. Keeping that band unchanged after strong nine month figures indicates management sees current demand as broadly aligned with its operating plans.
For you, that ties directly into catalysts around backlog conversion and sector mix. Defense and Aerospace, Electrification and a recovering Industry segment already provide volume, while improved capital efficiency metrics point to an ongoing focus on cash and margins. The main operational watchpoints remain regional profitability gaps, supply chain tightness and how inventory and deposits behave over the coming quarters.
What The Medium Term Kitron Forecasts Assume
Kitron's current analyst narrative rests on relatively punchy growth assumptions. Consensus models point to revenue expanding by 18.5% a year over the next three years, with profit margins moving from 7.1% today to 7.9% by around 2029 as new facilities and backlog conversion feed through the income statement.
On the earnings side, the same forecasts map out a move from €76.0 million in profit today to €140.7 million by 2029. That is an increase of about €64.7 million, which implies earnings would be close to 1.9x current levels if the projections land as expected. For you as an investor, the key question is not whether that number looks attractive in isolation, but whether the order book, sector mix and capacity footprint give enough visibility to that step up in profitability.
The share count assumptions also matter because they shape how much of that profit pool falls to each share. Analysts expect outstanding shares to grow by 7.0% per year over the next three years. That tempers some of the per share upside implied by the earnings bridge and makes it important to focus on earnings per share, not just headline net income, when you think about Kitron's potential return profile.
Kitron's narrative projects €1.8b revenue and €140.7 million earnings by 2029. This implies 18.5% yearly revenue growth and an earnings increase of about €64.7 million from €76.0 million today.
The valuation framework built on these inputs is straightforward. Consensus targets point to Kitron trading on a P/E of 24.5x in 2029 if it delivers €140.7 million of profit, compared with 22.9x today and 21.2x for the broader GB Electronic industry. That multiple uplift assumes investors continue to pay a premium for the business once it has scaled into the higher revenue and margin profile implied by the forecasts.
Analysts have translated these earnings and multiple assumptions into a consensus price target of NOK105.97, with a spread between NOK89.63 at the low end and NOK133.93 at the high end. Against a current share price of NOK83.2, that central target sits 21.5% higher. Rather than treating those figures as a promise, use them as a reference point to test your own view on what level of revenue growth, margin expansion and earnings power feels realistic for Kitron over the next few years.
Uncover why Kitron's fair value indicates a 19% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view focuses on Kitron’s cash generation rather than its backlog. The most bearish analysts were working with around €1.7b revenue and €133.5 million earnings by 2029 before this Q3 report, and a price target near NOK89.88. That more cautious stance assumes tighter cash flow and margins, so use it as a counterweight and explore how these opinions might shift after the latest guidance.
Explore 3 other Kitron fair value estimates, including one that suggests it could be worth just NOK89.88.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Kitron research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Kitron. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kitron's overall financial health at a glance.
Looking for more investment ideas beyond Kitron?
Kitron may be the focus today, but your portfolio benefits when you cast the net wider and line up other companies with financial profiles that suit your own risk and return preferences.
- If you want potential value combined with quality fundamentals, start by scanning our curated set of 192 high quality undervalued stocks that already clear a cash flow and balance sheet quality bar.
- If capital preservation matters most to you, filter for resilience first by running through a tailored 229 resilient stocks with low risk scores that score well on financial strength and risk metrics.
- If you are hunting for underfollowed opportunities, broaden your watchlist with a focused 610 high quality undiscovered gems that pair solid fundamentals with lower investor attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com