


Kirby (KEX) posted third quarter 2026 results, reporting revenue of US$977.21 million and earnings per share of US$2.09. The company also issued tighter full-year guidance indicating expected EPS growth in the range of 10% to 15%.
The upbeat Q3 report and tighter full year guidance arrived alongside a strong run in Kirby’s shares, with a 1 month share price return of 11.0% and a year to date share price gain of 30.54%, suggesting that momentum has been building. At the same time, investors who held on longer have seen a 44.64% 1 year total shareholder return and a 153.64% 5 year total shareholder return, which points to a story that is being shaped over years rather than just a single earnings print.
Scan for other marine and transport operators showing similar earnings momentum by reviewing our hand picked 26 high quality undervalued stocks along with Kirby's latest numbers.
Kirby now appears to be a high quality operator with strong recent execution, and its share price has sprinted ahead. The real test is whether that recent enthusiasm still leaves room for value.
Most Popular Narrative: 12% Undervalued
Kirby closed at $146.07, while the most followed narrative pegs fair value closer to $166.17 based on a $4.3b revenue trajectory and a 7.57% discount rate. That gap rests on a view that tight barge capacity and a growing power generation backlog can keep earnings power building.
Supply constraints and industry-wide aging of the barge fleet are restraining new capacity growth, with industry inland barge construction around 60 to 70 units per year and newbuild returns still about 40% away from justified economics. This supports limited vessel availability, firmer pricing and the potential for higher Marine Transportation revenue and net margins.
See why 12 investors see Kirby as 12% undervalued.
Result: Fair Value of $166.17 (UNDERVALUED)
Still, the Kirby narrative can be knocked off course if medical cost inflation keeps squeezing margins or if weakness in oil and gas related services lingers longer than expected.
Find out about the key risks to this Kirby narrative.
Another View on Kirby’s Valuation
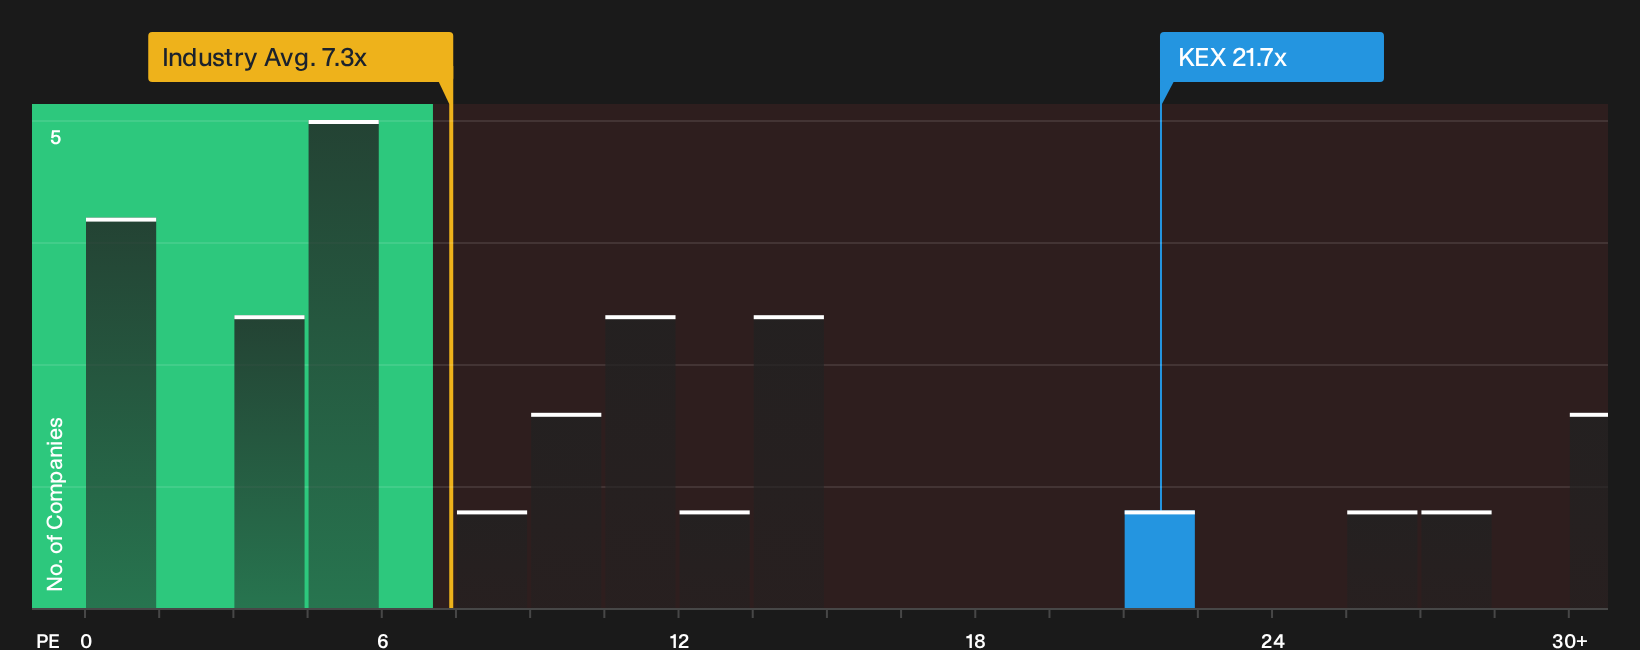
On the earnings narrative, Kirby screens as undervalued. On simple pricing, the picture is tougher. The stock trades on a P/E of 21.7x compared with 7.2x for the US Shipping industry and 14.4x for its peer group, while the fair ratio is 16.6x. That gap points to investors already paying up for quality, so the question becomes how much of the story is already in the price.
To pressure test that view against the earnings narrative, take a closer look at how the current price compares with the fair ratio and peer valuations in our breakdown. Then judge whether the premium still feels justified for Kirby. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling the optimism in Kirby's story but not fully convinced yet? Act quickly, review the data for yourself, and weigh those potential upsides in our 3 key rewards.
Looking for more investment ideas beyond Kirby?
If Kirby has your attention, do not stop there. Broaden your watchlist with a few focused screens that surface different types of opportunities you might otherwise miss.
- Target resilient balance sheets by scanning a list of solid balance sheet and fundamentals (24 results) that filters for companies with financial footing designed to handle tougher conditions.
- Chase potential mispricings by reviewing a 19 high quality undiscovered gems that highlights quality businesses the broader market may not be focused on yet.
- Prioritise stability and capital protection by reviewing a 32 resilient stocks with low risk scores that focuses on companies with lower assessed risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com