


Molson Coors Beverage has seen its share price slip over recent years, even with some shorter term rebounds, which puts fresh focus on what investors are really paying for its sales today. With the stock moving but the business still driven by a mature beverage portfolio, the open question is how well the current price lines up with the revenue it generates.
- Over the past 3 years the share price has fallen 24.9%, which raises the issue of whether the current valuation is now more tightly linked to Molson Coors Beverage's underlying sales power.
- The business relies on established beer and beverage brands, so the key lever for valuation can be how efficiently those brands convert existing shelf space and consumer loyalty into steady sales rather than rapid volume expansion.
- There is a second opinion on Molson Coors Beverage worth weighing. See what analysts think Molson Coors Beverage's shares could be worth.
The issue now is whether Molson Coors Beverage's current share price is appropriately supported by the scale and quality of its sales base.
If you are questioning whether Molson Coors Beverage at US$39.24 fairly reflects its sales, it can help to compare it with a wider group of 26 high quality undervalued stocks
Is Molson Coors Beverage Still Cheap on Sales?
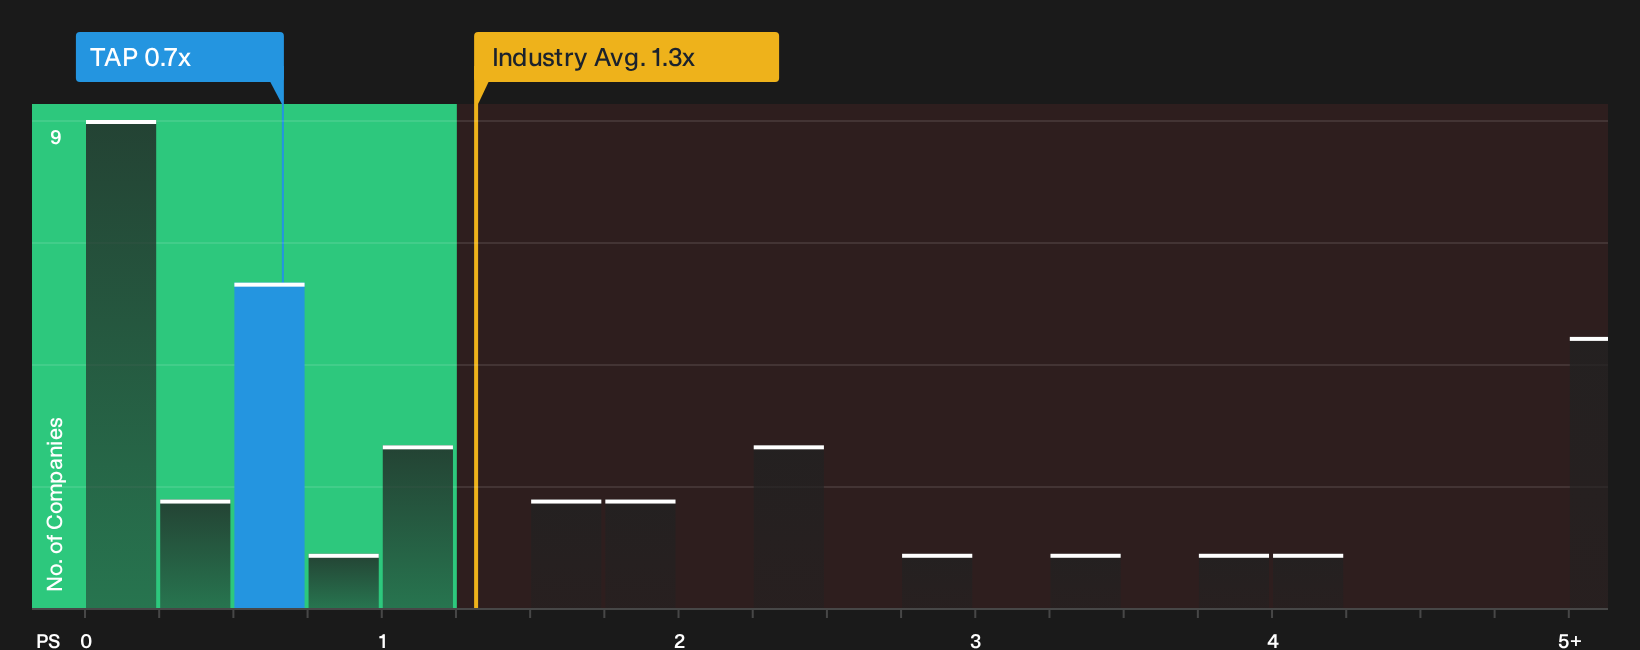
P/S works well for Molson Coors Beverage because investors are often weighing what they pay for each dollar of sales from its established brands. On this metric, the stock trades at about 0.7x P/S, which is lower than the wider beverage industry average of roughly 1.3x and also below a broader peer group closer to 1.8x.
The Fair Ratio model, which adjusts the benchmark multiple for Molson Coors Beverage’s specific mix of growth prospects, profitability, size and risk, points to a higher P/S than where the shares change hands today. That places the current 0.7x P/S in undervalued territory on this framework. Anyone looking at the stock is effectively being asked whether the underlying sales quality justifies that discount or not. Explore the numbers behind Molson Coors Beverage's P/S valuation.
The Molson Coors Beverage Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Molson Coors Beverage pick up where the P/S puzzle leaves off and explain which combinations of future growth, profit margins and earnings would need to occur for the stock to look meaningfully higher or lower than today’s price. Each narrative links its number to a clear view on how Molson Coors Beverage's prospects and risks might change, giving you a reference point to revisit as fresh information becomes available.
The Molson Coors Beverage community splits between those who see a discounted turnaround story and those who think recent pressure already stretches the valuation.
Bull case: 10% undervalued
"Ongoing balance sheet improvement, with net debt to EBITDA at 2.53x, alongside a US$2.35b remaining share repurchase authorisation after buying back 15.3% of Class B shares..."
Discover why this Narrative puts Molson Coors Beverage at 10% undervalued.
Bear case: 19% overvalued
"Although Molson Coors is pushing Horizon 2030 moves such as Monaco, Topo Chico Hard and Fever-Tree to reshape the portfolio toward beyond beer and premium offerings, the recent 3.6% constant currency decline in net sales revenue and 27.8% fall in underlying pretax income show that these newer brands have not yet offset pressure in core beer..."
Explore why this Narrative puts Molson Coors Beverage at 19% overvalued.
An unresolved piece of the Molson Coors Beverage puzzle
Before you put too much weight on any price to sales comparison, it helps to ask who is steering Molson Coors Beverage, how their rewards line up with your interests, and what that actually looks like in practice. See who runs Molson Coors Beverage and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com