


- Super Micro Computer recently reported preliminary fiscal Q1 2027 revenue guidance of US$18.5b to US$19.5b, above its prior outlook, alongside a flurry of AI-focused product launches and alliances spanning NVIDIA Vera CPU racks, Nokia AI-RAN deployments, and Nutanix powered private AI infrastructure.
- The combination of higher expected sales tied to AI platforms and deeper roles inside AI factories, radio networks, and private inference stacks suggests that Super Micro Computer is increasingly competing to supply larger portions of full data center builds rather than just individual servers.
- We will now look at how Super Micro Computer's investment narrative may be affected by this stronger AI driven revenue guidance.
Scan how Super Micro Computer’s AI factory push compares with other hardware builders pressing into full-stack infrastructure by running through the curated 54 AI infrastructure stocks in the same space.
Super Micro Computer Investment Narrative Recap
To own Super Micro Computer, you need to believe the build out of full AI infrastructure, not just GPU servers, continues to pull buyers toward its rack scale DCBBS model. The raised fiscal Q1 2027 revenue outlook tied to AI platforms reinforces that theme and keeps execution on these large deployments as the key short term catalyst.
The biggest near term risk still sits in deal mix, working capital, and dependence on very large AI orders. Higher guidance does not change exposure to margin resets, inventory heavy projects, or any future pullback from a small group of multibillion dollar customers, so earnings quality and cash conversion remain important to watch.
The NVIDIA Vera CPU rack launch looks most relevant to the current AI factory story because it extends Super Micro Computer deeper into the CPU side of agentic AI and reinforcement learning workflows. By pairing Vera CPU racks with Vera Rubin NVL72 GPU systems under the DCBBS umbrella, the business is pitching more of the rack as a standardized, liquid cooled package.
That push matters for catalysts because it directly ties to higher value configurations and potentially supports demand behind the upgraded Q1 revenue guidance. It also introduces fresh execution risk around liquid cooling at scale, power architectures such as 800 VDC racks, and secure agent governance with NVIDIA OpenShell and Sentry, where deployment complexity can affect timelines and profitability.
Super Micro Computer Analyst Assumptions and Valuation Check
Analysts framing Super Micro Computer around the current AI factory push are underwriting a long runway of expansion. The consensus view points to revenue climbing at 33.6% a year over the next three years, even as profit margins are expected to compress from 5.6% today to 3.9% by around 2029. On that path, earnings are projected to move from US$2.2b today to US$3.7b by 2029, with a wide band of opinion that runs from US$2.9b at the low end to US$4.7b at the high end. Those projections also build in share count growth of 7% a year, which matters for how much of that profit pool ultimately belongs to each share you might own.
Valuation work coming out of this earnings deck translates those inputs into a 2029 target profile of US$93.1b in revenue and US$3.7b in earnings. To line that up with today’s price targets, analysts apply a 12.5x P/E on the 2029 earnings estimate, compared with about 10.6x today and a current US Tech sector multiple of 24.5x. With the stock at US$35.57 and the consensus target at US$43.27, the implied upside in those models sits at 17.8%, framed against a discount rate of roughly 9.6% to bring future cash flows back to present value. That spread essentially reflects the market’s willingness to pay now for Super Micro Computer’s potential to convert AI rack wins into durable earnings power.
Super Micro Computer's current analyst narrative points to forecast 2029 revenue of US$93.1b and earnings of US$3.7b, built on assumed yearly revenue growth of 33.6% and an earnings increase of about US$1.5b from US$2.2b today.
Uncover why Super Micro Computer's fair value indicates a 21% potential upside to its current price before the market closes that gap.
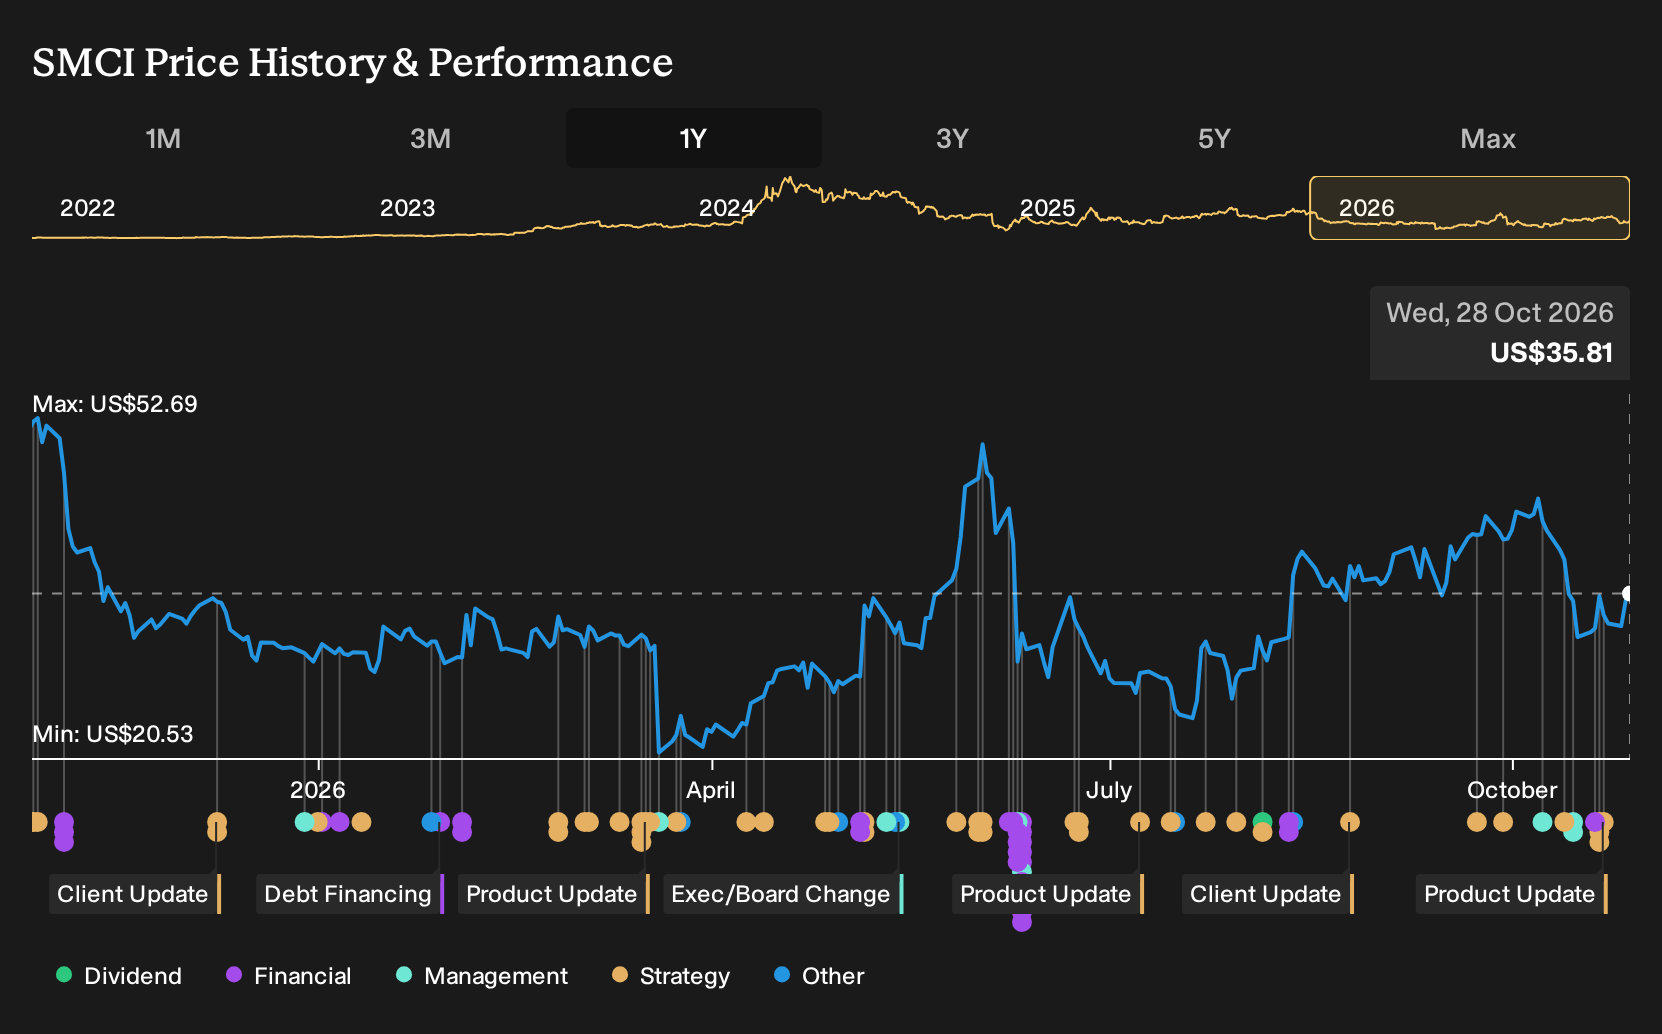
Exploring Other Perspectives
One bullish twist you might explore is how some analysts leaned heavily on Super Micro Computer’s AI order book even before this Vera CPU rack news. The most optimistic group was already penciling in US$112.3b of 2029 revenue and US$4.2b of earnings. That is far above consensus and shows how far opinions can spread. Use this announcement as a prompt to compare those more aggressive forecasts with your own expectations and decide which story feels more realistic.
Explore 9 other Super Micro Computer fair value estimates, including one that suggests potential upside of up to 169% from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider relying on your own analysis and judgment.
- A great starting point for your Super Micro Computer research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Super Micro Computer. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Super Micro Computer's overall financial health at a glance.
Looking for more Super Micro Computer investment ideas?
If this Super Micro Computer story has sharpened your thinking, you can widen the opportunity set by scanning other stocks through the Simply Wall St screener and seeing how their fundamentals compare.
- For investors who want quality and value in the same place, start with companies that combine stronger balance sheets and attractive pricing through the 26 high quality undervalued stocks.
- If capital preservation matters just as much as upside potential, focus on businesses with sturdier financial profiles by reviewing the 32 resilient stocks with low risk scores.
- When steady income is a priority, look for payers with higher yields supported by fundamentals with the help of the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com