


AI related investment has become a key driver of US economic growth, and a large share of that computing power depends on reliable medical data, diagnostics and drug pipelines. As more digital infrastructure is built, the healthcare sector tends to benefit from better tools, not just bigger budgets. That is where a group of robust US healthcare leaders comes in. This article highlights three stocks from that group that may merit a closer look.
The three healthcare stocks that follow are only a sample, and the broader screen surfaced 36 more US listed companies with equally compelling stories that are not covered below.
If you want to quickly identify potential high quality healthcare opportunities tailored to your own risk and time horizon, head straight to the Best Healthcare Stocks screener to filter and analyze the full set of candidates.
GeneDx Holdings (WGS)
GeneDx Holdings brings genomic testing and AI driven analysis directly into frontline healthcare, giving pediatric specialists and rare disease teams a clearer read on complex cases that traditional diagnostics often miss.
GeneDx focuses on whole exome and whole genome sequencing for pediatric and rare diseases, alongside data and AI based interpretation platforms that support hereditary risk and cancer testing. Most revenue comes from segment adjustment services at about US$423 million, with a smaller contribution from Fabric Genomics and legacy Sema4 at roughly US$31 million, all generated in the United States. The business has a market cap of about US$1.9 billion.
Management is prioritizing payer coverage and AI driven revenue cycle tools to address the gap between current collection rates around the low 30% range and the longer term ~70% target. However, the persistence of roughly 32% outpatient genome collections through Q2 2026 indicates that any improvement in net collections and earnings may occur more slowly than the volume growth in tests.
This raises the question of what could happen if that pressure on how much cash GeneDx ultimately keeps from each test changes more quickly than the market currently anticipates.
If that cash conversion gap closes faster than expected, the full narrative for GeneDx Holdings explains how GeneDx could see that shift accelerate sentiment and reshape the risk profile.

Axogen (AXGN)
Axogen focuses on peripheral nerve repair, which fits neatly with the Best Healthcare Stocks theme by turning complex reconstructive surgery needs into a focused medical device and biologic portfolio that hospitals and surgeons can routinely use in operating rooms.
Axogen generates all its revenue from peripheral nerve repair products and services, reporting about US$251 million from this segment, and carries a market value close to US$2.2b.
Axogen gives surgeons tools to repair damaged nerves rather than relying on traditional grafts alone, which is the kind of targeted medical technology this screener aims to surface.
Upcoming FDA Biologics License Application (BLA) approval for Avance Nerve Graft in September 2025 is described by the company as a potential path to secure 12 years of market exclusivity and establish Avance as the only biologic with this indication, which the company suggests could influence pricing power, limit biosimilar competition, and affect both gross margin and long-term earnings visibility.
The central question now is how Axogen’s growth plans might change if assumptions about future demand and reimbursement were to shift.
That hinges on whether Axogen converts this clinical opportunity into durable economics. The full narrative for Axogen unpacks how growth, pricing and risk could be decoupling under the surface.

Jazz Pharmaceuticals (JAZZ)
Jazz Pharmaceuticals leans into the Best Healthcare Stocks theme through a focused mix of sleep, epilepsy, and cancer treatments that are already in doctors’ hands, while late stage oncology and neurology projects aim to extend that specialist footprint.
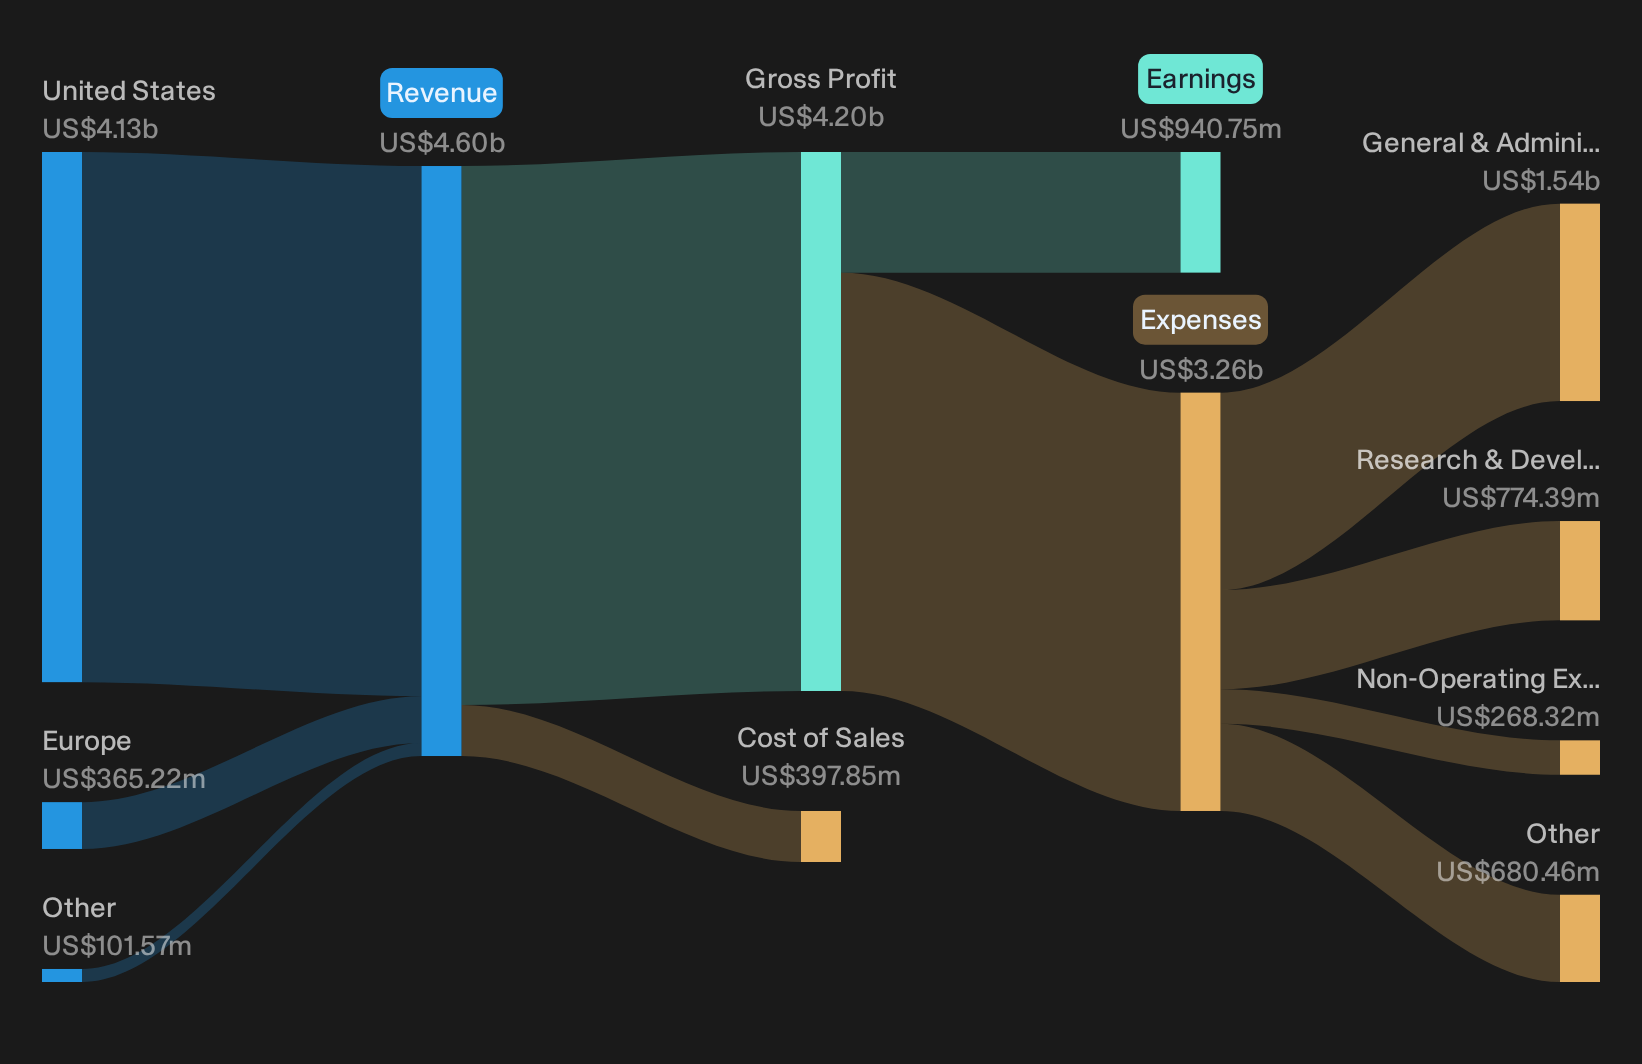
Jazz Pharmaceuticals generated about US$4.6b from pharmaceutical products worldwide, with most sales tied to therapies for sleep disorders, severe seizures, and cancer, and carries a market value of roughly US$13.4b.
For this screener, Jazz Pharmaceuticals matters because it blends established specialty drugs with a maturing late stage pipeline, giving you exposure to both current cash flows and potential new treatment areas as its oncology and neurology franchises evolve.
Expansion of Ziihera across additional HER2 driven tumors, including biliary tract, colorectal, lung and early or metastatic breast cancer, following the raised US$3b to US$5b peak sales outlook, has been cited as a factor that could add new oncology revenue streams and affect long term earnings power.
The real swing factor is how one unresolved shift in its product mix affects the balance between high cost R&D and future profitability.
If that product mix shift is what really moves the needle, the full narrative for Jazz Pharmaceuticals maps how Jazz Pharmaceuticals’ oncology bets, cash flows and risks could be decoupling.
Seeking Alternatives Before Momentum Flies
Fresh ideas move first, and the fastest gains often come before the crowd catches on. Track breakout momentum while it matters, stay ahead of dropping sentiment, act now.
- Spot resilient compounders early and sift through a curated 32 resilient stocks with low risk scores before the market fully catches up to their balance sheet strength and steadier return profile.
- Ride the next wave of automation by scanning the hand picked 96 robotics and automation stocks while these operators are still building momentum under the radar for now.
- Position ahead of the AI build out and comb through a focused 54 AI infrastructure stocks before capital flows crowd into the same limited group of tickers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com