


Swedbank (OM:SWED A) has just put fresh numbers on the table. Third quarter and nine month results are out, giving you new detail on net interest income, earnings and per share profitability.
Against this backdrop, Swedbank’s share price at SEK391.3 sits on top of a 20.25% year to date share price return. The 1 year total shareholder return of 48.63% and 5 year total shareholder return of 201.88% point to momentum that has been building over a longer stretch, with the latest earnings release and the recently completed SEK642.99m buyback tranche adding fresh context to that performance and to how investors weigh future growth potential against legal and operational risks.
Scan how Swedbank’s fresh earnings and buyback move compare with other banks showing strong momentum and robust fundamentals in our hand picked list of solid balance sheet and fundamentals (202 results)
Swedbank now trades only slightly below the average analyst target, while implied fair value estimates sit far lower. Where does that leave upside, if any, after this latest earnings release and buyback?
Most Popular Narrative: 4% Undervalued
Against Swedbank’s last close at SEK391.3, the most followed narrative points to a fair value of roughly SEK407.9, leaving a modest valuation gap that now leans heavily on cost control and capital flexibility.
The main thing that has to go right is that Swedbank delivers the targeted SEK 1 billion lower annual cost run-rate by end 2028, while managing revenue headwinds from the planned Entercard back-book and PayEx divestments and ongoing regulatory capital demands.
The current valuation implies that Swedbank is fairly valued, with the share price already reflecting a stronger Baltic growth engine, a leaner operating model and the capacity for higher capital returns following the completion of legacy US investigations.
See why 22 investors see Swedbank as 4% undervalued.
Result: Fair Value of SEK407.94 (UNDERVALUED)
Still, the Swedbank narrative could be knocked off course if the Entercard and PayEx exits pull out income faster than cost cuts and capital buffers can adjust.
Find out about the key risks to this Swedbank narrative.
Another View On Swedbank’s Valuation
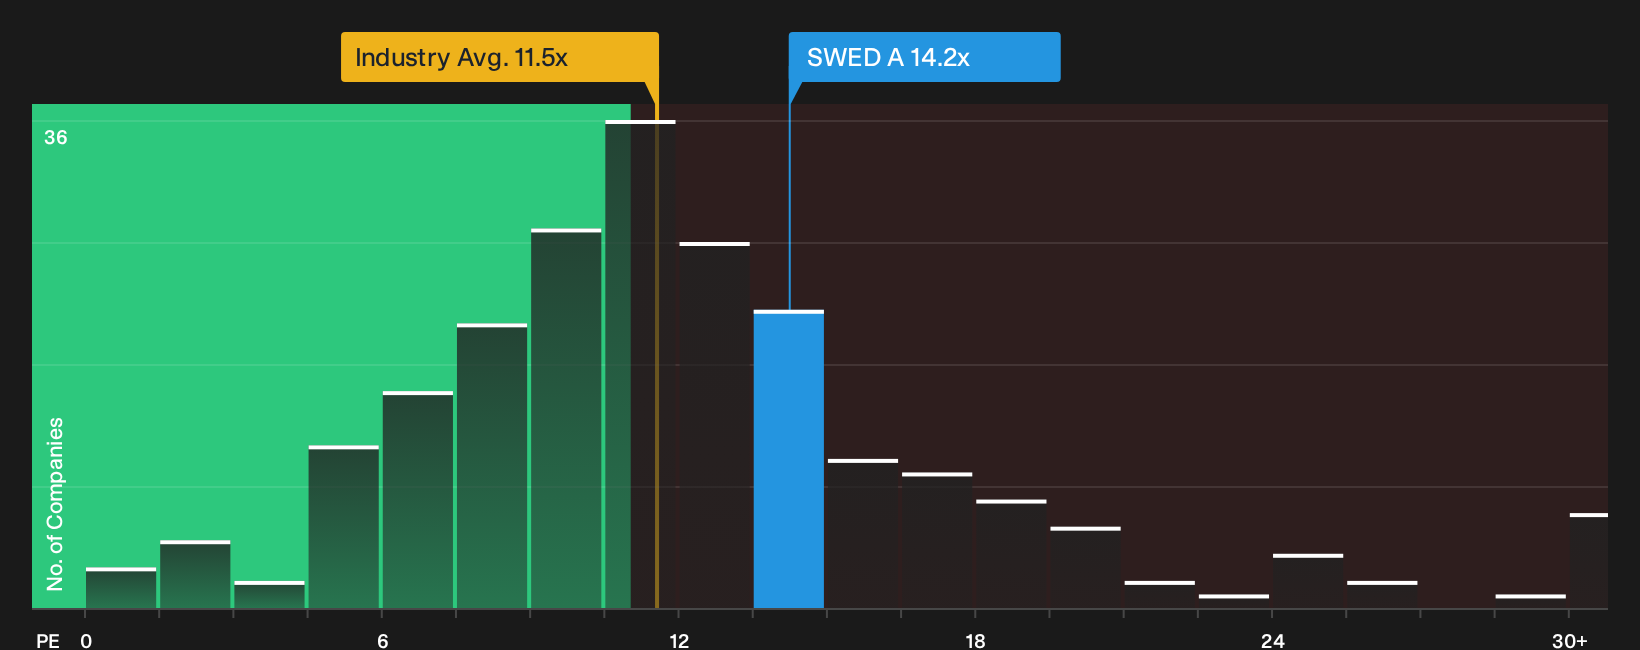
That 4% gap to fair value looks modest once you switch lens. On a P/E of 14.2x, Swedbank trades richer than European banks at 11.7x, its peer group at 11.9x, and even above its own 13x fair ratio. That premium adds valuation risk if the story slips.
For a closer look at how the numbers stack up against this price, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty in this Swedbank story appears balanced between potential benefits and risks, so move quickly to review the full picture for yourself with 2 key rewards and 3 important warning signs
Looking for more investment ideas beyond Swedbank?
If Swedbank has sharpened your focus on quality and valuation, do not stop here. Broaden your watchlist now so you are not late to the next opportunity.
- Target resilient balance sheets and steady fundamentals by screening a list of solid balance sheet and fundamentals (202 results) that can help anchor your portfolio.
- Hunt for quality at a discount by using a curated 190 high quality undervalued stocks that filters for strong businesses priced below their assessed worth.
- Build a steadier income stream by focusing on a 225 dividend fortresses designed to spotlight higher yielding payers with robust profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com