


Symbotic has seen its share price swing sharply in recent years, and the scale of those moves now puts a spotlight on what investors are paying for its sales. With the stock recently closing at US$38.97, the key issue is whether that price tag lines up with the revenue the business is currently generating.
- Over the past 5 years the stock has gained about 288.1%, which puts a lot of weight on whether today's valuation can still be anchored to its underlying sales base.
- Fresh attention on automation in security services, including robotics in projects tied to large investors like SoftBank, can shape how markets think about Symbotic's potential revenue scale and the timing of any margin improvement from its warehouse systems.
- Your read on Symbotic is one view; the desks covering it have another. See what analysts think Symbotic's shares could be worth.
For investors, the debate is whether Symbotic's current share price is adequately backed by its sales when compared with the Fair Ratio benchmark.
If you are weighing Symbotic against other automation and robotics plays, it can help to compare it with 96 robotics and automation stocks.
Is Symbotic a Bargain on Sales?
P/S fits Symbotic because investors are effectively paying for a sales engine that is still translating revenue into consistent profits.
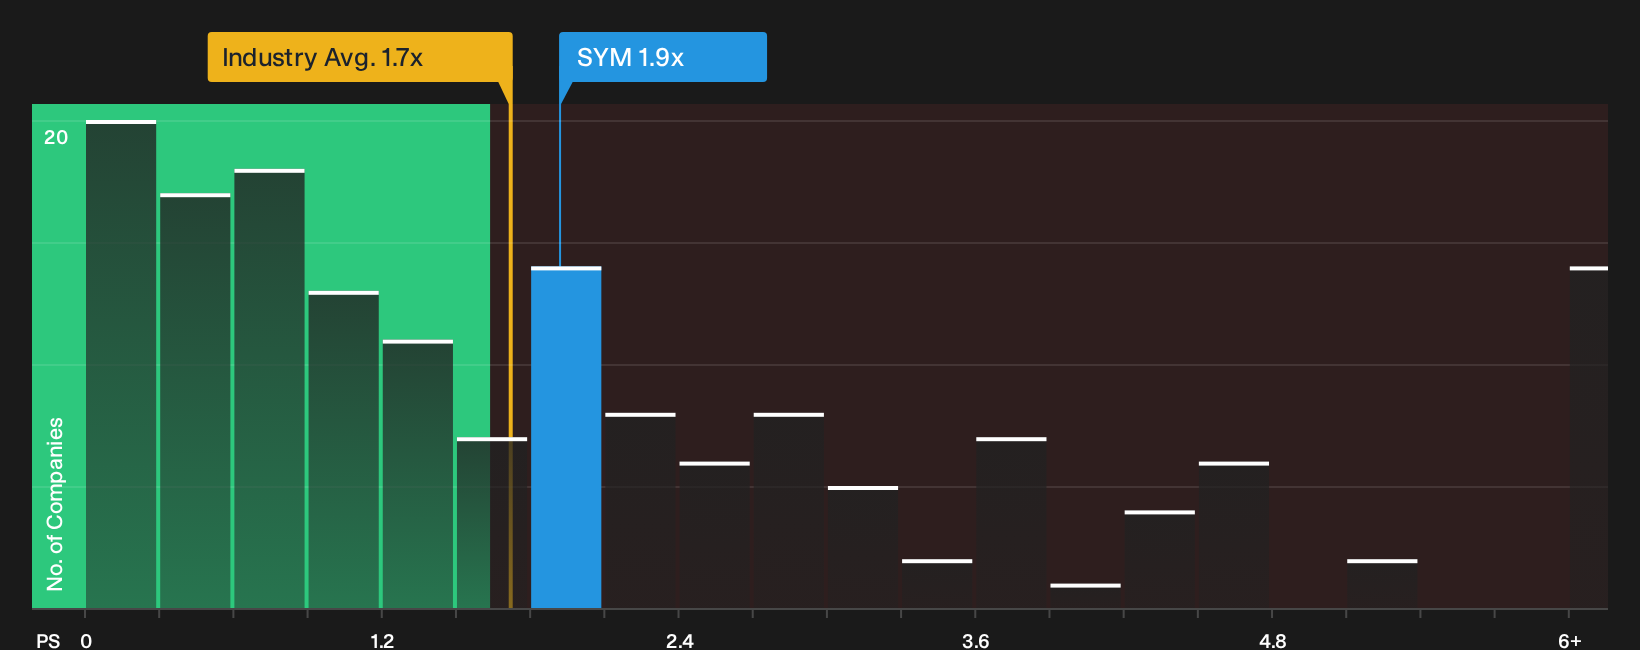
On this metric, the stock trades on a P/S of about 1.9x. That sits below the broader Machinery industry average of roughly 1.7x, yet also under the peer group level of about 3.2x for similar automation focused businesses. A Fair Ratio that blends Symbotic's growth assumptions, margins, size and risk profile points to a higher P/S than the current figure, which means the market price screens as undervalued against that tailored benchmark.
Because interest in robotics around projects linked to groups like SoftBank keeps attention on automation themed stocks, this discount on P/S suggests Symbotic is not being priced as aggressively as some sector peers despite the buzz. That gap leaves the P/S multiple as a useful starting point for readers comparing what each dollar of Symbotic's revenue currently costs versus other ways to get exposure to warehouse automation. Explore the numbers behind Symbotic's P/S valuation.
The Symbotic Narrative: What Would Justify Today's Price?
Symbotic's Simply Wall St Narratives pick up where the P/S discussion leaves off and explain which combinations of revenue growth, margins and earnings would need to occur for the current share price to appear meaningfully higher or lower over time on the Community page. Each narrative is presented as a clear, testable idea about how Symbotic's business might develop so you can see whether the story is tracking toward or away from that expectation.
Community views on Symbotic split between those who see more upside left in the story and those who think most of the good news is already in the price.
Bull case: 54% undervalued
"The current valuation implies that the market is not fully pricing in a business with a US$22.5b backlog, a growing base of operational systems, rising high-margin software and services revenue, and a debt-free balance sheet with US$1.7b of cash…"
Discover why this Narrative puts Symbotic at 54% undervalued.
Bear case: roughly fairly valued
"Rising capital intensity, with quarterly CapEx including capitalized software running at about US$20–25 million and cash and equivalents moving from about US$2.0b to US$1.7b in fiscal Q3 2026, raises the risk that any pause in project starts or customer decisions leaves Symbotic with compressed free cash flow and less flexibility to support earnings through a slower order period…"
Explore why this Narrative puts Symbotic at roughly fairly valued.
One last Symbotic check that sits beyond the share price
Valuation only goes so far without asking who is steering Symbotic and how their pay nudges decisions on risk, growth and capital use. See who runs Symbotic and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com