


Circle Internet Group has been under pressure, with the stock falling sharply over the past year just as regulators in the US and Europe tighten the rules around USDC and other stablecoins. That mix of price weakness and shifting oversight puts the spotlight on a simple question for investors who follow Circle Internet Group: whether today’s valuation is properly grounded in the cash the business can generate.
- The share price is down 38.0% over the past year, which raises the issue of whether the current market value matches the cash flow profile the company is building around USDC.
- Fresh regulatory milestones in both the EU and US can reshape how fast USDC volumes translate into usable cash flows, as stricter reserve and supervision frameworks may support more durable revenue streams but could also affect costs and capital needs.
- Prefer to judge Circle Internet Group on earnings? See what Circle Internet Group's 46.2x P/E says about the price.
The issue now is whether Circle Internet Group’s current share price is justified by the cash flows implied by its Discounted Cash Flow (DCF) intrinsic value estimate.
If you are weighing Circle Internet Group against other ways to put cash flow and valuation under the microscope, it can help to compare it with 26 high quality undervalued stocks.
Where Does Circle Internet Group Sit on Cash Flow?
The Discounted Cash Flow (DCF) model here looks at the cash Circle Internet Group could return to shareholders over time and brings those figures back to today in $ terms. Latest twelve month free cash flow sits at about $690.4 million, so this is already a cash generative business rather than a pure story stock.
Analysts feeding into the DCF are assuming growing free cash flow, with projections reaching into the mid single digit billions over the coming decade before discounting. That helps explain why the intrinsic value estimate comes out broadly in line with the current share price of $81.71, rather than implying a large gap in either direction. Because USDC has now been tagged as the first “significant” e money token under MiCA in Europe, the tighter capital and reserve rules help frame those projected cash flows as more regulated, but also more tightly supervised, than many crypto peers. Find out what Circle Internet Group could be worth using our Discounted Cash Flow (DCF) estimate.
The Circle Internet Group Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Circle Internet Group valuation puzzle leaves off and explain which assumptions on growth, profitability and earnings would need to hold for the shares to be worth materially more or less than today’s price, all housed on the Community page. Each Narrative treats Circle Internet Group's fair value as a thesis that can be revisited over time, so you can see how the underlying story holds up as new information arrives.
Community views on Circle Internet Group split between those who see licensing and Arc traction as underappreciated and those who think USDC economics already look fully reflected.
Bull case: 58% undervalued
"The launch of Arc Mainnet with more than 100 partners, nearly 3 million test wallets, around US$0.5b in testnet transactions and a roughly US$3b fully diluted network value creates room for Circle Internet Group to build new fee and token linked income streams…"
Discover why this Narrative puts Circle Internet Group at 58% undervalued.
Bear case: 128% overvalued
"Distribution, transaction, and other costs rose to US$461 million, increasing 52% year-over-year, largely driven by partner distribution payments…"
Explore why this Narrative puts Circle Internet Group at 128% overvalued.
One more Circle Internet Group check that belongs beside the valuation work
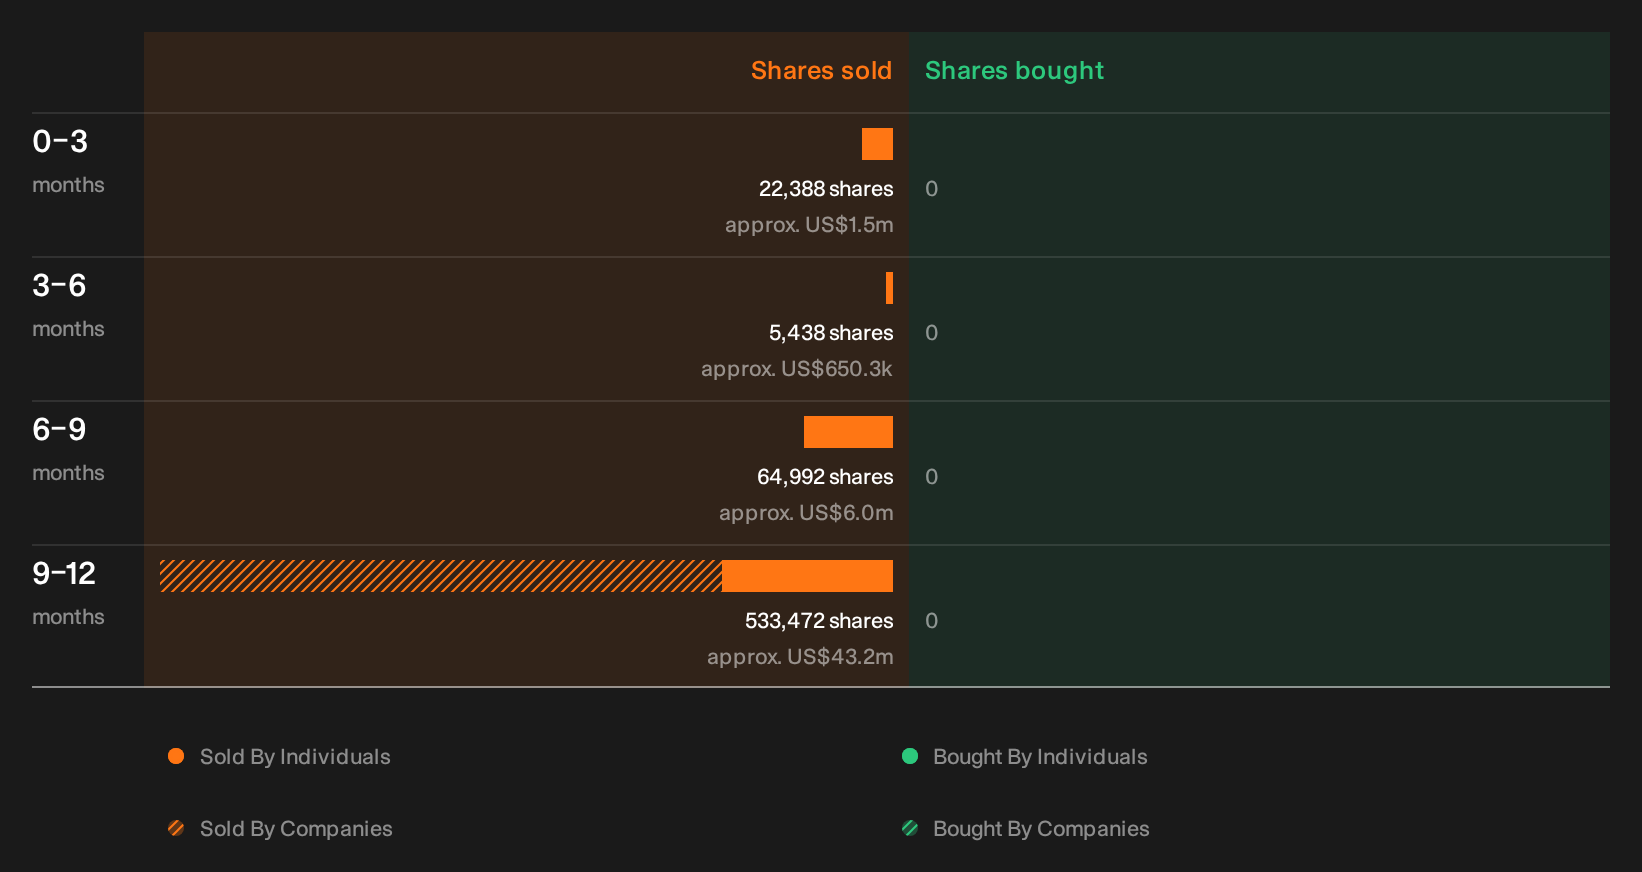
Price and cash flow only tell part of the story for Circle Internet Group, because recent dealings by people on the inside of the business have also triggered a fresh item on the checklist. See the recent insider selling flagged for Circle Internet Group.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com