


Paycom Software has delivered a strong run in recent years, which puts fresh attention on what investors are really paying for its earnings today. With a US$262.79 share price at the last close, the question now is how that performance lines up with what the business is generating in profit.
- Over the past 3 years, Paycom Software has returned 78.7%. This puts meaningful weight on whether its current earnings profile can support that kind of share price outcome.
- The company earns revenue from its payroll and human capital management platform. The durability of client relationships and the profitability of recurring fees may shape how much value investors can reasonably ascribe to each dollar of earnings.
- The analysts covering Paycom Software have run their own numbers. See what analysts think Paycom Software's shares could be worth.
The issue now is whether Paycom Software's current share price is appropriately aligned with what its earnings justify on this basis.
If you are weighing whether Paycom Software's earnings justify its recent share price run, it can help to compare it with a broader field of companies filtered through 26 high quality undervalued stocks
Has Paycom Software Run Too Far on Earnings?
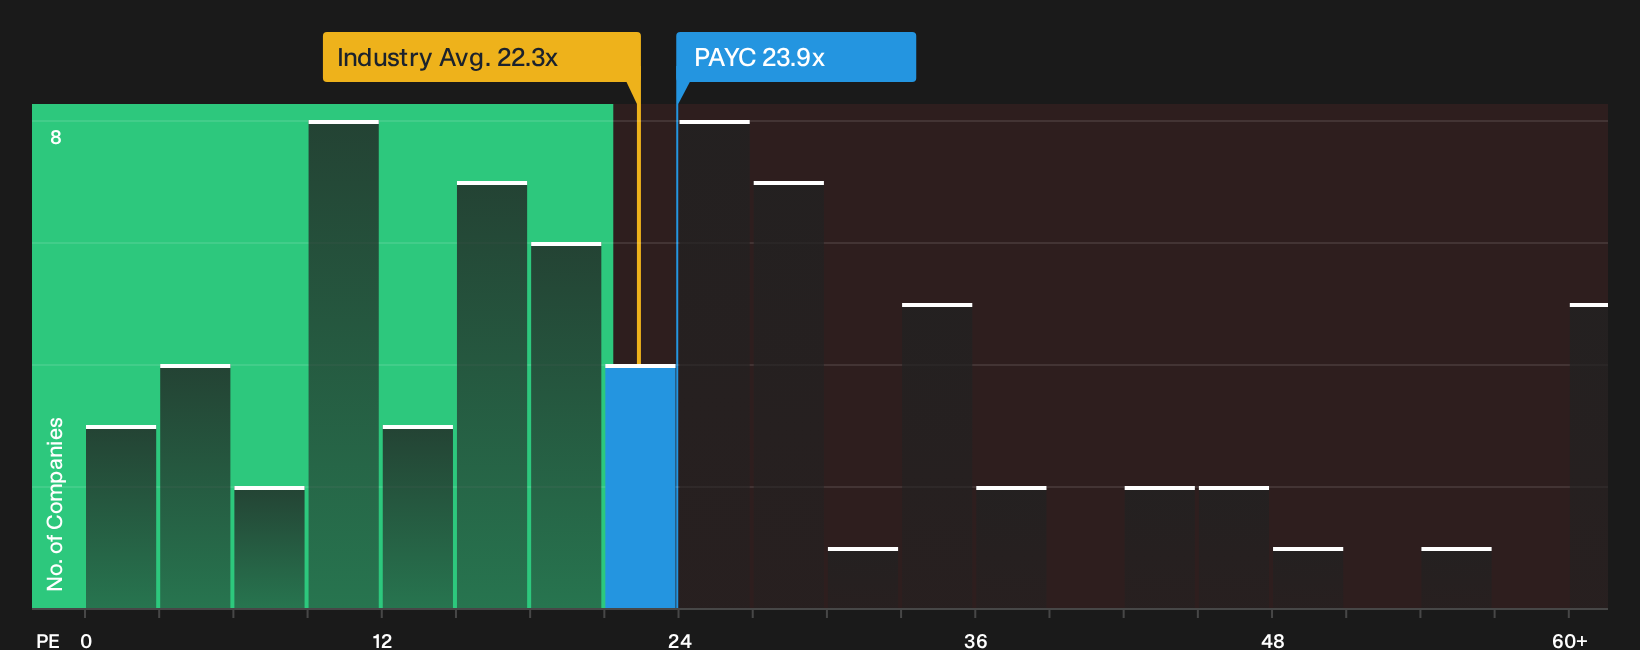
The P/E lens fits Paycom Software because earnings remain the main way shareholders can judge what they are paying for each dollar of profit. At the recent US$262.79 share price, the stock trades on a P/E of about 23.9x. That is slightly above the wider Professional Services industry average of roughly 22.3x and also above the peer group average of about 19.9x.
The tailored fair P/E implied by this framework sits below Paycom Software's current multiple, so the shares screen as overvalued on this specific earnings yardstick. The gap suggests investors are already placing a premium on the quality and stability of Paycom Software's payroll and human capital management earnings, relative to what this model would usually assign for businesses with similar characteristics. For anyone assessing whether that premium holds up, the key questions are how resilient those profits prove to be and whether future cash generation can justify paying more than the benchmark P/E. Explore the numbers behind Paycom Software's P/E valuation.
The Paycom Software Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Paycom Software pick up where this valuation question leaves off by spelling out what kind of future for growth, margins and earnings would need to play out for the stock to be worth meaningfully more or less than today’s price. Each narrative sets up a fair value as a thesis about Paycom Software's business that investors can track over time rather than a static snapshot.
Community views on Paycom Software split sharply, with one camp seeing meaningful upside and another arguing expectations already look stretched.
Bull case: 12% undervalued
"Owning the full tech stack, from a single database to owned data centers, addresses employer concerns about exposing sensitive HR data to external LLMs..."
Discover why this Narrative puts Paycom Software at 12% undervalued.
Bear case: 64% overvalued
"The current valuation implies that the market is placing a high multiple on 7 to 8% guided 2026 revenue growth, record mid 40s EBITDA margins, and free cash flow expected to exceed US$650 million..."
Explore why this Narrative puts Paycom Software at 64% overvalued.
One more piece of the Paycom Software story to check before you move on
Valuation only tells part of the story, because our research has also flagged specific risk checks on Paycom Software that could change how you view the whole setup. Take a closer look at 2 warning signs before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com