


In October 2026, the global markets have experienced heightened volatility driven by AI investment concerns and rising oil prices, yet small-cap stocks have shown resilience with the Russell 2000 Index advancing by 2.00%. Amid this backdrop, investors are increasingly focusing on small-cap companies that demonstrate strong fundamentals and potential for growth, particularly those with notable insider activity which can signal confidence in their future prospects.
Top 10 Undervalued Small Caps With Insider Buying Globally
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Q Technology (Group) | 3.3x | 0.2x | 46.92% | ★★★★★☆ |
| Transcontinental | 2.6x | 0.2x | -99.01% | ★★★★☆☆ |
| Diversified Royalty | 25.1x | 9.9x | 47.17% | ★★★★☆☆ |
| Franchise Brands | 27.0x | 2.0x | 48.13% | ★★★★☆☆ |
| Nexus Industrial REIT | 10.0x | 3.0x | 10.04% | ★★★★☆☆ |
| Pizza Pizza Royalty | 11.7x | 8.9x | 39.63% | ★★★★☆☆ |
| Saniona | 8.6x | 3.7x | 20.01% | ★★★★☆☆ |
| Sagicor Financial | 6.8x | 0.5x | -83.96% | ★★★★☆☆ |
| MCAN Mortgage | 10.3x | 5.9x | -8.14% | ★★★☆☆☆ |
| AB Dynamics | NA | 1.8x | 20.75% | ★★★☆☆☆ |
Let's explore several standout options from the results in the screener.
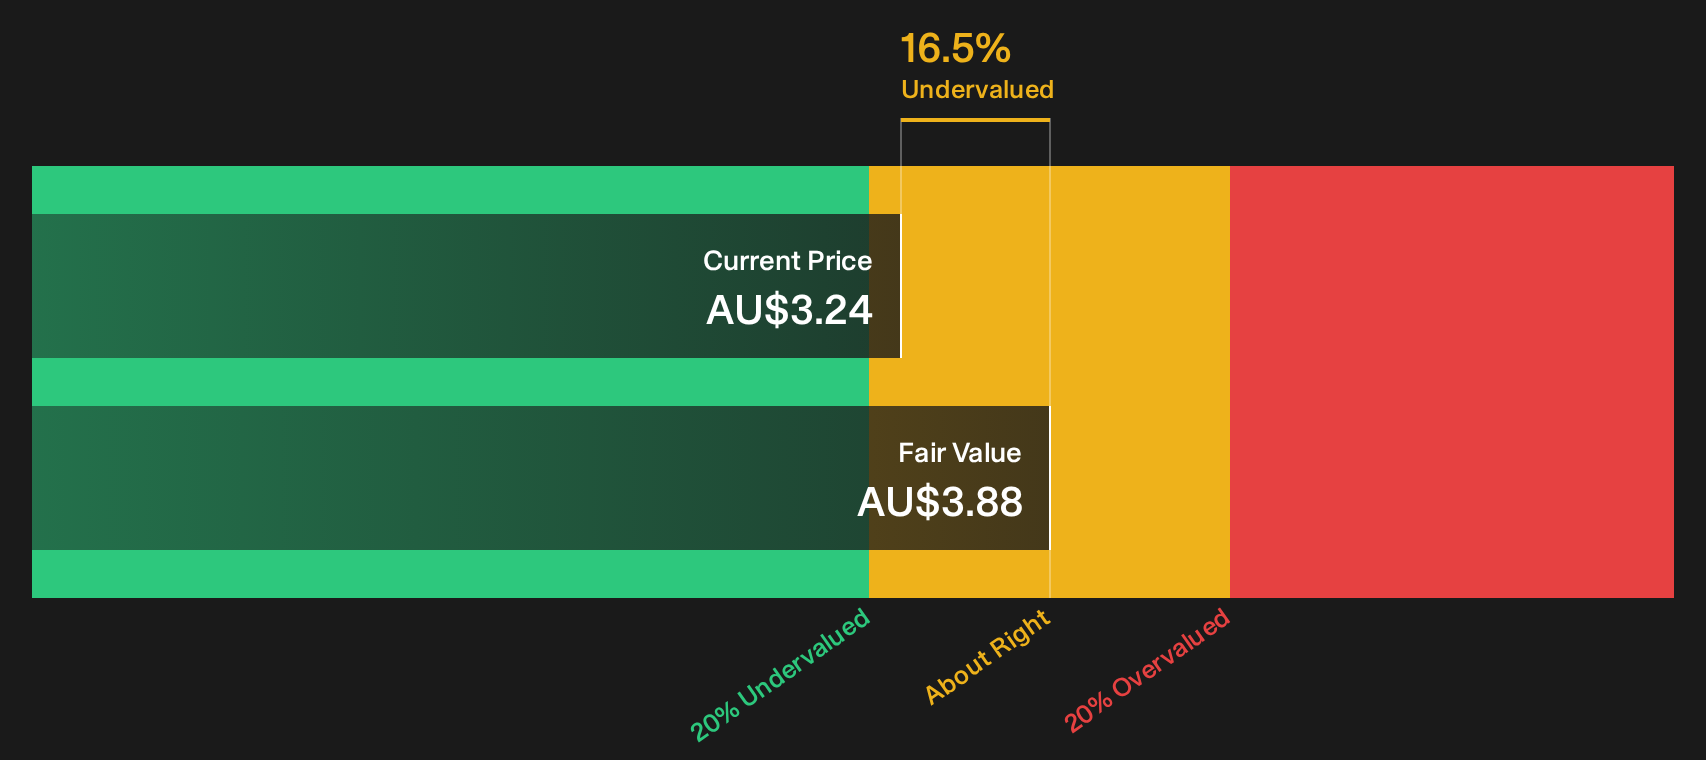
Australian Clinical Labs (ASX:ACL)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Australian Clinical Labs operates in the healthcare sector, providing pathology and clinical laboratory services, with a market capitalization of A$1.02 billion.
Operations: The company's primary revenue stream is from Pathology/Clinical Laboratory Services, generating A$736.15 million. Over recent periods, the gross profit margin has fluctuated, reaching 38.13% in the latest quarter. Operating expenses have consistently been a significant cost factor, with general and administrative expenses contributing notably to this category.
PE: 25.3x
Australian Clinical Labs, a smaller player in the healthcare sector, showcases insider confidence with recent share purchases. Despite facing a slight dip in sales and revenue to A$735.75 million and A$736.15 million respectively for the year ending June 2026, their earnings are set to grow at 16% annually. However, reliance on external borrowing poses funding risks. The company recently announced an increased fully franked dividend of A$0.0925 per share, reflecting commitment to shareholder returns amidst these challenges.
- Navigate through the intricacies of Australian Clinical Labs with our comprehensive valuation report here.
Assess Australian Clinical Labs' past performance with our detailed historical performance reports.
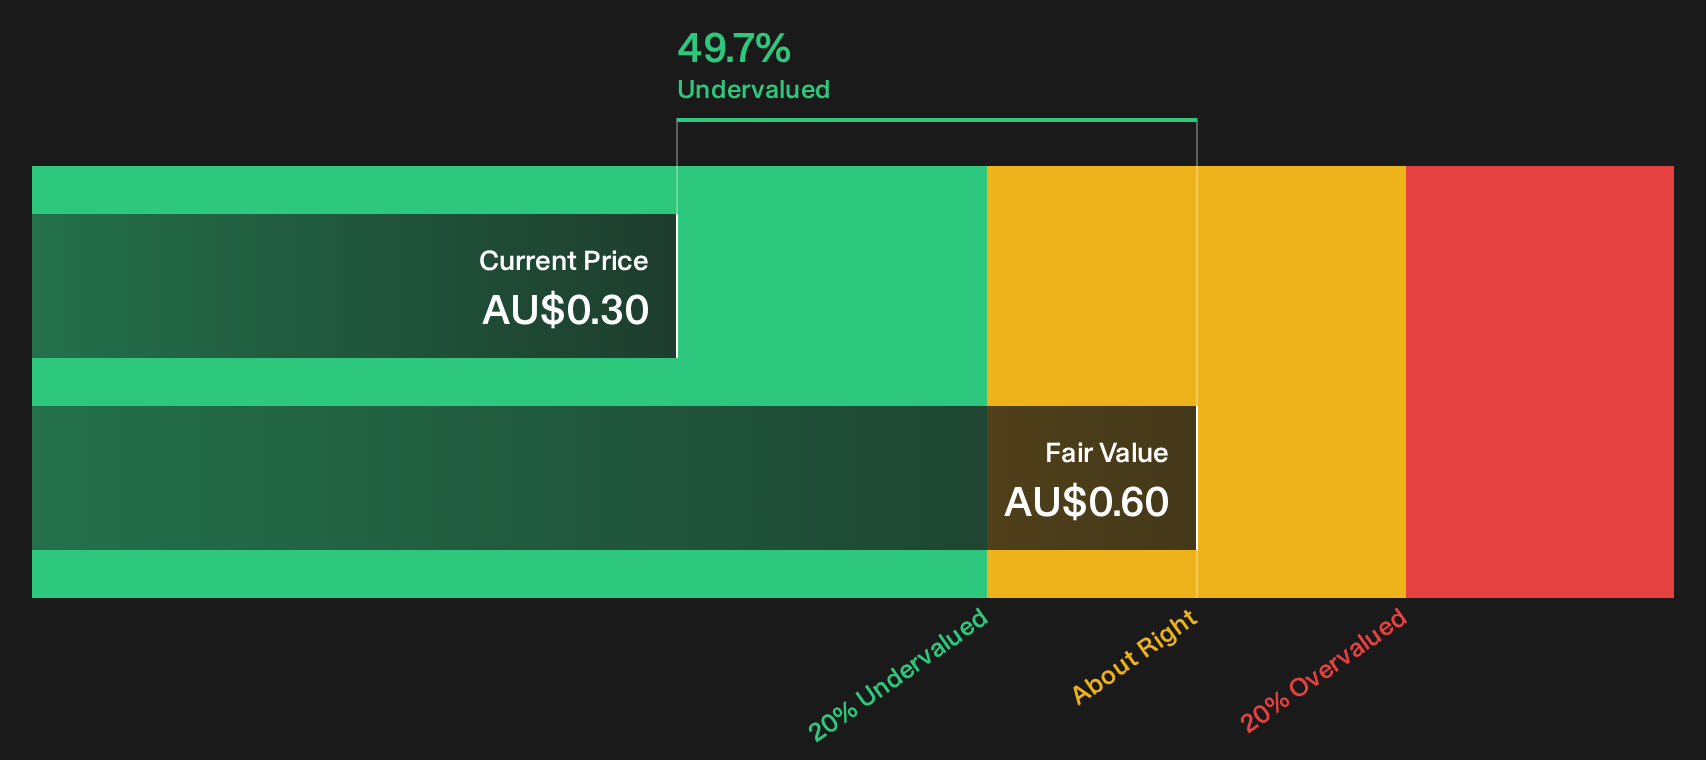
EQ Resources (ASX:EQR)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: EQ Resources is involved in mineral exploration, with a focus on developing and operating resource projects, and has a market capitalization of A$165.44 million.
Operations: EQ Resources generates revenue primarily from mineral exploration, with a recent revenue figure of A$165.44 million. The company's cost structure includes significant costs of goods sold and operating expenses, which have historically impacted profitability. Notably, the gross profit margin has shown improvement in recent periods, reaching 41.91%.
PE: 218.8x
EQ Resources, a company with a focus on tungsten projects, recently reported significant financial improvements. For the year ending June 30, 2026, sales surged to A$165.44 million from A$66.05 million the previous year, while net income turned positive at A$7.11 million from a loss of A$39.23 million last year. Insider confidence is evident as an insider purchased one million shares for approximately A$297,500 in October 2026. The company's strategic expansion into joint ventures and index inclusions highlights its potential for growth despite reliance on external funding sources and past shareholder dilution challenges.
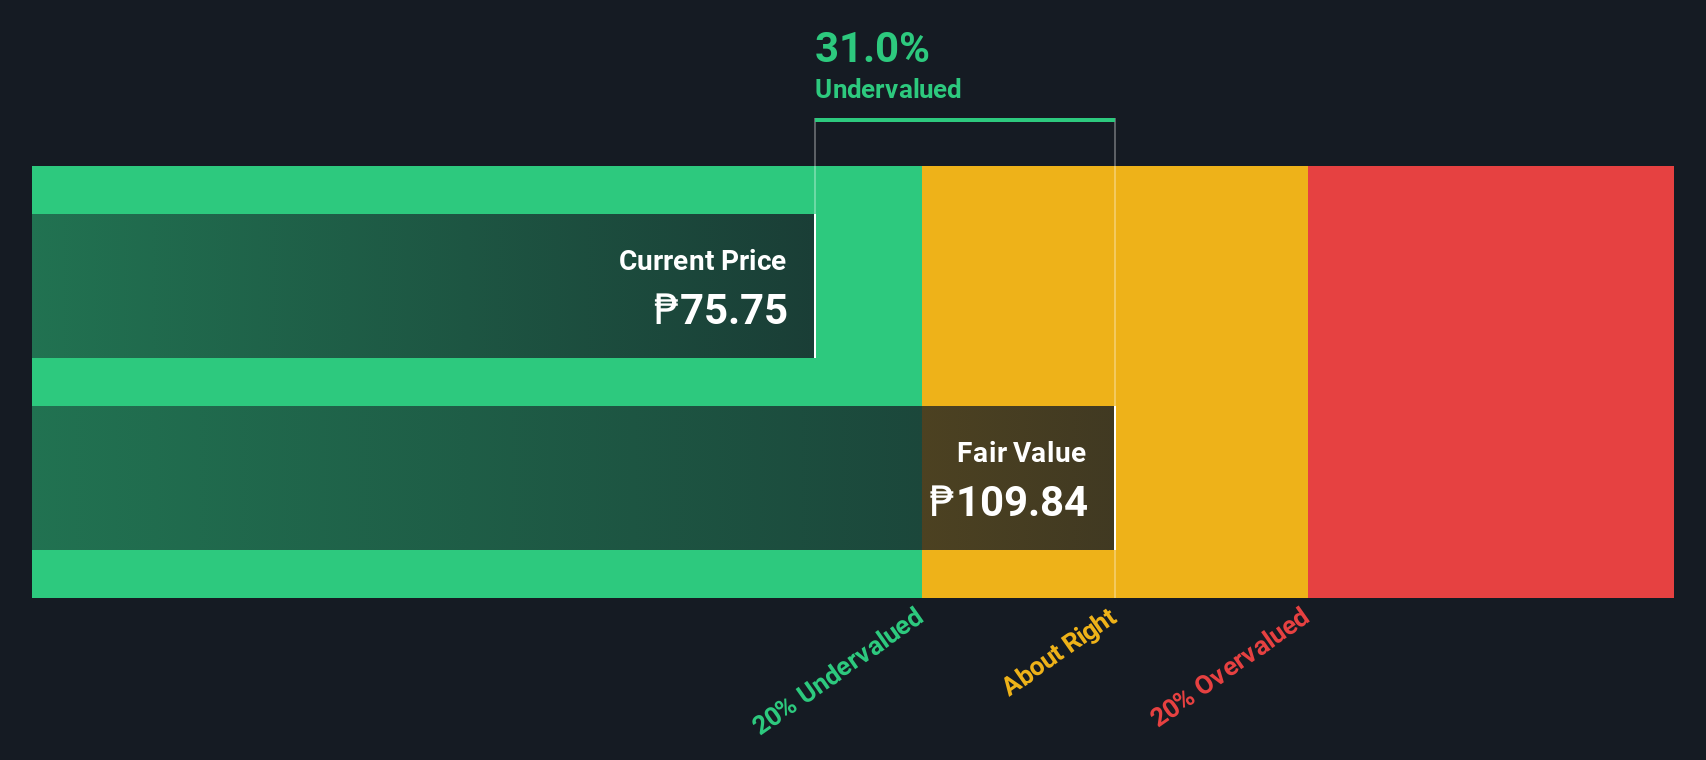
Security Bank (PSE:SECB)
Simply Wall St Value Rating: ★★★★★★
Overview: Security Bank is a financial institution that provides a range of services including retail banking, business banking, financial markets, and wholesale banking with operations contributing to its market capitalization of ₱106.58 billion.
Operations: Retail Banking and Wholesale Banking are the primary revenue streams, contributing ₱25.82 billion and ₱20.47 billion respectively, with Financial Markets also playing a significant role at ₱8.69 billion. The company has experienced fluctuations in its net income margin, which was 21.04% as of June 2026, reflecting variations in profitability over time. Operating expenses have been a substantial portion of costs, with general and administrative expenses consistently being one of the larger components within this category.
PE: 4.0x
Security Bank, a smaller player in the financial sector, recently experienced insider confidence with share purchases over the past quarter. Despite challenges like a 3% bad loans ratio and an allowance for bad loans at 86%, it shows promise with earnings projected to grow by 15.41% annually. The bank's addition to the S&P Global BMI Index highlights its potential appeal. Recent leadership changes aim to align strategic priorities, potentially enhancing operational efficiency and customer focus moving forward.
- Click here to discover the nuances of Security Bank with our detailed analytical valuation report.
Examine Security Bank's past performance report to understand how it has performed in the past.
Summing It All Up
- Click here to access our complete index of 112 Undervalued Global Small Caps With Insider Buying.
- Already own these companies? Link your portfolio to Simply Wall St and get alerts on any new warning signs to your stocks.
- Discover a world of investment opportunities with Simply Wall St's free app and access unparalleled stock analysis across all markets.
Ready To Venture Into Other Investment Styles?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com