


Europe’s energy price crunch has pushed household and government budgets into the spotlight, which puts reliable healthcare spending in sharp focus for UK investors. Essential services like medical treatment and medicines tend to stay in demand even when fuel and heating bills climb. This article picks out three high quality British healthcare stocks from a curated shortlist that combines solid finances with resilient business models.
The three stocks covered below are a sample of the strongest healthcare operators on the radar. The full screen also surfaced 2 more listed businesses with equally compelling stories that are not included here. To see the full set and quickly identify which ones fit your criteria, go straight to the Best Healthcare Stocks screener.
NIOX Group (AIM:NIOX)
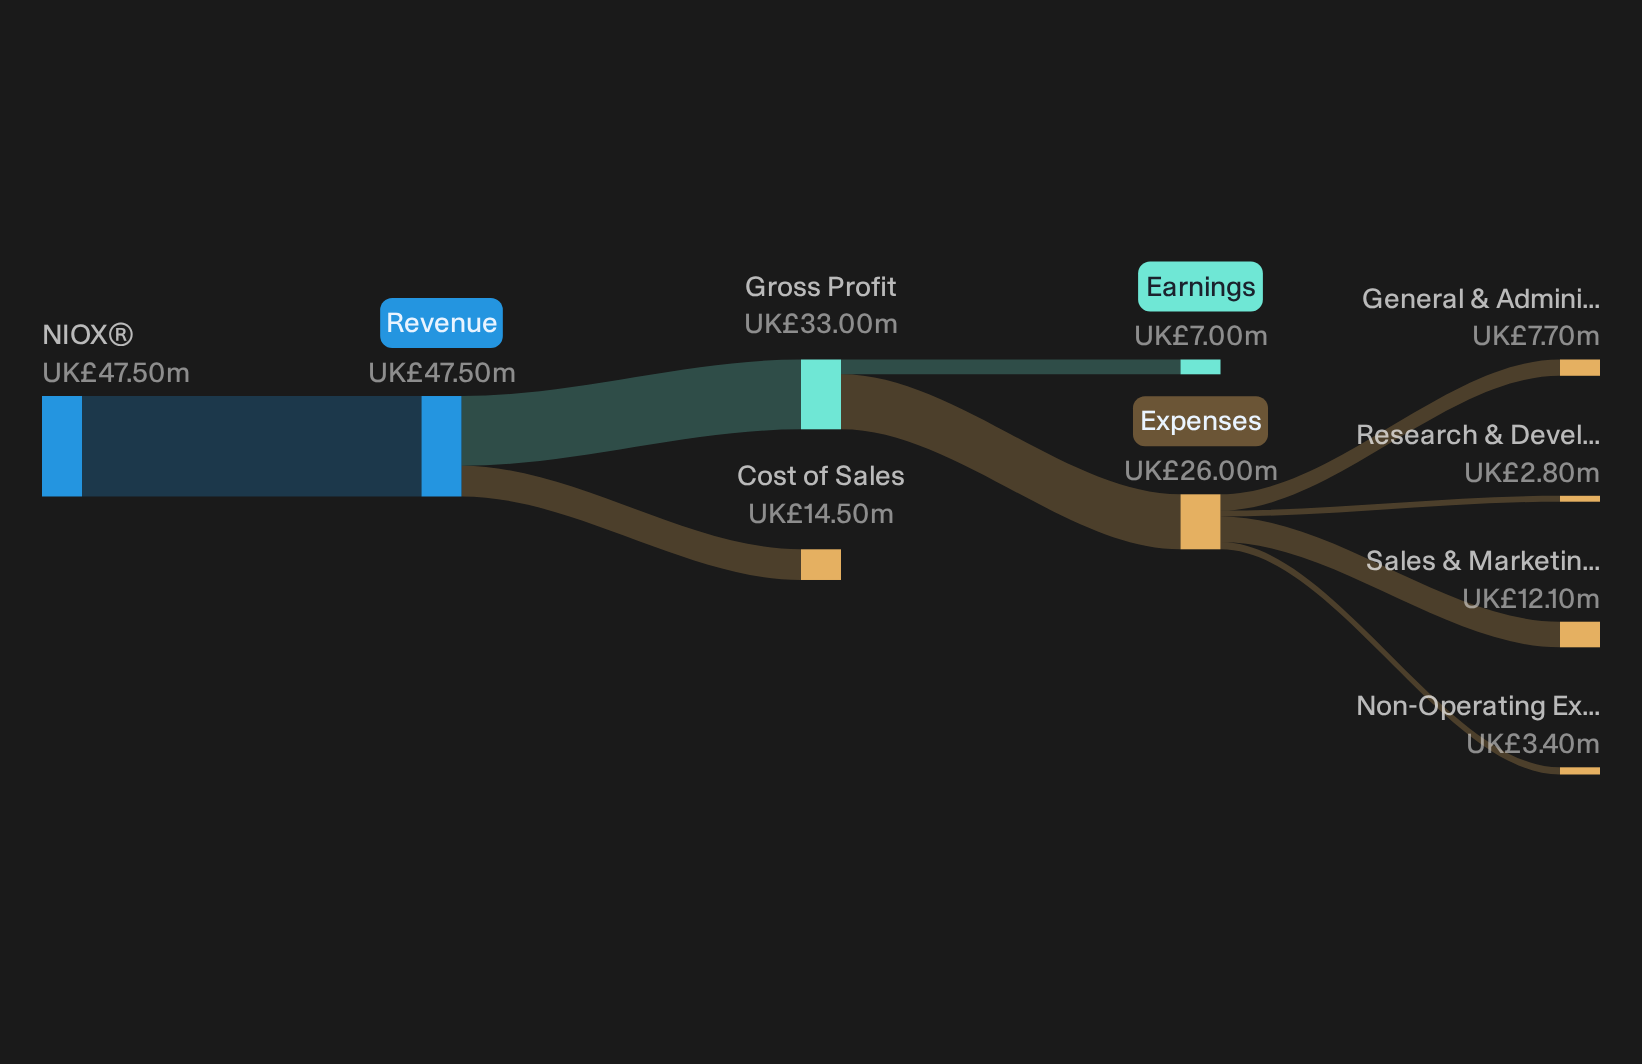
NIOX Group is a healthcare technology business built around its NIOX VERO device, which helps clinicians diagnose and manage asthma and COPD at the point of care. All revenue, £47.5 million in 2025, comes from the NIOX line, and the company’s market value is about £286 million.
NIOX Group aligns directly with the screener’s healthcare tech theme through its FeNO testing kit. It pairs a point of care device with recurring consumables in asthma and COPD clinics. Earnings growth has outpaced the wider UK medical equipment space. This supports today’s 14.7% profit margin and highlights one pressure point that could yet shift how much of that margin investors actually keep.
That margin pressure is exactly what the 4 key rewards and 1 important warning sign unpacks, so you can see where NIOX Group’s strengths may be masking future trade offs.
HUTCHMED (China) (AIM:HCM)
HUTCHMED (China) is a biopharma group focused on targeted cancer and immunology therapies, with theme linked strength coming from marketed oncology drugs Fruquintinib and Savolitinib alongside a broad late stage pipeline. In 2025 it generated about US$237 million from marketed oncology products, US$68 million from oncology and immunology R&D, and US$245 million from other ventures, with a market value close to £1.8 billion.
HUTCHMED (China) matters here because it brings a growing suite of targeted cancer and blood disorder medicines that already fit squarely inside the screener’s focus on high quality healthcare franchises with room to scale.
"Early hematology data for sovleplenib in wAIHA, including higher durable response rates, faster hemoglobin recovery and lower use of rescue therapies compared with placebo, combined with priority review status in China, creates headroom for HUTCHMED to add a new revenue stream that is less tied to existing solid tumor products and could shift the earnings mix toward hematology."
What happens to HUTCHMED’s earnings profile if that emerging franchise changes how much high margin income flows through the rest of this decade?
If that shift in earnings mix is what matters to you, read the full narrative for HUTCHMED (China) to see how HUTCHMED (China) could accelerate or stall from here.

Integrated Diagnostics Holdings (LSE:IDHC)
Integrated Diagnostics Holdings runs a broad diagnostics platform across pathology and radiology, putting it squarely in the Best Healthcare Stocks screener as a testing and imaging specialist. The group generated about EGP 2,941 million from walk-in patients and EGP 6,229 million from contracts, and carries a market value near US$267 million.
For investors who want pure exposure to healthcare services rather than drug pipelines or device makers, Integrated Diagnostics Holdings offers direct access to everyday testing and imaging that hospitals and patients rely on.
"The decision to acquire the remaining 49% stake in the Saudi Arabian venture gives IDH full control over the entity, enabling more flexible execution of its strategy in a high-potential market, supporting revenue and possibly net margins as operations scale."
What really matters next is how one pressure point in its funding mix shapes future returns on all that diagnostic capacity.
That funding mix question is exactly what the full narrative for Integrated Diagnostics Holdings unpacks, highlighting how Integrated Diagnostics Holdings could experience changes in returns, including potential acceleration, divergence from past patterns, or the risk of stalling.

Seeking Fresh Alternatives Beyond Healthcare?
Fresh ideas often move first. Breakout stories, early momentum and under the radar stocks can get noticed quickly once the crowd arrives, so review these ideas while they are still timely and consider your options promptly.
- Explore early-stage upside with hand-picked growth stories from the 14 elite penny stocks with strong financials before momentum traders focus on them and entry points become less accessible.
- Evaluate long-term cash flow potential by screening a curated 4 dividend fortresses that aims to keep paying even when markets lose momentum.
- Position for potential infrastructure-related opportunities by tracking curated enablers of the AI buildout with the focused 54 AI infrastructure stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com