


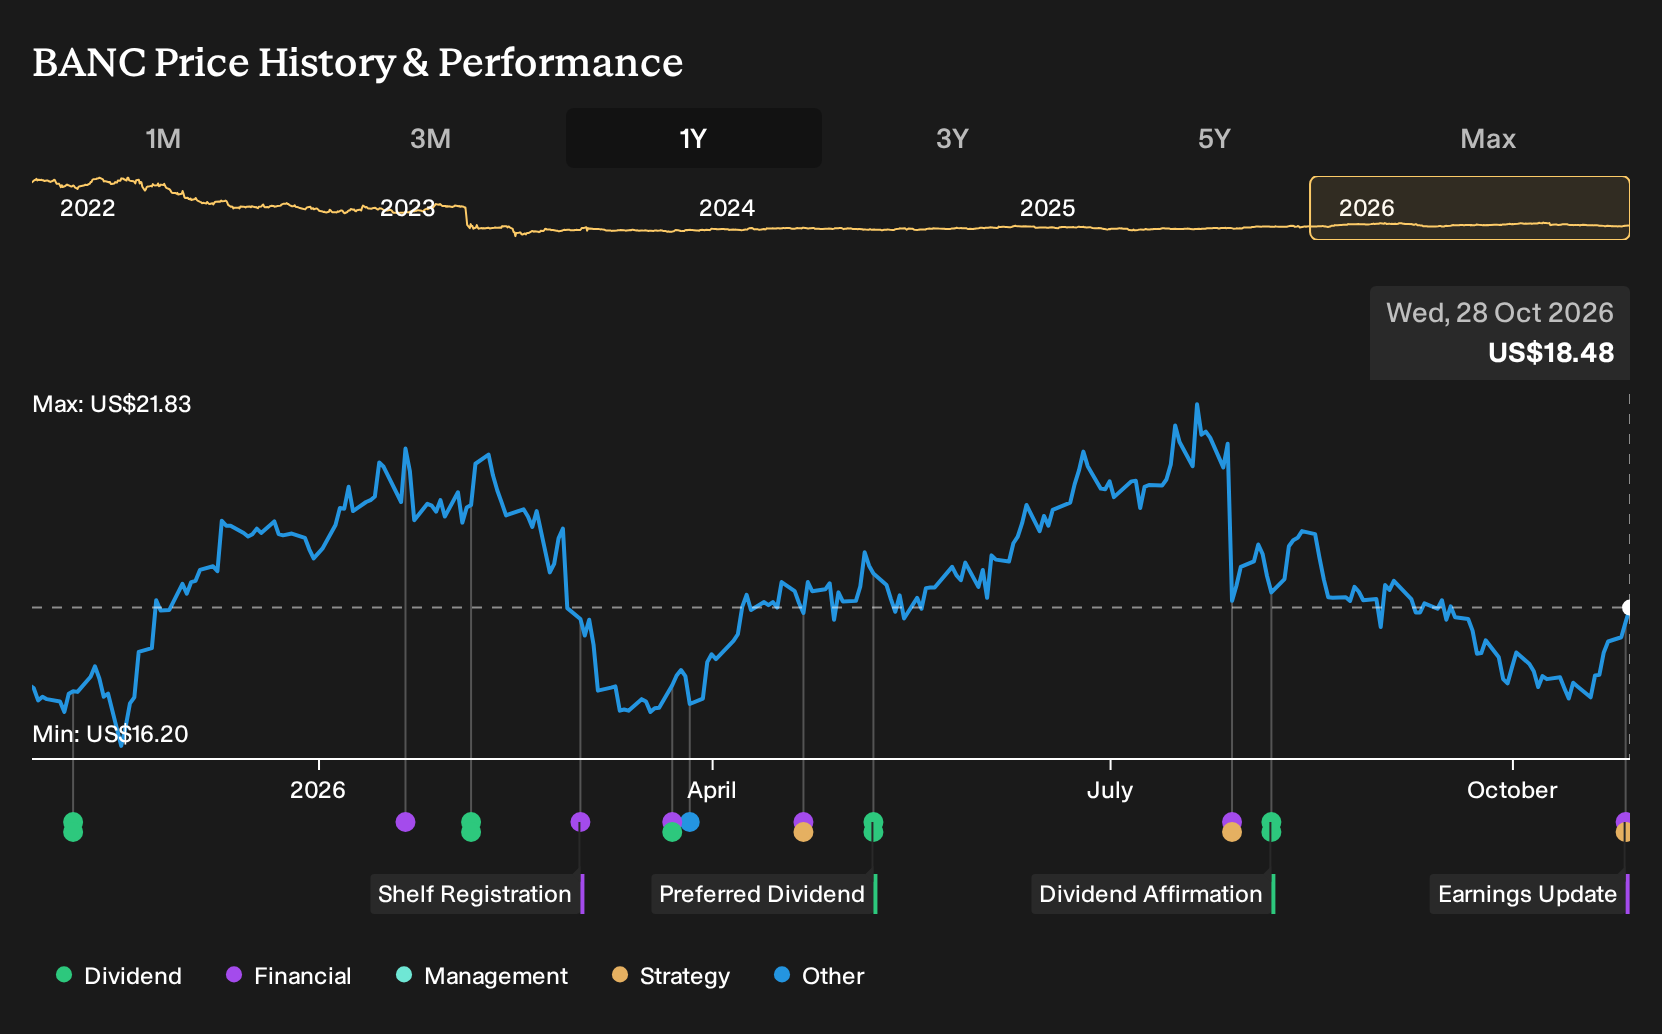
- Banc of California reported third quarter 2026 net income of US$83.06 million, or US$0.46 per diluted share from continuing operations, with net interest income of US$272.44 million.
- Across the first nine months of 2026, net interest income reached US$774.56 million while the banking group recorded a net loss of US$86.34 million and third quarter net charge offs of US$17.29 million, highlighting ongoing credit and restructuring pressures behind the headline profit.
- We will now look at how Banc of California's investment narrative is affected by stronger quarterly earnings supported by balance sheet repositioning.
Banc of California Investment Narrative Recap
To own Banc of California, you need to believe the merger integration, loan book reshuffle, and digital investments can turn recent restructuring pain into steadier profitability. The third quarter profit, supported by US$272.44 million of net interest income, points to a franchise that still generates earnings power even while the year to date numbers are weighed down by earlier actions.
The key short term catalyst is operational follow through on balance sheet repositioning, so that future quarters show cleaner earnings with less noise from one off items. The biggest near term risk is credit quality and integration execution, especially with higher net charge offs, which could keep provisions and expenses elevated if conditions stay tough.
The most relevant update is the swing in credit costs. Banc of California reported third quarter net charge offs of US$17.29 million, compared with recoveries a year earlier. That shift matters because the whole thesis around loan portfolio reshaping, including commercial real estate reductions, hinges on containing future credit losses while still supporting interest income.
For you as a shareholder, the question is whether recent earnings, including US$83.06 million of quarterly net income, signal a more resilient run rate or simply a good period while credit costs tick higher. If management can keep generating solid net interest income while holding charge offs in check, it supports the idea that merger integration, deposit gathering, and lending focus are starting to translate into more durable returns.
Banc of California's narrative projects US$1.6b revenue and US$738.7 million earnings by 2029. This would entail 33.6% yearly revenue growth and an earnings increase of about US$791 million from the current earnings of a US$52.3 million loss.
Uncover how Banc of California's fair value indicates an 18% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Banc of California’s balance sheet remix as the key catalyst. Before these results, they were projecting revenue of about US$1.6b and earnings of roughly US$605.3 million by 2029. You can treat those upbeat assumptions as one possible path and compare them with other viewpoints after this earnings and credit update.
Explore 2 other Banc of California fair value estimates, including one that suggests as much as 326614% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Banc of California research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Banc of California. The report includes a comprehensive fundamental analysis summarized in a single visual called the Snowflake, making it easy to evaluate Banc of California's overall financial health at a glance.
Looking For More Investment Ideas Beyond Banc of California?
If the Banc of California story has sharpened your thinking about balance sheets, earnings quality, and risk, it can help to set it against a wider watchlist. Fresh ideas often emerge when you compare one bank or lender with others that have different capital strength, payout habits, or valuation profiles.
- For investors who want potential bargains with quality fundamentals, scan through 26 high quality undervalued stocks that might merit a closer look.
- If capital preservation and steadier profiles matter most to you, narrow your search to a 32 resilient stocks with low risk scores that may better fit a cautious approach.
- When you are hunting for future leaders that are not yet widely appreciated, focus on a curated pool of 19 high quality undiscovered gems with stronger underlying metrics than their size implies.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com