


Renewed attention on iRhythm Holdings (IRTC) follows fresh coverage highlighting rapid annual revenue expansion and a recent shift to positive free cash flow. This combination points to tighter cost control and growing traction for its wearable cardiac monitoring services.
Recent share price action reflects that shift. The stock has climbed with a 9.2% 7 day share price return and a 10.1% 30 day share price return, yet remains down 29.2% year to date. Meanwhile, the 3 year total shareholder return of 57.1% points to momentum that has built over a longer horizon.
Spot emerging healthcare compounders by comparing iRhythm Holdings with a curated list of 36 healthcare AI stocks, which are also pairing rapid top line expansion with improving cash generation.iRhythm Holdings now appears to be a healthier business than it was a year ago, yet the share price has already moved sharply higher in recent weeks. Are buyers paying a fair price for that progress, or reaching for growth that is already reflected in the current valuation?
Most Popular Narrative: 28% Undervalued
The most followed narrative pegs iRhythm Holdings at a fair value of $171.33 compared with the last close of $123.99, so the market price sits well below that estimate while the story leans heavily on long term cardiac monitoring adoption and profitability turning a corner.
Investment in the Zio ecosystem including next-generation patches, enhanced form factors, and AI-powered analytics (such as the Lucem Health partnership) is improving product differentiation, diagnostic yield, and workflow efficiency. This is likely leading to higher gross margins and operating leverage as software and data become a larger component of the business.
See why 5 investors see iRhythm Holdings as 28% undervalued.
Result: Fair Value of $171.33 (UNDERVALUED)
Still, iRhythm Holdings faces meaningful pressure from regulatory scrutiny and data privacy investigations that could weigh on costs and investor confidence if the outcomes disappoint.
Find out about the key risks to this iRhythm Holdings narrative.
Another View: iRhythm Holdings Through a Sales Multiple Lens
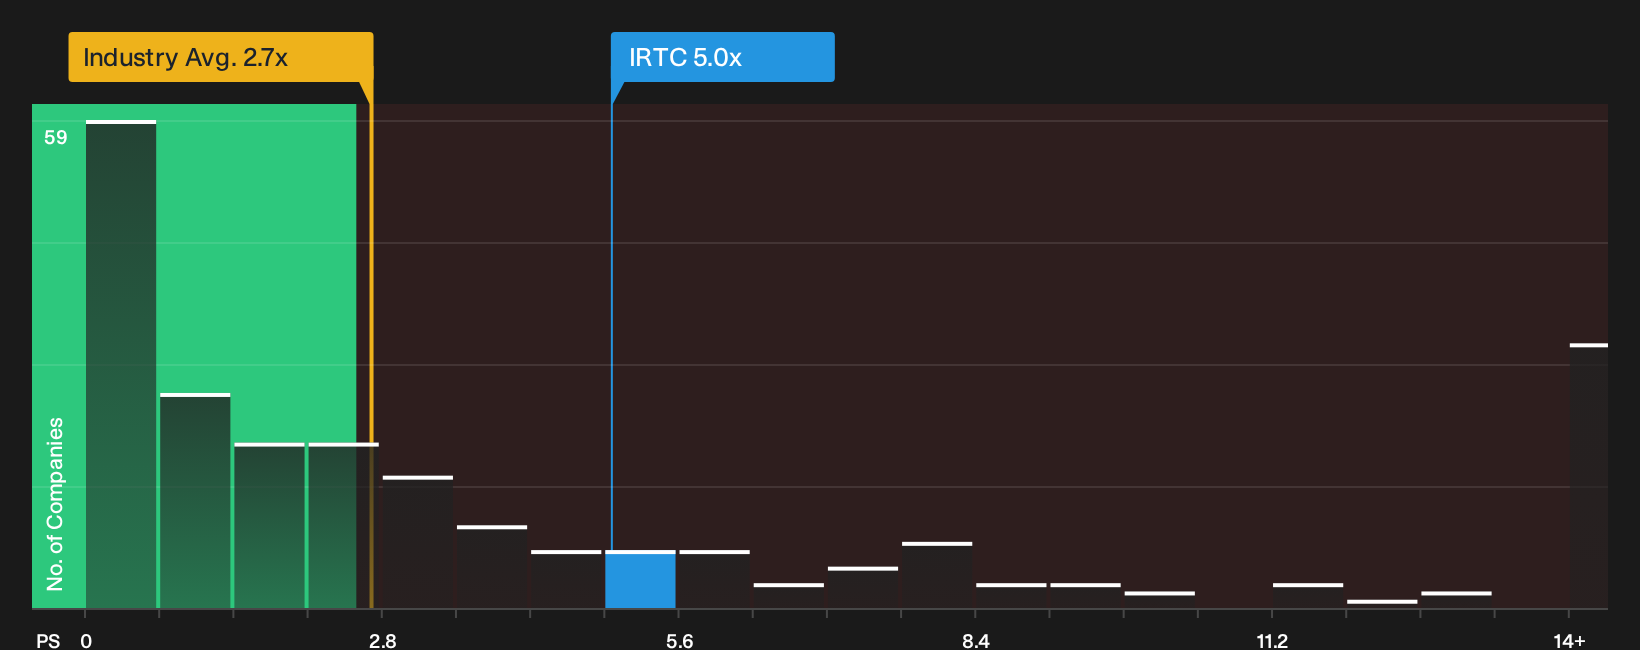
That fair value of $171.33 leans heavily on future cash flows and profitability. On current trading, iRhythm Holdings changes hands at about 5x sales, compared with a 2.6x P/S for the US Medical Equipment group and a 3x peer average, while the fair ratio sits at 4.7x. The gap points to investors already paying up on today’s revenue line, even as the DCF narrative argues there is value left on the table. The question for investors is which signal to treat as the anchor.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in iRhythm Holdings can feel confusing, especially with both risks and rewards in play, so move quickly, look through the detail, and then weigh the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond iRhythm Holdings?
If you stop with iRhythm Holdings, you only see one angle. Broaden your watchlist with a few focused screens that surface different types of potential opportunities.
- Target resilient compounding potential by scanning a 26 high quality undervalued stocks list backed by solid fundamentals and compressed expectations.
- Prioritise balance sheet strength by reviewing a list of solid balance sheet and fundamentals (24 results) that can help you filter for sturdier businesses when conditions get tougher.
- Hunt for future leaders early by checking a 19 high quality undiscovered gems that highlights quality companies still flying under most investors' radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com