


Jiangxi Copper (SEHK:358) is back in focus after reporting nine month results to September 30, 2026, with sales of CNY 442,419.88 million and net income of CNY 11,686.56 million.
Despite the earnings release and the recent board reshuffle that moved Zhou Shaobing into the chairman role, Jiangxi Copper’s share price has come under pressure, with the 30 day share price return down 19.73% and the year to date share price return down 40.38%.
Scan beyond Jiangxi Copper and see how other producers are priced by reviewing the hand picked 17 top copper producer stocks that investors are watching closely after this earnings update.
Jiangxi Copper has just posted stronger nine month earnings while the share price has fallen hard. Does that shift the risk reward balance enough to make today’s valuation look more interesting for buyers?
Price-to-Earnings of 6x: Is it justified?
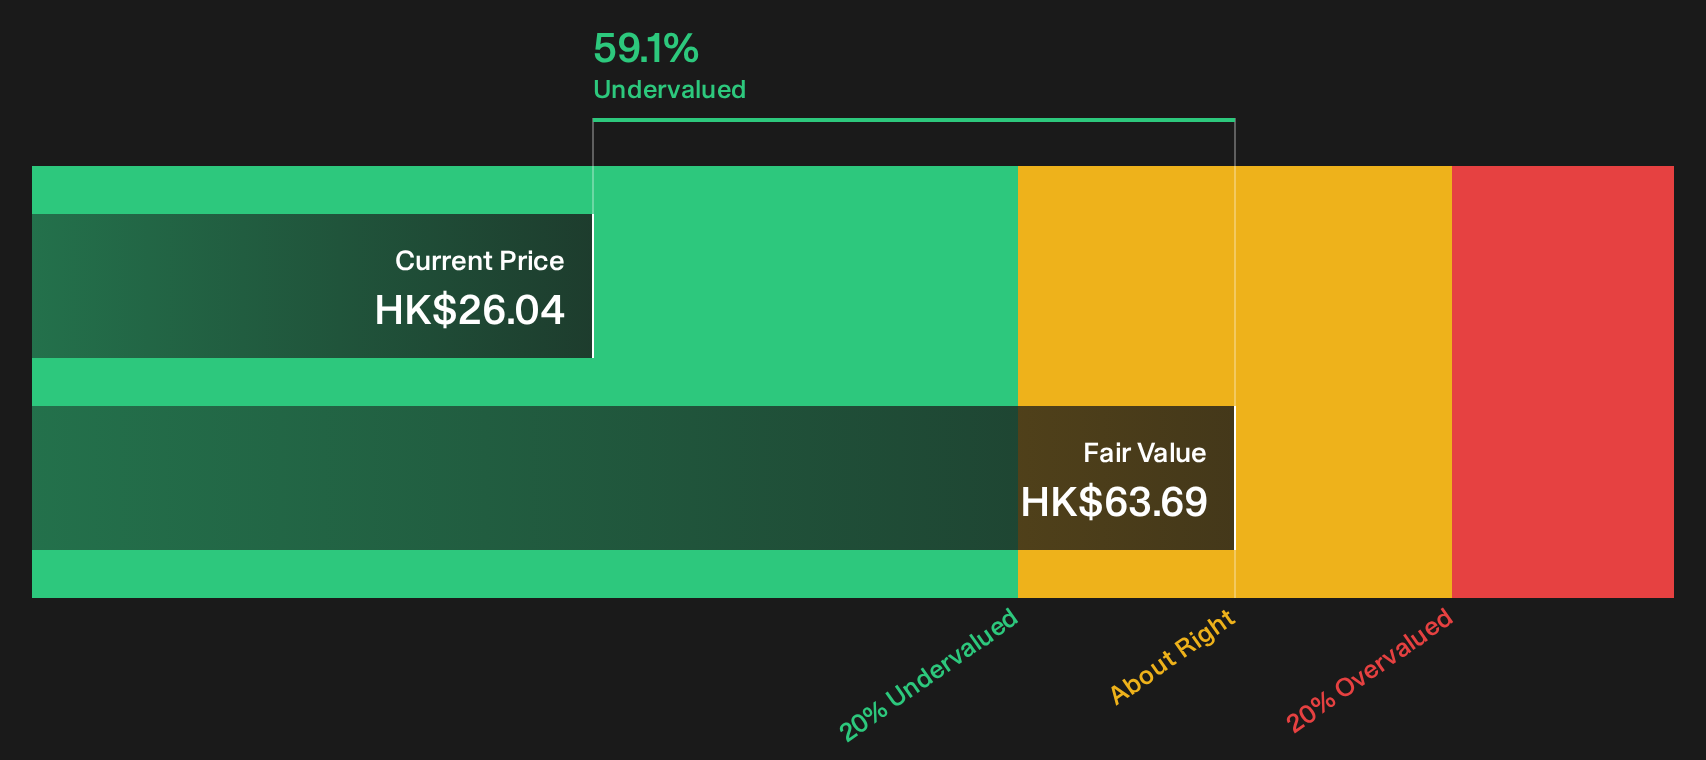
On simple numbers, Jiangxi Copper trades on a P/E of 6x, while also carrying a 59.1% discount to an estimated fair value and a share price of HK$26.04 that has fallen sharply this year compared to both the Hong Kong market and the local Metals and Mining group.
The P/E ratio compares what investors pay per share with the profits the business generates per share. For a miner and smelter like Jiangxi Copper, where earnings can swing with commodity cycles, this metric helps you see how much of those current profits the market is willing to pay for today.
Here, the stock changes hands at a lower P/E than its peer average of 9.4x and below the estimated fair P/E of 8.5x. That combination, alongside earnings growth of 59.9% over the past year that is faster than both its own 5 year earnings trend of 13.1% per year and the broader industry’s 48.5%, points to a market that is pricing Jiangxi Copper at a clear discount relative to its recent profit profile and to where valuation models suggest the P/E could reasonably move.
Against the Hong Kong Metals and Mining industry average P/E of 8.8x, Jiangxi Copper’s 6x multiple looks compressed. The fair P/E estimate of 8.5x implies a level the valuation could gravitate toward if current earnings prove sustainable or stabilise after the recent one off loss of CN¥5.5b that affected the last 12 months of results.
Explore the SWS fair ratio for Jiangxi Copper.
Result: Price-to-Earnings of 6x (UNDERVALUED)
Still, Jiangxi Copper faces clear risks, including earnings sensitivity to copper prices and the impact of any future operational or regulatory setbacks on sentiment.
Find out about the key risks to this Jiangxi Copper narrative.
Another View on Jiangxi Copper’s Value
The P/E story is one thing. A different lens comes from our DCF model, which estimates Jiangxi Copper’s future cash flows imply a fair value of HK$63.69 per share, compared with the current HK$26.04 price. That points to a very wide undervaluation gap. Is the market overreacting to short term noise, or are cash flow risks still underappreciated?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Jiangxi Copper for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 190 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
With Jiangxi Copper presenting both risks and potential rewards, sentiment is clearly split. Move fast, review the full data set, and decide where you stand by weighing the 3 key rewards and 1 important warning sign.
Ready for more investment ideas beyond Jiangxi Copper?
If Jiangxi Copper has sharpened your focus on value and risk, do not stop here. Broader opportunity often sits where fresh ideas meet disciplined filters.
- Target resilience by scanning companies that score well on balance sheet strength and fundamentals with this focused list of solid balance sheet and fundamentals (204 results).
- Hunt for quality at a discount by reviewing a curated 190 high quality undervalued stocks that may align better with your return and risk expectations.
- Spot potential early stage winners by checking a tightly screened 131 elite penny stocks with strong financials that filters for financial strength rather than pure speculation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com