


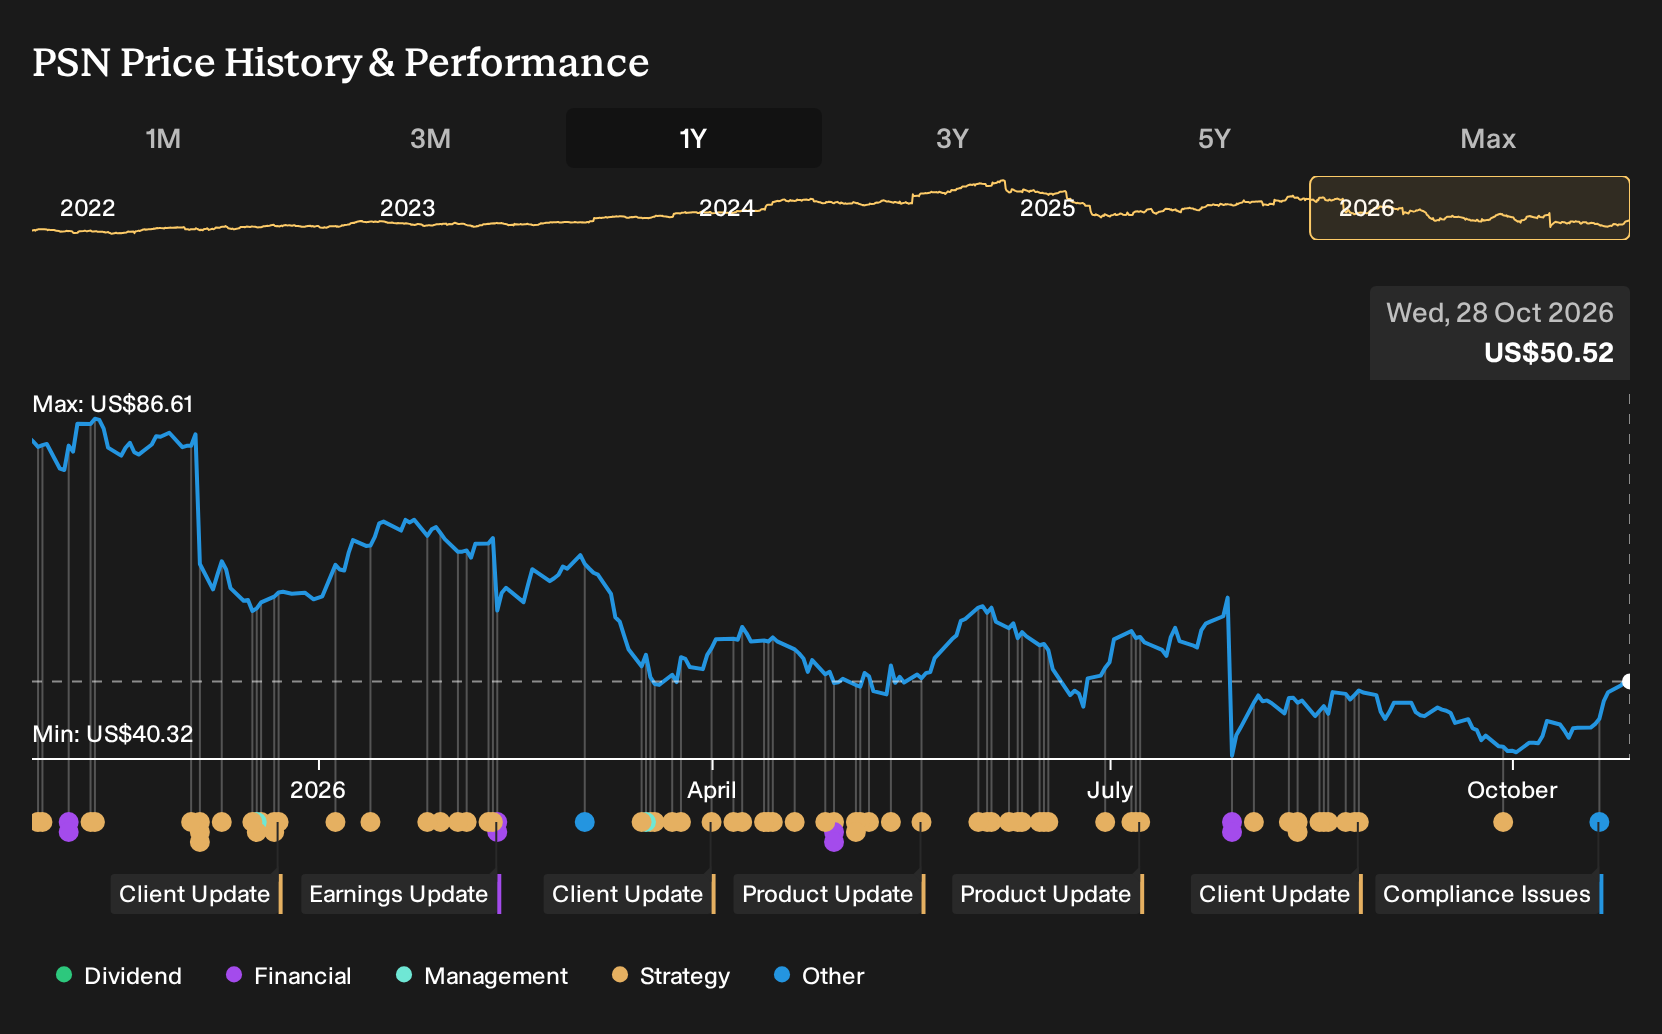
- Parsons reported Q3 2026 results with US$1,650.55 million in sales and US$54.15 million in net income, reaffirmed full year 2026 revenue guidance centered around US$6.35 billion, and confirmed that CFO Matt Ofilos will resign in early November 2026, with board member and former CFO George Ball stepping in as interim CFO.
- The combination of record profitability commentary, a guidance range slightly below analyst revenue expectations, and a leadership shift back to a long-tenured former finance chief gives investors fresh data points on Parsons’ current earnings power, cost discipline and succession planning.
- We will now explore how Parsons’ reaffirmed 2026 revenue guidance, alongside the CFO transition, could reshape the existing investment narrative.
Compare Parsons’ CFO change and PFAS contracts with peers by aligning them with 43 power grid technology and infrastructure stocks in the same infrastructure and defense supply chain.
Parsons Investment Narrative Recap
To stay invested in Parsons, you need to believe the mix shift toward higher margin federal tech, infrastructure work and environmental remediation keeps gaining traction as legacy contracts wind down. The reaffirmed 2026 revenue midpoint of about US$6.35b suggests management sees the core engine as intact, so the CFO handover looks more like an execution watchpoint than a thesis changer.
The near term swing factor remains how cleanly Parsons exits older joint ventures and lower return projects after recent one off charges and softer net income. The key risk is still contract timing tied to U.S. government budgets, where even modest delays can pressure reported revenue, margins and short term sentiment.
The PFAS soil remediation Success Memo is the announcement that matters most for Parsons right now. It effectively pre clears follow on federal contracts for its patented thermal conduction heating technology, turning PFAS work from a long shot idea into a pipeline that agencies can access quickly once funding is lined up.
For investors tracking catalysts, this creates a concrete, long duration opportunity in environmental cleanup that sits alongside transportation, water and defense tech programs. Execution risk shifts toward scaling projects profitably, managing any technical or regulatory hurdles and proving PFAS work converts backlog into cash without the kind of shocks seen in legacy construction exposures.
Parsons' current analyst framework points to US$7.2b in revenue and US$407.1 million in earnings by 2029, based on an assumed 4.6% yearly revenue growth rate and an earnings increase of about US$249.7 million from US$157.4 million today.
Uncover why Parsons' fair value signals an 18% potential upside to its current price that could narrow quickly as sentiment catches up.
Exploring Other Perspectives
One alternate view treats the Parsons CFO change itself as a key catalyst. The most optimistic analysts were already penciling in about US$7.7b of 2029 revenue and US$486.2 million of earnings before this update. You can read that as a bet that leadership stability, even with turnover, could sharpen execution. Your own take might differ, so it helps to compare these upbeat assumptions with more cautious scenarios.
Explore 3 other Parsons fair value estimates, including one that suggests the potential for as much as 134% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your Parsons research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Parsons. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Parsons' overall financial health at a glance.
Looking for more investment ideas beyond Parsons?
Once you have a view on Parsons, it can help to widen the lens and see how other companies stack up on income potential, balance sheet strength and long term durability using the Simply Wall St Screener.
- If income is your priority, focus on higher yielding opportunities by reviewing 6 dividend fortresses that pair payout potential with stability.
- If capital preservation comes first, narrow your watchlist to sturdier businesses by scanning a 32 resilient stocks with low risk scores that historically score well on resilience.
- If you prefer quality at a reasonable entry point, build a shortlist from a 26 high quality undervalued stocks that combine solid fundamentals with more modest pricing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com