


dormakaba Holding (SWX:DOKA) caught investor attention after shareholders approved a dividend of CHF 0.95 per share at the 20 October AGM, representing a 3.3% increase compared with last year.
The dividend decision comes at a time of improving momentum in dormakaba Holding's shares. The 90-day share price return is 22.05% and the 30-day gain is 10.02%, while the 3-year total shareholder return of 77.45% reflects a much stronger long-term performance compared with the more modest 2.05% total shareholder return over the past year.
Scan how dormakaba Holding compares with other companies that combine shareholder payouts with solid fundamentals by reviewing our curated 226 dividend fortresses list.
After a 22.05% move over 90 days and a higher dividend now in place, dormakaba Holding is no longer flying under the radar. Is this a sensible entry point, or would it be better to wait for a cheaper setup before buying in?
Most Popular Narrative: 8% Undervalued
Against the last close of CHF70.30, the most followed narrative pegs dormakaba Holding's fair value at CHF76.06, framing the recent share price strength as only partly reflecting what the business could be worth on its own numbers.
The current valuation suggests that the market remains cautious about how durable dormakaba Holding’s record 16.1% adjusted EBITDA margin, greater than 30% return on capital employed and planned growth in North America and vertical markets will be. This supports the view in this narrative that the stock is undervalued and that the setup is bullish rather than fully pricing in those achievements.
See why 4 investors see dormakaba Holding as 8% undervalued.
Result: Fair Value of CHF76.06 (UNDERVALUED)
Still, the dormakaba Holding story can shift quickly if recent revenue softness, especially in China and Southeast Asia, persists and if high margin segments see slower orders.
Find out about the key risks to this dormakaba Holding narrative.
Another View on dormakaba Holding’s Valuation
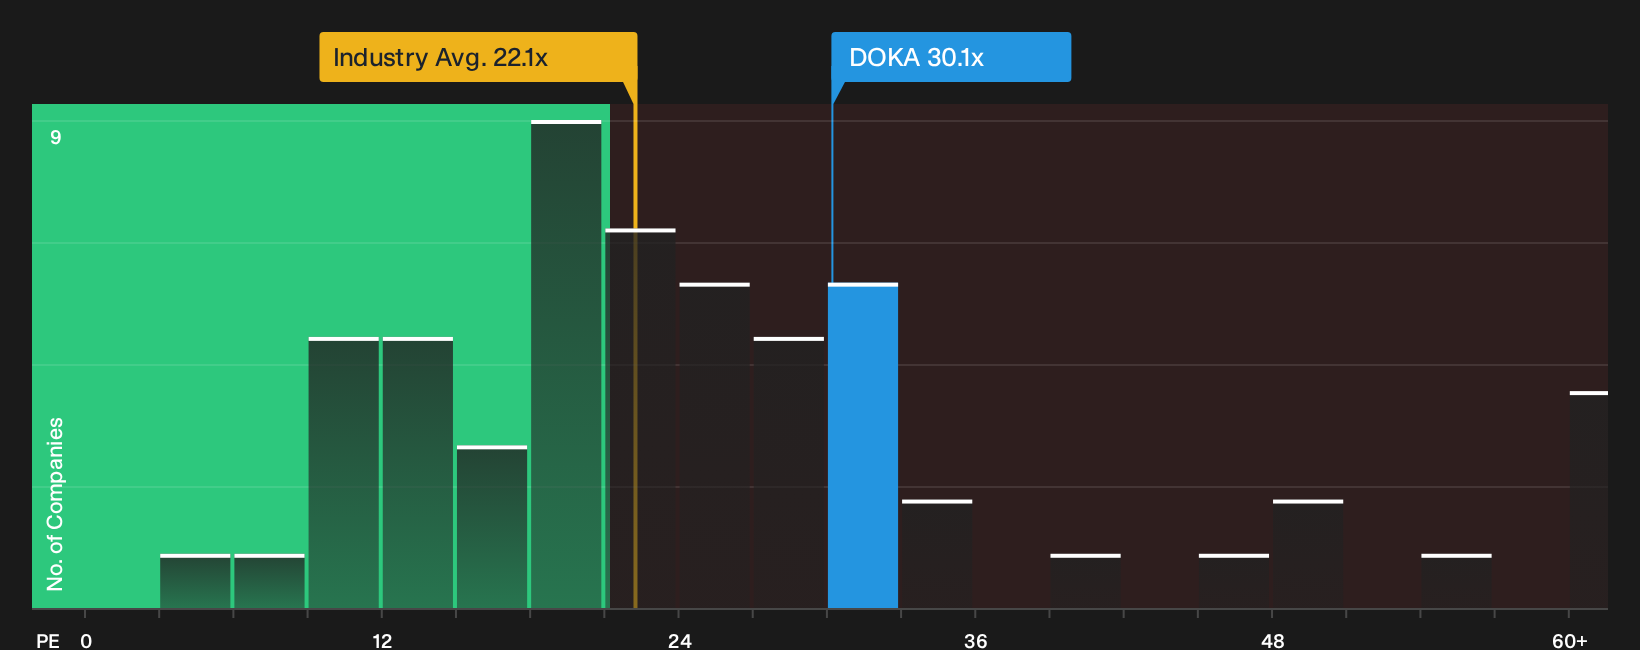
That 8% gap to the CHF76.06 fair value estimate is not the only lens investors are using. On earnings, dormakaba Holding trades on a P/E of 30.1x, compared with a fair ratio of 24.9x, peers at 28.8x and the wider European Building group at 22.6x. Is the premium a cushion or a risk if expectations slip?
To see what those earnings multiples imply about upside and downside in practice, take a closer look at our valuation breakdown, including how the fair ratio could become a gravity point for the share price over time, in the See what the numbers say about this price — find out in our valuation breakdown.
For a clearer visual of how dormakaba Holding lines up against its sector on this earnings measure, review the comparative chart in
Next Steps
Mixed messages on dormakaba Holding's valuation and risk reward profile can be useful, but only if you pressure test them against the underlying data yourself. To weigh the upside drivers against the concerns in detail, start with the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond dormakaba Holding?
If you stop with dormakaba Holding, you miss the chance to cross check your thinking against other quality setups that might better match your goals.
- Target stronger balance sheets and stress test your downside by scanning companies in our list of solid balance sheet and fundamentals (204 results).
- Hunt for mispriced quality and see which stocks our 189 high quality undervalued stocks flags as potential value opportunities.
- Grow your income stream by comparing dormakaba Holding's payout profile with companies highlighted in our 226 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com