


Modine Manufacturing (MOD) drew fresh attention after earnings estimates for the current quarter and fiscal year were revised downward and the stock was downgraded to a Zacks Rank #5, signaling anticipated underperformance.
Recent trading has been rough for Modine Manufacturing, with the share price down 18.0% over the past 30 days and 26.0% over 90 days. The 3-year total shareholder return of about 2.8x and the 5-year figure at more than 12x that starting level underline how strong the earlier run was and suggest recent momentum is fading rather than building.
Scan how Modine Manufacturing stacks up against other industrial plays under pressure by reviewing the hand-picked 26 high quality undervalued stocks that may offer a stronger risk-reward profile today.
After that kind of slide and with Modine Manufacturing still carrying solid revenue and net income figures, the real call is timing. Is this a reset worth leaning into now or a story to revisit at a lower entry point once the valuation work is done?
Most Popular Narrative: 52% Undervalued
Against a last close of $143.54, the most followed narrative for Modine Manufacturing points to a fair value near $302, which frames the recent pullback as a valuation gap rather than a broken business story.
The accelerating build out of data centers and the need for next generation cooling solutions are driving demand for Modine Manufacturing’s products, with management targeting data center revenue of about US$2b by fiscal 2028 after delivering US$1.1b in fiscal 2026 and guiding to 60% to 80% Data Center sales growth in fiscal 2027. This points to a significant revenue growth engine and potential operating leverage as new capacity fills.
See why 58 investors see Modine Manufacturing as 52% undervalued.
Result: Fair Value of $302.13 (UNDERVALUED)
Still, the Modine Manufacturing narrative depends on supply chain issues easing and data center contracts holding pricing power. Both of these factors could change if component shortages persist or margins compress.
Find out about the key risks to this Modine Manufacturing narrative.
Another View On Modine Manufacturing’s Valuation
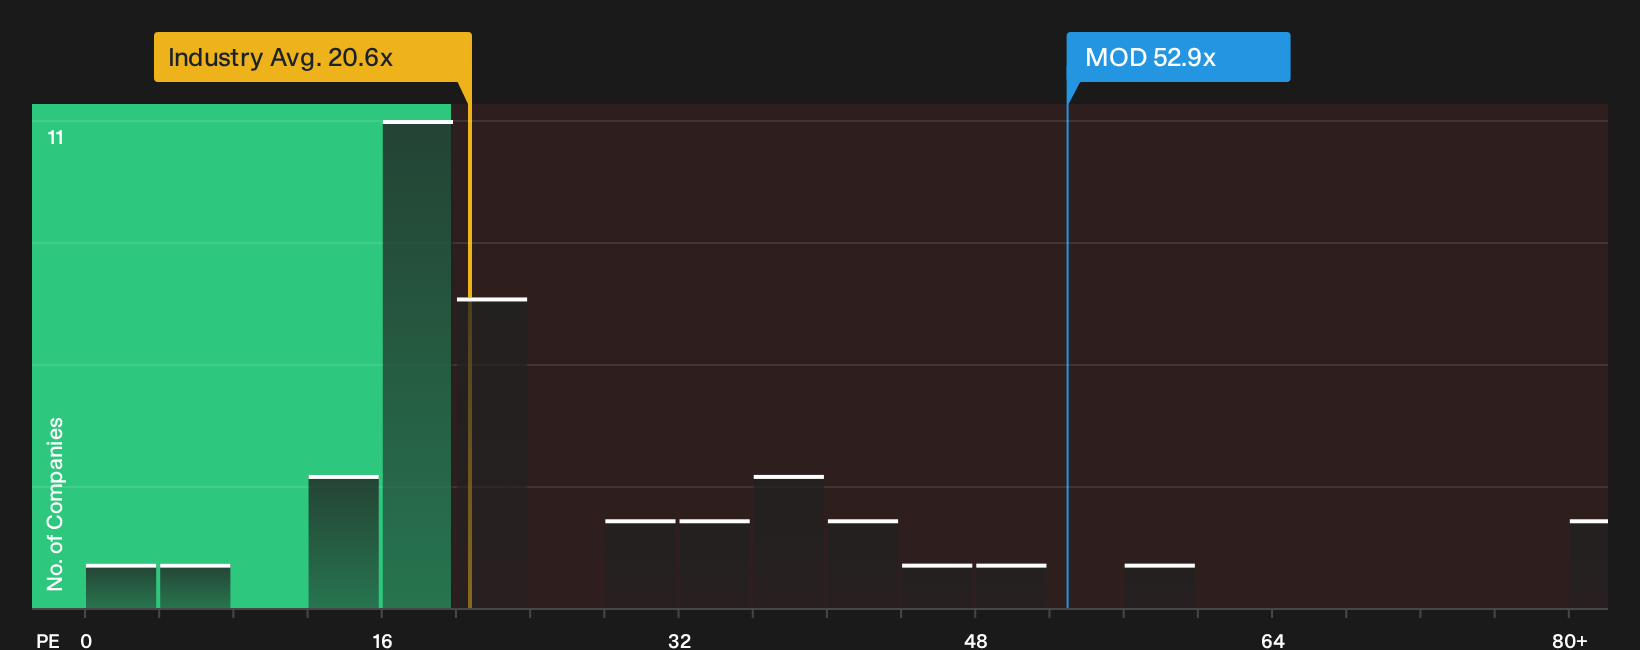
The fair value story for Modine Manufacturing leans heavily on future earnings, yet the current P/E of 52.9x tells a different story. It is more than double both the US Building industry at 20.6x and peers at 26.6x, even though the fair ratio points to 107.3x as a level the market could move toward. That gap leaves investors weighing whether today’s price is stretching expectations or whether the earnings line eventually has to catch up.
Before leaning on that comparison too hard, it is worth digging into how those ratios were built and what has to go right for them to hold up over time. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals dominate the Modine Manufacturing story right now. Move quickly, review the underlying numbers and decide where you stand on the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Modine Manufacturing?
Do not stop your research with Modine Manufacturing. Broaden your watchlist with fresh angles on quality, income, and resilience using the Simply Wall Street Screener.
- Hunt for potential future leaders before the crowd notices them by scanning a curated pool of 19 high quality undiscovered gems.
- Strengthen the income side of your portfolio by reviewing a focused set of reliable payers in the 6 dividend fortresses.
- Dial down portfolio stress and concentrate on durability by filtering for companies in the 32 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com